


 Sign In
 Sign In
Key takeaways:
Preparing to send your teen to post-secondary is an exciting — and emotional — milestone. But as you help them prepare for the next big step, it's only natural to wonder how to pay for university or college without overwhelming your family’s finances.
From tuition fees to living expenses, there’s a lot to consider — and also plenty of ways to ensure your child secures the student financing they need to succeed.
Here’s how to help you — and your teen — feel more informed and comfortable with the student financing process and the higher education journey ahead.
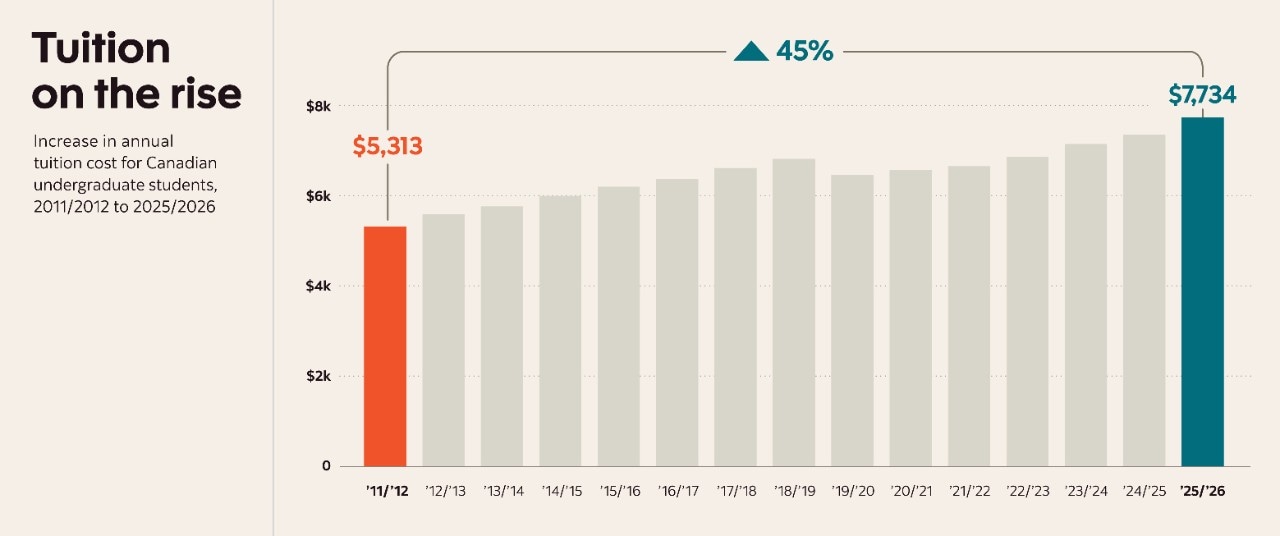
In 2025, the average cost of tuition for an undergraduate program in Canada was $7,734 per year,1 although this figure can vary widely based on the province and program. For Canadian citizens and permanent residents, tuition fee payments typically range from about $3,754 to $9,988 per year, depending on the school and the program.1
For example, if your child wants to enroll in a professional undergraduate program like dentistry or law, expect the costs to be substantially higher.
For international students, tuition is even steeper — averaging around $41,746 per year for undergraduate studies.1 Exchange rates may also affect the final cost for international payments.
On top of tuition fees, you should also budget for the cost of books and other course materials, typically between $1,000 and $2,000 per academic year.2 But these annual costs can also vary depending on the post-secondary institution and the program. Courses like science, engineering, business and technology may require more expensive textbooks or specialized supplies.
On top of tuition fees, you should also budget for the cost of books and other course materials. At some post-secondary institutions, students can expect to spend between $1,000 and $3,000 per academic year.4
However, annual costs can vary depending on the post-secondary institution and the program — science, engineering, business and technology courses may require more expensive textbooks or specialized supplies. And this doesn’t include residence fees! Check with the office of student services for a breakdown of what you can expect to pay.
Cost of living can vary greatly, depending on whether your child plans to live at home, in residence or off campus. If the goal is to save money, having your child live at home while they attend post-secondary can make a big difference.
However, if they plan to go to school out of province, they’ll need to budget for living expenses, including residence fees. Following are some living costs to consider.
Accommodation
There are pros and cons to living on and off campus. On-campus living is often more convenient and can help to reduce travel costs, but it comes with residence fees. In an off-campus rental, students can reduce their costs by splitting rent and utilities with roommates.
Where your teen decides to go to school can also have a huge impact on accommodation costs. An off-campus rental in Toronto or Vancouver is likely to be much more expensive than a rental in a small town in Nova Scotia or Saskatchewan.
Food
Some schools have mandatory meal plans for first-year university students who live in their residences. A meal program can cost thousands of dollars per academic year.
Of course, those living off campus still need to eat! Instead of a meal plan, they have to budget for groceries and be ready to do their own shopping and food preparation.
Transportation
A transit pass is often included in the cost of tuition. Using public transport is one way to cut costs. But if your teen plans to drive to school, they must consider the cost of gas and parking in their overall budget.
Students who attend school outside of their home province or territory should also consider the cost of travelling home for holidays or summer vacations. Always inquire about student discounts whenever booking flights or train fares.
Entertainment
Being a student is a lot of work, but it can also be a ton of fun. Don't forget to leave some room in the budget for entertainment costs. This might include a little bit of money each month to pay for streaming services or going out for a bite to eat.
If you're wondering how your kid can finance their post-secondary education, there are a few options.
Registered Education Savings Plan (RESP)
If you invested in a Registered Education Savings Plan (RESP), it’s time to put this money to good use. Once they enroll in a qualifying post-secondary program, you can use these funds to cover tuition payments, residence fees or other education-related costs.

Also read
Learn more about RESPs and how to make most use of this program.
Government grants and student loans
If you're looking for support beyond an RESP, the Government of Canada offers grants and student loans to eligible part-time and full-time students through the National Student Loans Service Centre (NSLSC). Students apply for these loans through their province or territory. For example, in Ontario, students apply through the Ontario Student Assistance Program (OSAP), which combines both provincial and federal funding into a single application.

DID YOU KNOW?
Federal student loans now carry 0% interest after graduation.
If your child applies for financial aid, they’re automatically assessed for government grants, which don’t need to be paid back. But student loans must be repaid after graduation. Make sure your child knows about repayment deadlines to avoid late fees or late payment penalties. As of 2023, federal student loans carry 0% interest after graduation, making repayment more affordable.
Student grans and student loans eligibility
Eligibility for government grants and student loans is based on several factors. How much they qualify for may depend on:
- Province or territory of residence
- Family household income (how much you make can impact how much your kid can receive in student financing)
- If they have dependents
- Tuition fees and living expenses
- If they have a disability
Based on their eligibility, your teen may receive enough money to cover their tuition fees and living expenses. If not, there are other options available to fill the gaps, such as private student loans.

DID YOU KNOW?
In 2025, the average cost of tuition for an undergraduate program in Canada was $7,734.1
Scholarships, bursaries and university financial aid
In addition to government funding, many universities and colleges may offer their own scholarships, bursaries, grants and financial assistance programs. These programs are typically based on merit, financial need or a combination of both, and usually require a separate application through the school's student services or financial aid office.
Encourage your teen to research the school's financial aid options early and apply before the deadline — it’s a great way to reduce costs without taking on extra debt.
Private student financing
Private student loans are usually issued by banks and other financial institutions. A popular type of private student loan is a student line of credit.
With a line of credit, you can borrow money repeatedly up to a certain amount — like a credit card. Your teen can use a student line of credit to borrow money when they need it, pay it back and then borrow again up to their credit limit.
Products like Scotiabank’s ScotiaLine® Personal Line of Credit for Students offer flexible payment plans and interest-only installments during school, with a 12-month grace period for principal payments after graduation (monthly interest payments only).3
A line of credit can be used to pay for expenses related to post-secondary education, including tuition fees, books, residence fees, food or transportatio
READ MORE: Financial tips you need to know after graduating college or university
There are a few notable differences between a student loan and a student line of credit:
| Government student loan | Private student line of credit |
Loan amount | Limits on the maximum amount of combined federal and provincial student loans a student can receive | Student can often borrow more money than they can get with a government student loan |
Co-signer requirement | No co-signer required | A co-signer may be required without a strong credit history |
Repayment amount | Comes as a lump sum amount that must be repaid in full when a student finishes school | Student is only responsible for repaying the amount of money they use Some products, like the ScotiaLine® Personal Line of Credit for Students, offer deferred principal payments, with interest-only payments while a student is still in school and for 12 months post-graduation Some products, like the ScotiaLine® Personal Line of Credit for Students, offer deferred principal payments, with interest-only payments while your kid is still in school and for 12-months post-graduation.3 |
Interest payments | No interest is charged on student loans | Interest payments begin as soon as they borrow the money |
Access to repayment assistance | Eligible to apply to the Repayment Assistance Plan (RAP) | Not eligible for RAP |
If you’re interested in learning more, check out our guide to student financing in Canada.
Beyond the different student financing options available, there are other ways to support your child in their dreams of obtaining a higher education.
Open a student account
Encourage your teen (or help them) set up a student account early. This ensures they have a secure place to store any funds from scholarships, grants, bursaries or student loans.
You can check out Scotiabank's Preferred Package for Students and Youth, which is designed specifically for student life.4 For eligible account holders, this account offers no monthly account fees, unlimited debit and Interac e-Transfer† transactions5 and the opportunity to earn Scene+™ points on everyday purchases.6
If your teen is an international student, opening a Canadian bank account simplifies international money transfers and managing day-to-day expenses.
Set up payment options
Make sure your child understands payment options, including online banking, international payments and payment processing times (which can take a few business days). They should also know how to add their school as a payee using their student number and account number to avoid missing a due date.
Help set up payment options
Make sure your child understands payment options, including online banking, international payments and payment processing times (which can take a few business days). They should also know how to add the school as a payee using their student number and account number to avoid missing a due date.
Apply for a student credit card
As long as your teen is the age of majority in your province, regardless of where they attend school, you can assist them in signing up for a student credit card. Scotiabank offers no- and low-annual fee credit cards7 especially for students, and on select premium credit cards, Preferred Package for Students and Youth account holders are eligible for an ongoing $40 annual fee rebate (on eligible credit cards).8
READ MORE: Everything you need to know about student credit cards
Student credit cards are a great way to start building a strong credit history while getting rewarded for everyday spending. As a bonus, you’ll also be able to give your teen advice on responsible credit card use and avoiding unnecessary debt — lessons best learned sooner than later.
If your teen hasn’t reached the age of majority for your province or doesn’t meet the eligibility requirements for a student credit card, you can add them as an additional cardholder to your account. Although this won’t help build their credit history and you’ll be responsible for their spending, it will allow you to monitor how they’re using credit.9
Assist with applications
You can help your teen secure the student financing they need by assisting them with applications for student loans, bursaries and grants — or by exploring a private student line of credit if they require additional funding.
Knowing how your teen will pay for tuition is only the first step! They also need to make tuition payments. Some tips to make this step a little easier:
- Confirm the details with the school: Always check with their post-secondary institution for specific payment options, accepted payment methods, deadlines and extra fees that may apply.
- Pay online: Most schools allow online payments via online banking.
- Pay in person: Payments can also be made in person at your local bank or by using a money order.
- Use a credit card (if accepted): Credit card payments may be accepted, but a convenience fee might apply.
- Allow time for processing: Make sure your teen allows time for payment processing to avoid missing fee payment deadlines — some schools need up to three business days.
- Avoid late fees: Watch for late fees if payments are delayed.
- Know the refund process: Schools typically issue refunds for overpayments on a student pay account.
Getting ready to head off to post-secondary is a big deal — not just for your teen, but for you, too. But this exciting time can also feel overwhelming if you’re unfamiliar with the ins and outs of scholarships, grants and student loans. Start researching different schools and funding options early to give yourselves plenty of time to make informed decisions and build a realistic budget.
Effective starting on and after June 22, 2026 (the “Effective Date”), clients who have a Preferred Package account (“Account”) will receive an annual fee rebate of $40 (“Annual Fee Rebate”) on one Eligible Card Account where they are the primary cardholder (“Eligible Card”), beginning on the first Anniversary Date after June 22, 2026 (and on each annual Anniversary Date thereafter), provided all of the following conditions are met: (i) there must be at least $15,000 in Qualifying Purchases posted to the Eligible Card Account in the 12 monthly statement periods prior to the month in which the Eligible Card Account’s annual fee is charged to the Eligible Card Account (the “Annual Anniversary Spend Amount"), and (ii) both the Eligible Card Account and the Account must be open and in good standing at the time the Annual Fee Rebate is applied. The Rebate should appear on your Eligible Card statement approximately on, or within the first two statements after the annual fee is charged to the Eligible Card Account.
The first-year annual fee(s) charged on your Eligible Card Account after the Effective Date is not eligible for an Annual Fee Rebate. The Annual Fee Rebate applies, even if you opened an Eligible Card Account prior to the Account Open Date.
Each Account will only receive one Annual Fee Rebate regardless of the number of accountholders on the Account or Eligible Cards held or opened on the Eligible Card Account. If you are the primary cardholder of multiple Eligible Cards, the Annual Fee Rebate will be applied to the annual fee that is charged first on an Eligible Card after the Account Open Date if you meet the Annual Anniversary Spend Amount.
If your Eligible Card Account has an annual fee(s) that is greater than the amount of the Annual Fee Rebate, you are responsible for any difference in annual fee(s) after the Annual Fee Rebate is applied. All other fees and charges applicable to the Eligible Card Account continue to apply.
The Annual Fee Rebate is subject to change and cannot be combined with any other offer including an annual fee rebate or waiver offer. Annual fees, rates and other features for Eligible Cards are subject to change. We may limit or revoke the Annual Fee Rebate(s) without notice if we believe there is suspicious or fraudulent activity, if the offer is being abused, or if you receive an Annual Fee Rebate in error.
“Account Open Date” means the date that the Account is opened.
“Anniversary Date” means the date that is one year after the annual fee is first charged to your Eligible Card Account and every 12 months thereafter.
“Eligible Card Accounts” are currently the Scotiabank Gold American Express®, Scotiabank Passport® Visa Infinite +* and Scotia Momentum® Visa Infinite +* credit cards. Eligible Card Accounts are subject to change.
A “Qualifying Purchase” is a Purchase (as defined in your credit agreement for your Eligible Card Account) that is posted to your Eligible Card Account, less any refunds, returns or other similar credits on your Eligible Card Account. Qualifying Purchases exclude cash advances (including balance transfers and cash-like transactions), interest charges, fees and payments posted to your Eligible Card Account.
