

- Mexico: October inflation overshoots consensus, driven by non-core pressures; Producer prices jump; Auto production and exports fall while domestic sales grow
MEXICO: OCTOBER INFLATION OVERSHOOTS CONSENSUS, DRIVEN BY NON-CORE PRESSURES
In October, headline inflation picked up (chart 1), rising from 3.45% to 3.75%, above the 3.65% consensus, and remaining below 4% for the sixth consecutive month, although with strong pressures in both core and non-core components. On a sequential monthly basis, headline inflation rose 0.65%, core inflation 0.34%, and non-core inflation picked up again by 1.75%.
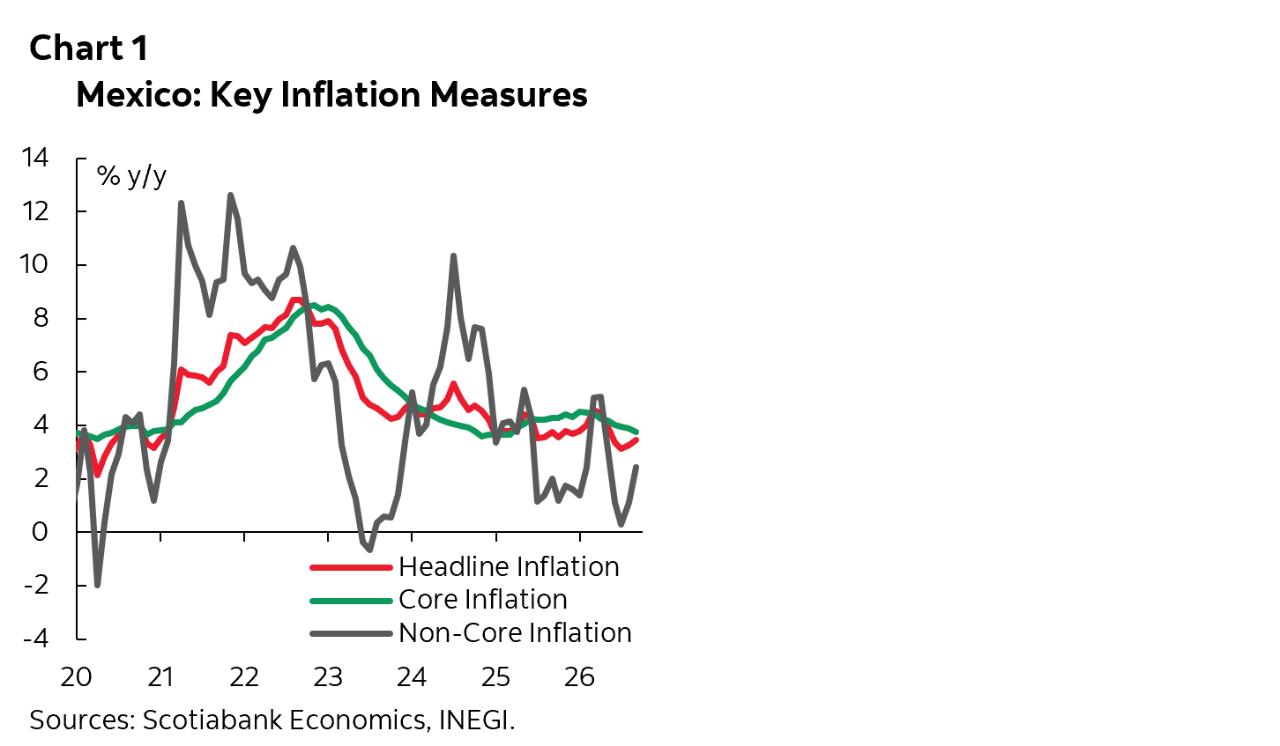
Core inflation accelerated from 3.75% to 3.80%, also above the 3.78% consensus. Within it, goods rose from 3.21% to 3.25%, and services from 4.27% to 4.32%—with education holding at 5.84% and housing at 3.53%.
Meanwhile, non-core inflation accelerated again, rising from 2.45% to 3.59%, with the agricultural component at 2.99%—with fruits and vegetables at 13.89% and livestock products at -3.61%; meanwhile, energy and government-approved tariffs stood at 4.06%.
Among the products with the largest upward impact—ranked by greatest incidence—were electricity, with a monthly change of 18.51%, air transportation at 26.36%, tomatoes at 9.68%, LP domestic gas at 3.67%, and tomatillos at 35.58%; meanwhile, internet, telephone and pay-tv packages, potatoes, and lemons kept their prices lower this month.
PRODUCER PRICES KEPT CLIMBING IN OCTOBER
Also in October, Mexico's National Producer Price Index (INPP), including oil, continued to rise, with an annual change of 5.60% and a monthly increase of 1.92%—up from 4.05% y/y and 1-47% m/m. Primary activities increased slightly on an annual basis by 1.05%, although they fell 0.47% month over month, while secondary activities rose 6.08% annually and 2.44% monthly—with increases in mining (31.71%), construction (6.23%), and manufacturing (4.46%), while public utilities declined (-5.74%). Meanwhile, service activities prices grew 5.24% annually and 1.21% monthly.
AUTOMOTIVE SECTOR: PRODUCTION AND EXPORTS FALL WHILE DOMESTIC SALES GROW
In October, the automotive landscape showed mixed signals (chart 2). Production reached 302,803 vehicles, an annual change of -17.7%, deepening its decline from the previous -15.5%. Exports also fell by 17.9% year over year, with 258,137 vehicles exported. On the other hand, domestic sales grew, with 137,395 light vehicles sold, an annual increase of 3.1% (down from 7.9%). In the cumulative January–October period, production totaled 3,254,062 vehicles, an annual change of -4.0%; sales registered 1,287,225 units, a change of 4.8%; and exports reached 2,786,76 units, an annual change of -3.28%.
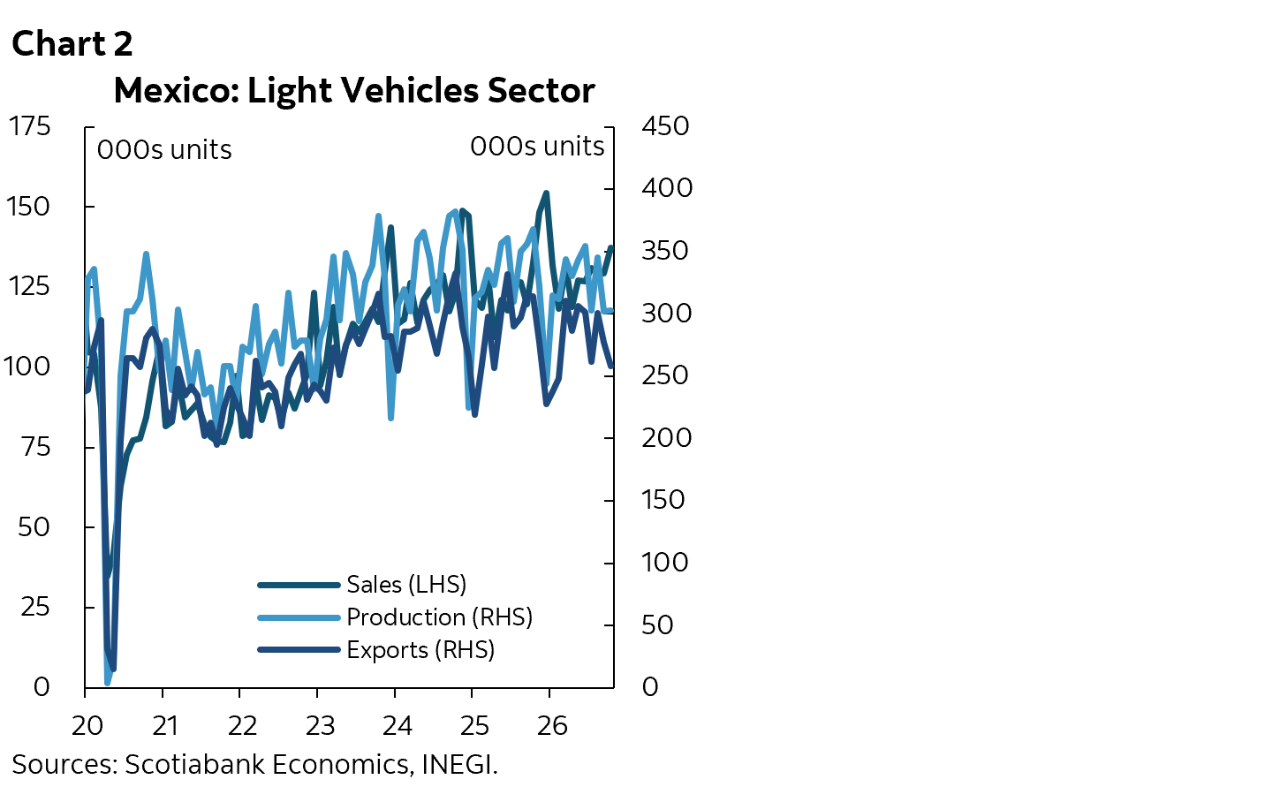
—Rodolfo Mitchell, Miguel Saldaña & Martha Cordova
DISCLAIMER
This report has been prepared by Scotiabank Economics as a resource for the clients of Scotiabank. Opinions, estimates and projections contained herein are our own as of the date hereof and are subject to change without notice. The information and opinions contained herein have been compiled or arrived at from sources believed reliable but no representation or warranty, express or implied, is made as to their accuracy or completeness. Neither Scotiabank nor any of its officers, directors, partners, employees or affiliates accepts any liability whatsoever for any direct or consequential loss arising from any use of this report or its contents.
These reports are provided to you for informational purposes only. This report is not, and is not constructed as, an offer to sell or solicitation of any offer to buy any financial instrument, nor shall this report be construed as an opinion as to whether you should enter into any swap or trading strategy involving a swap or any other transaction. The information contained in this report is not intended to be, and does not constitute, a recommendation of a swap or trading strategy involving a swap within the meaning of U.S. Commodity Futures Trading Commission Regulation 23.434 and Appendix A thereto. This material is not intended to be individually tailored to your needs or characteristics and should not be viewed as a “call to action” or suggestion that you enter into a swap or trading strategy involving a swap or any other transaction. Scotiabank may engage in transactions in a manner inconsistent with the views discussed this report and may have positions, or be in the process of acquiring or disposing of positions, referred to in this report.
Scotiabank, its affiliates and any of their respective officers, directors and employees may from time to time take positions in currencies, act as managers, co-managers or underwriters of a public offering or act as principals or agents, deal in, own or act as market makers or advisors, brokers or commercial and/or investment bankers in relation to securities or related derivatives. As a result of these actions, Scotiabank may receive remuneration. All Scotiabank products and services are subject to the terms of applicable agreements and local regulations. Officers, directors and employees of Scotiabank and its affiliates may serve as directors of corporations.
Any securities discussed in this report may not be suitable for all investors. Scotiabank recommends that investors independently evaluate any issuer and security discussed in this report, and consult with any advisors they deem necessary prior to making any investment.
This report and all information, opinions and conclusions contained in it are protected by copyright. This information may not be reproduced without the prior express written consent of Scotiabank.
™ Trademark of The Bank of Nova Scotia. Used under license, where applicable.
Scotiabank, together with “Global Banking and Markets”, is a marketing name for the global corporate and investment banking and capital markets businesses of The Bank of Nova Scotia and certain of its affiliates in the countries where they operate, including; Scotiabank Europe plc; Scotiabank (Ireland) Designated Activity Company; Scotiabank Inverlat S.A., Institución de Banca Múltiple, Grupo Financiero Scotiabank Inverlat, Scotia Inverlat Casa de Bolsa, S.A. de C.V., Grupo Financiero Scotiabank Inverlat, Scotia Inverlat Derivados S.A. de C.V. – all members of the Scotiabank group and authorized users of the Scotiabank mark. The Bank of Nova Scotia is incorporated in Canada with limited liability and is authorised and regulated by the Office of the Superintendent of Financial Institutions Canada. The Bank of Nova Scotia is authorized by the UK Prudential Regulation Authority and is subject to regulation by the UK Financial Conduct Authority and limited regulation by the UK Prudential Regulation Authority. Details about the extent of The Bank of Nova Scotia's regulation by the UK Prudential Regulation Authority are available from us on request. Scotiabank Europe plc is authorized by the UK Prudential Regulation Authority and regulated by the UK Financial Conduct Authority and the UK Prudential Regulation Authority.
Scotiabank Inverlat, S.A., Scotia Inverlat Casa de Bolsa, S.A. de C.V, Grupo Financiero Scotiabank Inverlat, and Scotia Inverlat Derivados, S.A. de C.V., are each authorized and regulated by the Mexican financial authorities.
Not all products and services are offered in all jurisdictions. Services described are available in jurisdictions where permitted by law.