

- Chile: October CPI at 0.5% m/m (4.5% y/y) in line with our expectation
- Peru: Macroeconomic expectations reinforce the likelihood that the BCRP will keep its policy rate unchanged
CHILE: OCTOBER CPI AT 0.5% M/M (4.5% Y/Y) IN LINE WITH OUR EXPECTATION
Benign inflation composition does not reduce the likelihood of a 25bp policy rate hike in December
October CPI came in at 0.5% m/m, in line with our point forecast, although below both market consensus and UF forward pricing expectations (Bloomberg: 0.6%, FRW: 0.56%). Core inflation excluding volatile items (ex-volatiles) stood at 0.0% m/m, slightly below our 0.1% forecast, but almost entirely explained by the unprecedented 14.7% decline in the Internet connection item, which subtracted 0.11pp from core CPI and 0.07pp from headline CPI. We maintain our expectation of a policy rate increase at the December meeting.
The decline in inflation breadth was driven by Cyber-sensitive goods. As expected, goods diffusion declined relative to the previous month, reflecting discounts associated with the Cyber Monday event held in early October (charts 1 and 2). Based on our estimates, the contribution of these price declines to headline CPI was -0.09pp, smaller than in October last year (-0.15pp), partly due to fewer products posting price declines, but also because the declines were concentrated in items with a lower weight in the CPI basket.
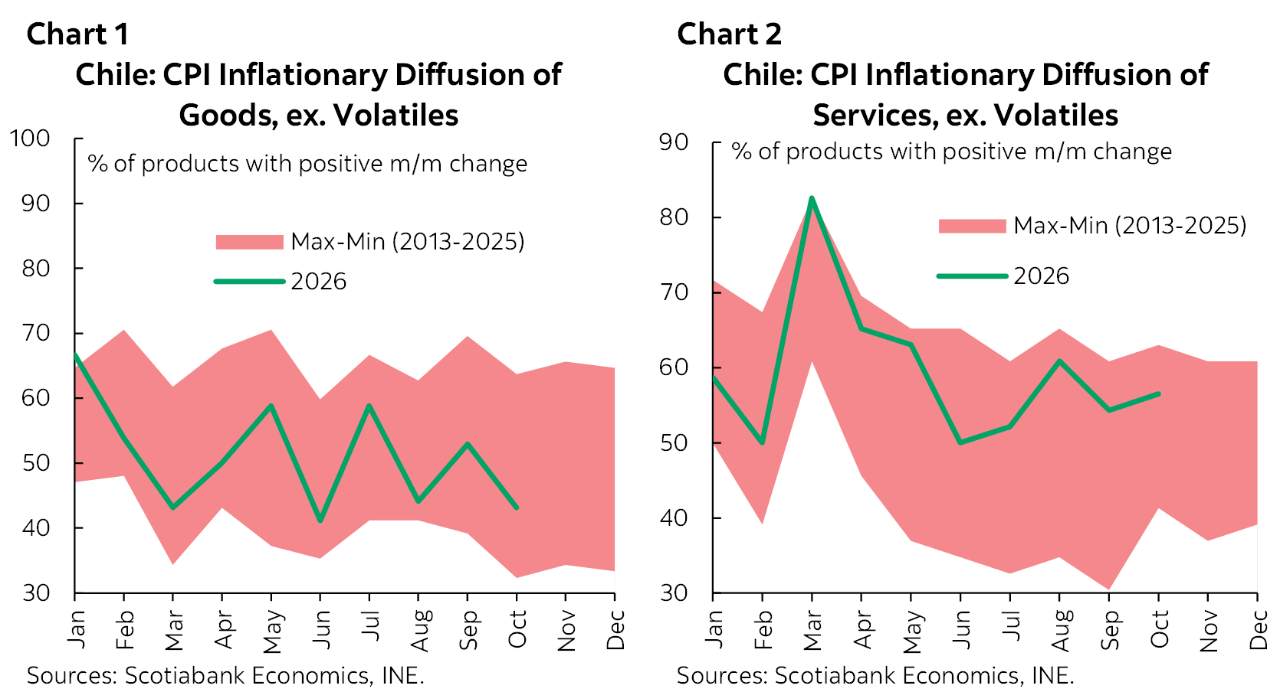
October inflation was largely explained by volatile components, particularly fuels and fresh vegetables. The unexpected drop in Internet connection prices (-14.7%) pushed monthly core inflation down to zero, leaving headline inflation mainly determined by the expected increase in fuel prices (gasoline, diesel and LPG) and higher fresh vegetable prices, which have been affected by this year's weather conditions and are following a pattern similar to that observed in 2023.
Preliminarily, we forecast November CPI at 0.5% m/m (4.7% y/y), with another positive contribution from fuels. Next week, ENAP is set to announce further fuel price increases, which will be the only adjustment implemented this month, as the next fuel pricing decision will take place in December. We estimate another increase in gasoline prices of around CLP39/lt and a rise of around CLP90/lt in diesel prices, implying a CPI impact of roughly 0.2pp. At the same time, we expect part of the negative contribution from goods prices associated with October's Cyber Monday discounts to reverse in November. Together with additional increases in food prices, these factors would explain close to 60% of the CPI increase we project for November.
Monetary policy implications. The somewhat benign nature of this inflation print, which was in line with our forecast, does not reduce the likelihood of a 25bp increase at the December monetary policy meeting. However, it does suggest less urgency for a subsequent hike in January. Following this release, the probability of bringing the policy rate to 5.0% appears higher at the March meeting. This does not materially alter our baseline scenario, which continues to incorporate a 25bp hike in December and an additional 25bp increase during Q1-27.
—Aníbal Alarcón
PERU: MACROECONOMIC EXPECTATIONS REINFORCE THE LIKELIHOOD THAT THE BCRP WILL KEEP ITS POLICY RATE UNCHANGED
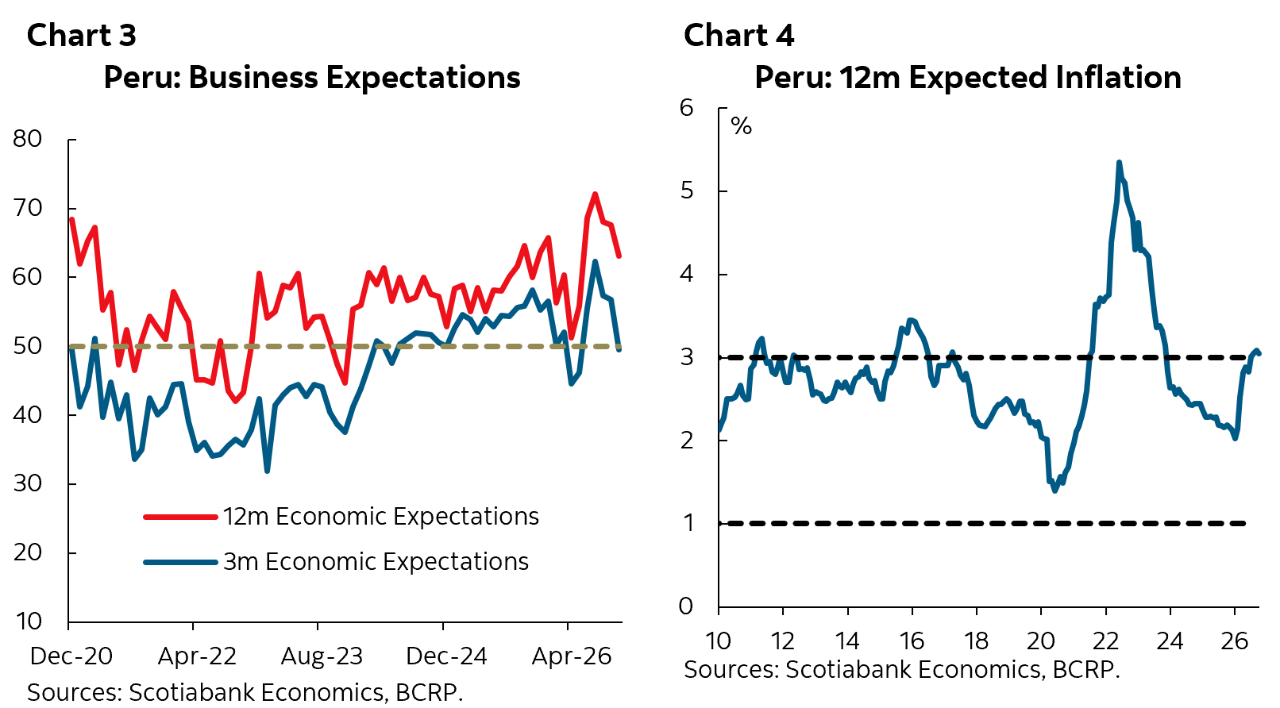
The Central Reserve Bank of Peru (BCRP) recently released its October Survey of Macroeconomic Expectations. The results point to a deterioration in business confidence and some easing in 12-month inflation expectations.
Business expectations for the 3- and 12-month horizons deteriorated once again. In particular, 3-month expectations moved back into contractionary territory, amid the effects of the El Niño phenomenon, which is already affecting some economic sectors, including agriculture and fishing. However, this deterioration is likely to be temporary, as 12-month expectations remain in expansionary territory and above the 60-point mark.
As for 12-month inflation expectations, October marked the fourth consecutive month in which they remained above the BCRP’s target range (1%–3%), although they edged down from 3.09% to 3.05%. This figure does not yet reflect the impact of the rebound in headline inflation in October (5.25%), as the survey was conducted beforehand. Inflation expectations are therefore likely to increase again in November. However, they should return to levels close to 3.0% in December and could even fall below that level.
Against this backdrop, the likelihood that the BCRP will keep its policy rate unchanged at 4.25% on Thursday, November 12th, has increased.
The survey also provided economic agents’ expectations for the main macroeconomic indicators:
- 2026 inflation expectations: The estimate increased from 4.1% to 4.5%, remaining below our current forecast of 4.8%. However, we see the risks as tilted toward a higher outcome.
- 2026 economic growth expectations: The estimate remained unchanged at 3.2%, in line with our forecast.
- End-2026 exchange rate expectations: The estimate increased from PEN 3.36 to PEN 3.39 per US dollar. Our current forecast remains at 3.35, a projection we have maintained since December 2025. However, we see the risks as tilted toward an exchange rate within a range of 3.35–3.40.
—Ricardo Avila
DISCLAIMER
This report has been prepared by Scotiabank Economics as a resource for the clients of Scotiabank. Opinions, estimates and projections contained herein are our own as of the date hereof and are subject to change without notice. The information and opinions contained herein have been compiled or arrived at from sources believed reliable but no representation or warranty, express or implied, is made as to their accuracy or completeness. Neither Scotiabank nor any of its officers, directors, partners, employees or affiliates accepts any liability whatsoever for any direct or consequential loss arising from any use of this report or its contents.
These reports are provided to you for informational purposes only. This report is not, and is not constructed as, an offer to sell or solicitation of any offer to buy any financial instrument, nor shall this report be construed as an opinion as to whether you should enter into any swap or trading strategy involving a swap or any other transaction. The information contained in this report is not intended to be, and does not constitute, a recommendation of a swap or trading strategy involving a swap within the meaning of U.S. Commodity Futures Trading Commission Regulation 23.434 and Appendix A thereto. This material is not intended to be individually tailored to your needs or characteristics and should not be viewed as a “call to action” or suggestion that you enter into a swap or trading strategy involving a swap or any other transaction. Scotiabank may engage in transactions in a manner inconsistent with the views discussed this report and may have positions, or be in the process of acquiring or disposing of positions, referred to in this report.
Scotiabank, its affiliates and any of their respective officers, directors and employees may from time to time take positions in currencies, act as managers, co-managers or underwriters of a public offering or act as principals or agents, deal in, own or act as market makers or advisors, brokers or commercial and/or investment bankers in relation to securities or related derivatives. As a result of these actions, Scotiabank may receive remuneration. All Scotiabank products and services are subject to the terms of applicable agreements and local regulations. Officers, directors and employees of Scotiabank and its affiliates may serve as directors of corporations.
Any securities discussed in this report may not be suitable for all investors. Scotiabank recommends that investors independently evaluate any issuer and security discussed in this report, and consult with any advisors they deem necessary prior to making any investment.
This report and all information, opinions and conclusions contained in it are protected by copyright. This information may not be reproduced without the prior express written consent of Scotiabank.
™ Trademark of The Bank of Nova Scotia. Used under license, where applicable.
Scotiabank, together with “Global Banking and Markets”, is a marketing name for the global corporate and investment banking and capital markets businesses of The Bank of Nova Scotia and certain of its affiliates in the countries where they operate, including; Scotiabank Europe plc; Scotiabank (Ireland) Designated Activity Company; Scotiabank Inverlat S.A., Institución de Banca Múltiple, Grupo Financiero Scotiabank Inverlat, Scotia Inverlat Casa de Bolsa, S.A. de C.V., Grupo Financiero Scotiabank Inverlat, Scotia Inverlat Derivados S.A. de C.V. – all members of the Scotiabank group and authorized users of the Scotiabank mark. The Bank of Nova Scotia is incorporated in Canada with limited liability and is authorised and regulated by the Office of the Superintendent of Financial Institutions Canada. The Bank of Nova Scotia is authorized by the UK Prudential Regulation Authority and is subject to regulation by the UK Financial Conduct Authority and limited regulation by the UK Prudential Regulation Authority. Details about the extent of The Bank of Nova Scotia's regulation by the UK Prudential Regulation Authority are available from us on request. Scotiabank Europe plc is authorized by the UK Prudential Regulation Authority and regulated by the UK Financial Conduct Authority and the UK Prudential Regulation Authority.
Scotiabank Inverlat, S.A., Scotia Inverlat Casa de Bolsa, S.A. de C.V, Grupo Financiero Scotiabank Inverlat, and Scotia Inverlat Derivados, S.A. de C.V., are each authorized and regulated by the Mexican financial authorities.
Not all products and services are offered in all jurisdictions. Services described are available in jurisdictions where permitted by law.