

- Mexico: September remittances grow 1.6% despite a 6.3% drop in transfers; Fixed investment sustains its uptrend; Private consumption—imports lead, domestic demand lags; Consumer confidence—household optimism versus country outlook
MEXICO: SEPTEMBER REMITTANCES GROW 1.6% DESPITE A 6.3% DROP IN TRANSFERS
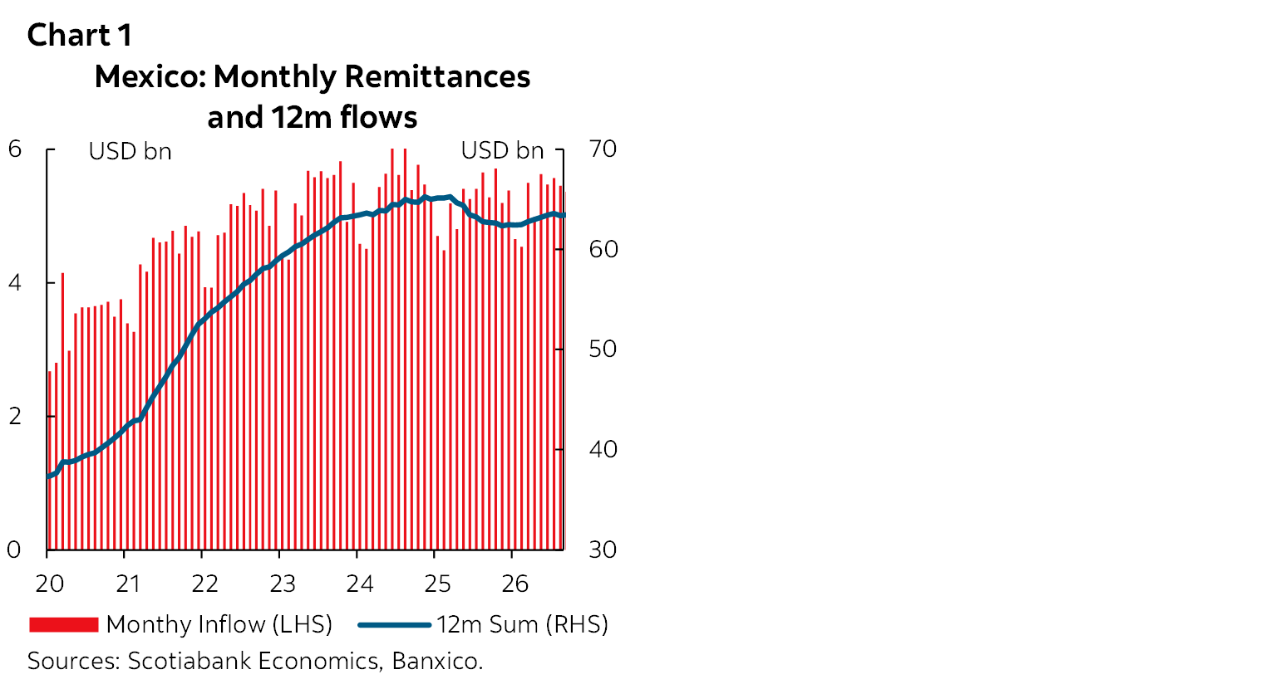
In September, remittances to Mexico totaled US$5,362 million, a 1.6% increase from a year earlier (chart 1). The number of transfers remained in negative territory, with a change of -6.3%, while the average amount per transfer stood at US$426.3, up 8.4% year over year. In the January–September period, inflows totaled US$47,164 million, a 2.1% annual increase. Meanwhile, over the last twelve months, inflows reached US$63,452 million.
FIXED INVESTMENT SUSTAINS ITS UPTREND
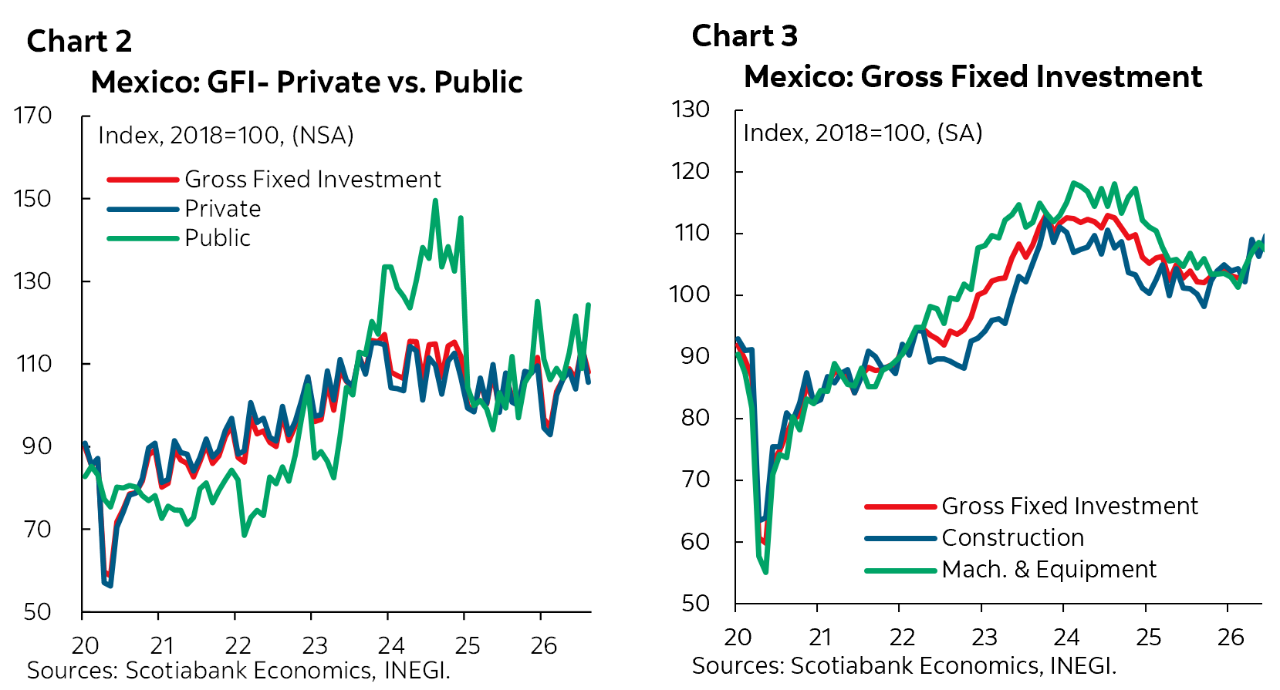
In August, INEGI's Monthly Gross Fixed Capital Formation Indicator showed that gross fixed investment continued its positive trend (charts 2 and 3), rising for the fifth consecutive month, with an annual change of 5.7% in unadjusted figures, compared with 6.6% previously. By component, machinery and equipment grew 3.5%, driven by a 5.2% increase in imported equipment, while the domestic component grew just 1.0%. Construction expanded 7.6%, with residential construction up 8.9% and non-residential construction up 6.4%. Meanwhile, private investment grew 4.8% and public investment 11.1%. Year-to-date through June, gross fixed investment stands at 2.2%, construction at 4.6%, and machinery and equipment at -0.5%.
PRIVATE CONSUMPTION—IMPORTS LEAD, DOMESTIC DEMAND LAGS
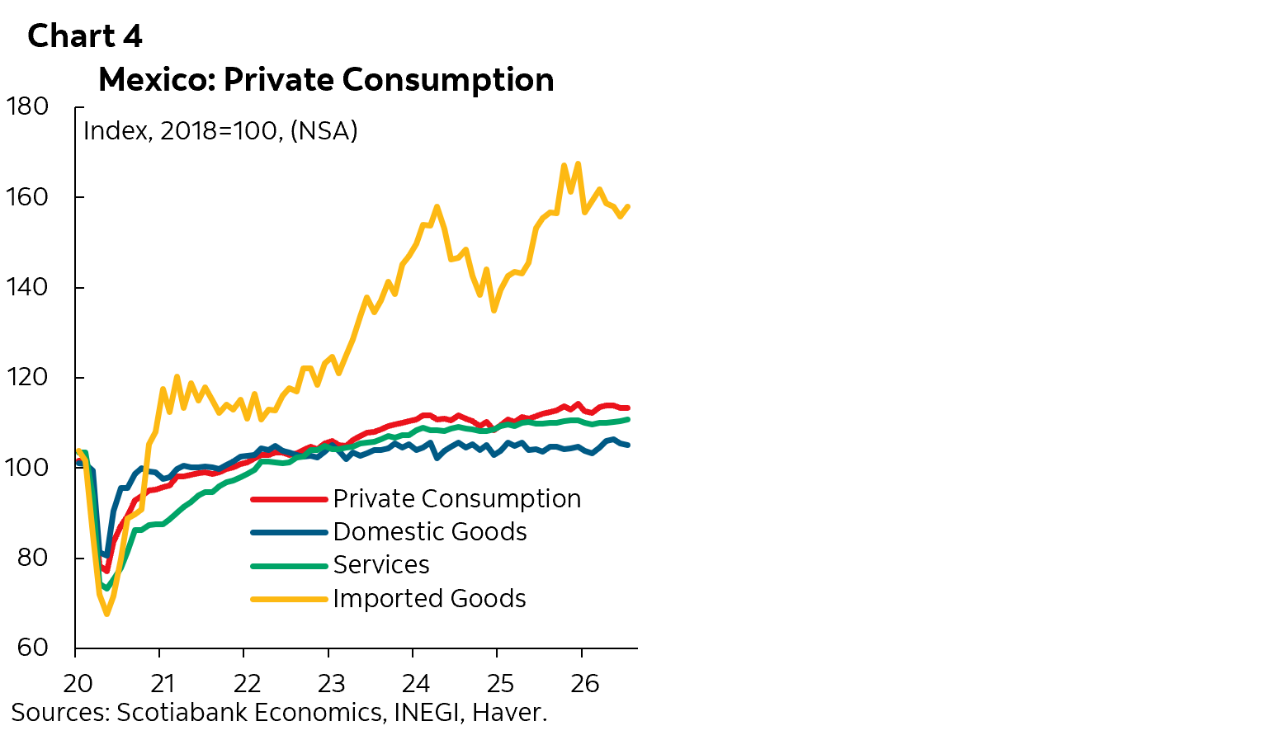
During the same month, private consumption registered an annual increase of 1.3% in unadjusted figures (chart 4), up from 1.1% previously. Imported goods rose 1.5%, up from 0.1% previously, supported by durable goods, which grew 15.8%, and offset by semi-durable goods, which fell -7.5%. Meanwhile, consumption of domestic origin stood at 1.0%, unchanged from the previous month; within it, durable goods grew 2.5%, semi-durable goods grew 3.7%, and non-durable goods grew just 0.2%. Domestic services, for their part, grew 1.1%. Year-to-date through August, private consumption increased 1.9% annually, still driven by the strength of imported goods at 7.2%, in contrast to the domestic component, which stands at 0.4%.
CONSUMER CONFIDENCE: HOUSEHOLD OPTIMISM VERSUS COUNTRY OUTLOOK
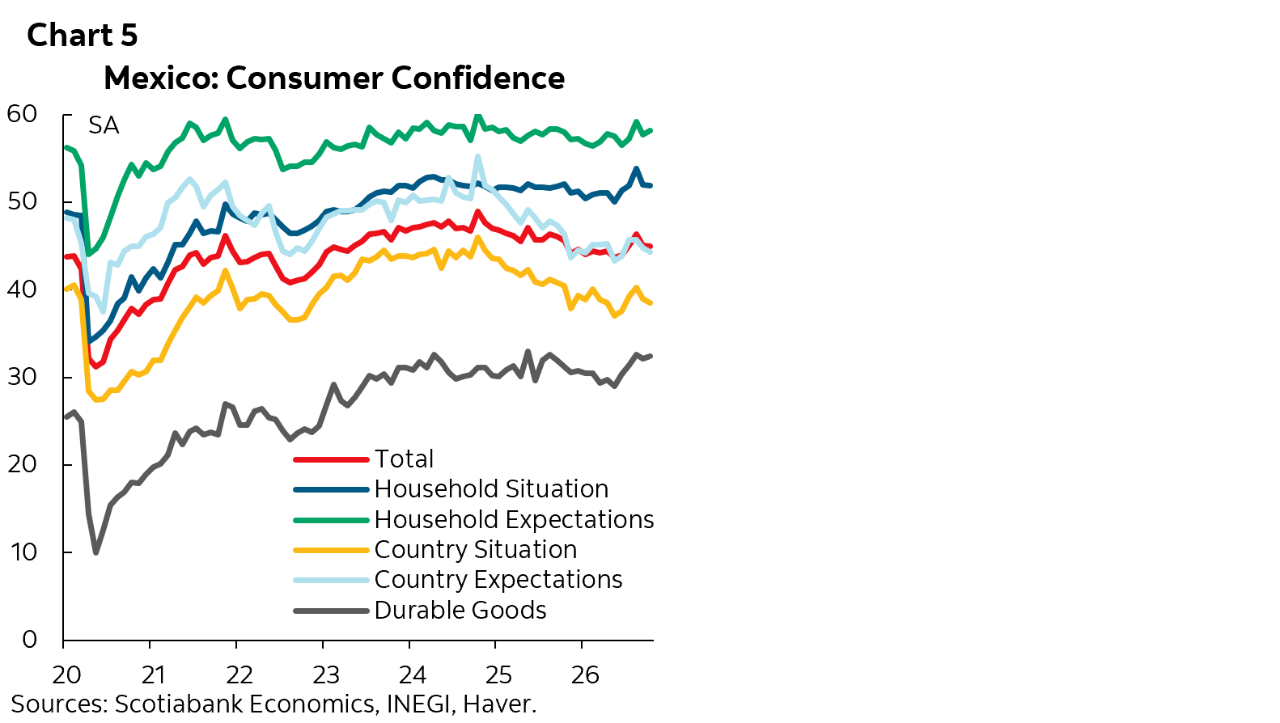
In October, consumer confidence rose to 46.1 points on a seasonally adjusted basis, from 45.1 points (chart 5). On an annual basis, the indicator fell -0.6 points, with declines in almost all of its components. Household perceptions remain above the 50-point threshold: the current household situation stands at 51.8 points, down -0.3 points year over year, while households' twelve-month expectations stand at 58.2 points, up just 0.2 points year over year. In contrast, the current situation of the country component stood at 38.5 points (-2.0 points year over year), while the twelve-month expectation for the country's situation stood at 44.7 points (-2.1 points year over year). Finally, the low perceived likelihood of purchasing durable goods stands out, at 32.4 points, although with an increase of 1.2 points year over year.
—Rodolfo Mitchell, Miguel Saldaña & Martha Cordova
DISCLAIMER
This report has been prepared by Scotiabank Economics as a resource for the clients of Scotiabank. Opinions, estimates and projections contained herein are our own as of the date hereof and are subject to change without notice. The information and opinions contained herein have been compiled or arrived at from sources believed reliable but no representation or warranty, express or implied, is made as to their accuracy or completeness. Neither Scotiabank nor any of its officers, directors, partners, employees or affiliates accepts any liability whatsoever for any direct or consequential loss arising from any use of this report or its contents.
These reports are provided to you for informational purposes only. This report is not, and is not constructed as, an offer to sell or solicitation of any offer to buy any financial instrument, nor shall this report be construed as an opinion as to whether you should enter into any swap or trading strategy involving a swap or any other transaction. The information contained in this report is not intended to be, and does not constitute, a recommendation of a swap or trading strategy involving a swap within the meaning of U.S. Commodity Futures Trading Commission Regulation 23.434 and Appendix A thereto. This material is not intended to be individually tailored to your needs or characteristics and should not be viewed as a “call to action” or suggestion that you enter into a swap or trading strategy involving a swap or any other transaction. Scotiabank may engage in transactions in a manner inconsistent with the views discussed this report and may have positions, or be in the process of acquiring or disposing of positions, referred to in this report.
Scotiabank, its affiliates and any of their respective officers, directors and employees may from time to time take positions in currencies, act as managers, co-managers or underwriters of a public offering or act as principals or agents, deal in, own or act as market makers or advisors, brokers or commercial and/or investment bankers in relation to securities or related derivatives. As a result of these actions, Scotiabank may receive remuneration. All Scotiabank products and services are subject to the terms of applicable agreements and local regulations. Officers, directors and employees of Scotiabank and its affiliates may serve as directors of corporations.
Any securities discussed in this report may not be suitable for all investors. Scotiabank recommends that investors independently evaluate any issuer and security discussed in this report, and consult with any advisors they deem necessary prior to making any investment.
This report and all information, opinions and conclusions contained in it are protected by copyright. This information may not be reproduced without the prior express written consent of Scotiabank.
™ Trademark of The Bank of Nova Scotia. Used under license, where applicable.
Scotiabank, together with “Global Banking and Markets”, is a marketing name for the global corporate and investment banking and capital markets businesses of The Bank of Nova Scotia and certain of its affiliates in the countries where they operate, including; Scotiabank Europe plc; Scotiabank (Ireland) Designated Activity Company; Scotiabank Inverlat S.A., Institución de Banca Múltiple, Grupo Financiero Scotiabank Inverlat, Scotia Inverlat Casa de Bolsa, S.A. de C.V., Grupo Financiero Scotiabank Inverlat, Scotia Inverlat Derivados S.A. de C.V. – all members of the Scotiabank group and authorized users of the Scotiabank mark. The Bank of Nova Scotia is incorporated in Canada with limited liability and is authorised and regulated by the Office of the Superintendent of Financial Institutions Canada. The Bank of Nova Scotia is authorized by the UK Prudential Regulation Authority and is subject to regulation by the UK Financial Conduct Authority and limited regulation by the UK Prudential Regulation Authority. Details about the extent of The Bank of Nova Scotia's regulation by the UK Prudential Regulation Authority are available from us on request. Scotiabank Europe plc is authorized by the UK Prudential Regulation Authority and regulated by the UK Financial Conduct Authority and the UK Prudential Regulation Authority.
Scotiabank Inverlat, S.A., Scotia Inverlat Casa de Bolsa, S.A. de C.V, Grupo Financiero Scotiabank Inverlat, and Scotia Inverlat Derivados, S.A. de C.V., are each authorized and regulated by the Mexican financial authorities.
Not all products and services are offered in all jurisdictions. Services described are available in jurisdictions where permitted by law.