

- Chile: September GDP up 0.2% y/y reveals solid growth across commerce, industry and services
- Peru: Inflation surprises to the upside in October and hits a three-year high
CHILE: SEPTEMBER GDP UP 0.2% Y/Y REVEALS SOLID GROWTH ACROSS COMMERCE, INDUSTRY AND SERVICES
- Non-mining activity reaches a historical high
September GDP rose 0.2% y/y, slightly above market expectations, reflecting a broad-based recovery across sectors, with the exception of Other Goods (charts 1 and 2). Non-mining GDP increased 0.9% m/m SA, reaching the highest level in the seasonally adjusted series, driven by the services sector which also posted a record high during the month on the back of strong business and transportation services. Mining activity remained in annual contraction (-12.1% y/y), although it showed a partial recovery at the margin relative to the previous month (9.8% m/m SA), supported by favourable weather conditions in September that allowed a normalization of extraction levels.
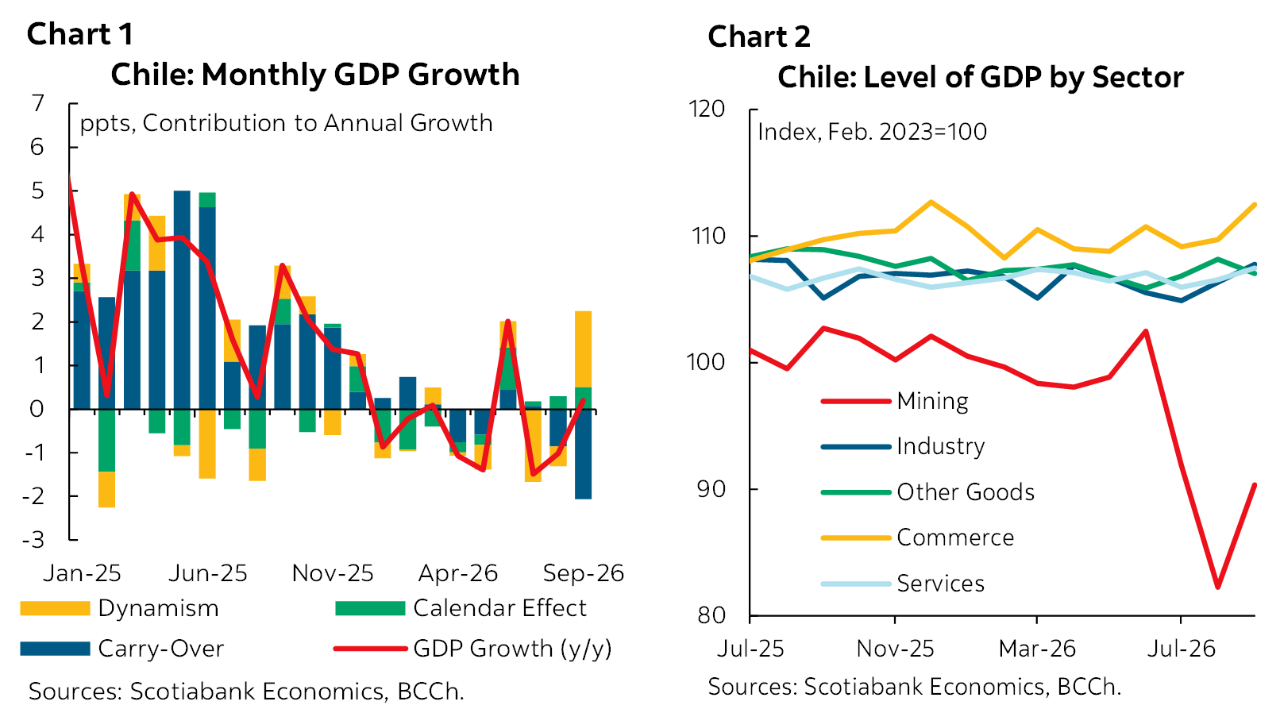
Public investment gained momentum in September, although it remains insufficient to materially boost growth. Capital expenditure execution reached 56.6% of the annual budget, accelerating 18.5% in real terms relative to the previous month, although still accumulating a decline of 11.7% during the first nine months of the year. By ministry, Housing stood out, posting annual growth of 5.7%, largely explained by higher capital transfers associated with housing subsidy payments. While public investment remains lagging and is still likely to end 2026 with significant underexecution, early signs of recovery are emerging and could provide some support to growth in the final part of the year.
From a monetary policy perspective, the latest activity figures suggest that the economy performs better when weather-related disruptions are absent, lending additional support to the view that growth conditions are improving as climate shocks dissipate, particularly those associated with the El Niño phenomenon.
October GDP, with one fewer working day, is expected to post a negative annual reading, which we estimate between -1.0% and -2.0% y/y. Weather conditions and labour disruptions linked to collective bargaining negotiations weighed on mining activity during the month, while severe rainfall affected personal services related to education in several municipalities through school closures. Along the same lines, electricity generation likely ceased to provide a positive contribution to GDP momentum, while commerce appears to have weakened amid lower-than-expected sales during the Cyber Monday event held in early-October. Although we expect partial offsetting contributions from other sectors, these are unlikely to be sufficient to deliver positive year-on-year growth, given demanding comparison bases. At Scotiabank, we maintain our forecast of a 0.3% contraction in total GDP in 2026, alongside a 0.7% y/y expansion in non-mining GDP.
—Aníbal Alarcón
PERU: INFLATION SURPRISES TO THE UPSIDE IN OCTOBER AND HITS A THREE-YEAR HIGH
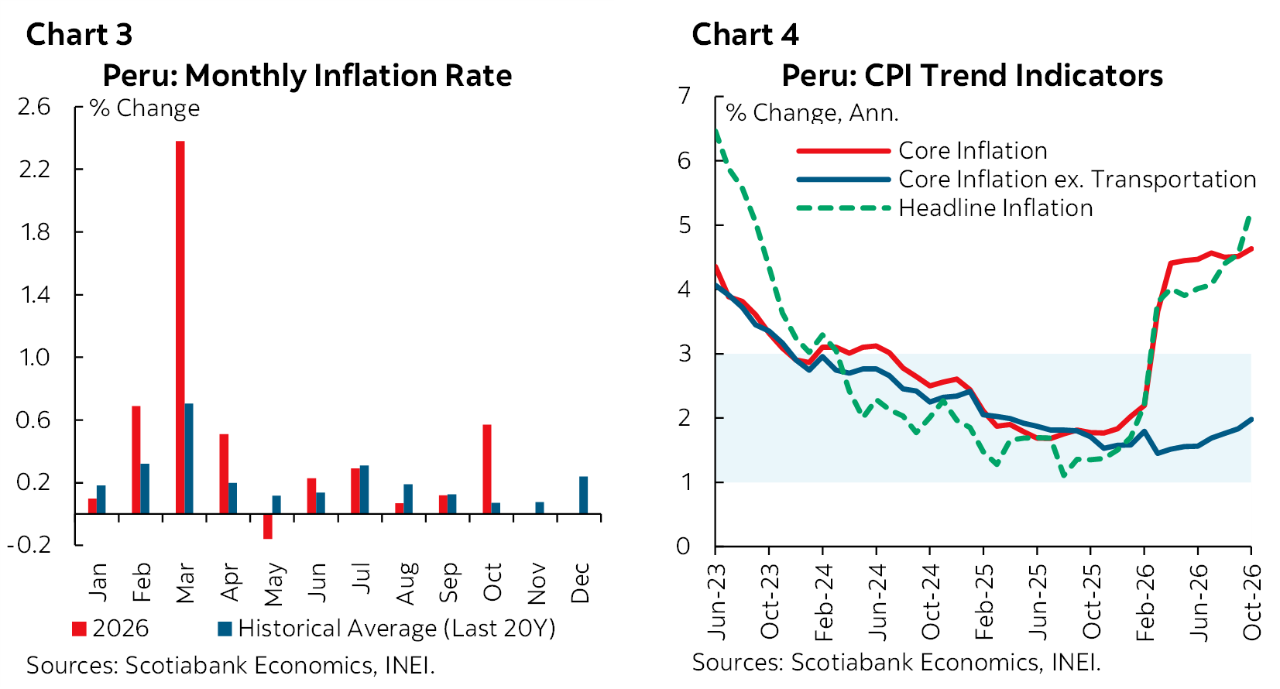
October's inflation report was released yesterday. We expected annual headline inflation to rise from 4.5% to 4.9%; however, the figure surprised to the upside, reaching 5.25%. On a monthly basis, prices increased by 0.6% in October, above the historical average of around 0.1% over the past 20 years, excluding the pandemic period.
This marked the first month in the past six in which inflation deviated significantly from its historical average, reflecting some persistence in supply-side shocks. Among the products recording the largest price increases were fish, peas, and potatoes, amid less favorable weather conditions. Higher fuel prices, associated with the rebound in international oil prices, also contributed to the increase. In contrast, products with significant weight in the consumer basket, such as chicken and eggs, continued to record price declines. By category, the increase was mainly driven by food and non-alcoholic beverages (+1.6%), transport (+0.8%), and restaurants and hotels (+0.2%). Meanwhile, the decline in communication (-1.4%) partially offset the overall increase.
Despite the significant rise in headline inflation, core inflation excluding transportation increased only moderately, from 1.8% in September to 2.0% in October. Part of this increase reflects a base effect, as monthly inflation stood at -0.1% in October 2025. As a result, inflation excluding the most volatile components remains contained, at the midpoint of the Central Reserve Bank of Peru’s (BCRP) target range, suggesting that, for now, the recent supply-side shocks have not spread more broadly across the consumer basket.
Looking ahead to the BCRP's next meeting on November 12th, both a rate hike and another pause remain possible. A key input will be the 12-month inflation expectations report, scheduled for release on November 5th. We do not expect a significant increase, and the figure could remain close to the 3.1% reported in October, given that inflation expectations for December 2027 remain considerably lower, at 2.75%, even if October's inflation reading puts some upward pressure on that forecast
Against this backdrop, and considering that core inflation excluding transportation remains contained, we continue to lean toward the BCRP keeping its policy rate unchanged in November. However, the balance has shifted following October’s upside inflation surprise, making the evolution of inflation expectations particularly relevant for the upcoming decision.
—Ricardo Avila
DISCLAIMER
This report has been prepared by Scotiabank Economics as a resource for the clients of Scotiabank. Opinions, estimates and projections contained herein are our own as of the date hereof and are subject to change without notice. The information and opinions contained herein have been compiled or arrived at from sources believed reliable but no representation or warranty, express or implied, is made as to their accuracy or completeness. Neither Scotiabank nor any of its officers, directors, partners, employees or affiliates accepts any liability whatsoever for any direct or consequential loss arising from any use of this report or its contents.
These reports are provided to you for informational purposes only. This report is not, and is not constructed as, an offer to sell or solicitation of any offer to buy any financial instrument, nor shall this report be construed as an opinion as to whether you should enter into any swap or trading strategy involving a swap or any other transaction. The information contained in this report is not intended to be, and does not constitute, a recommendation of a swap or trading strategy involving a swap within the meaning of U.S. Commodity Futures Trading Commission Regulation 23.434 and Appendix A thereto. This material is not intended to be individually tailored to your needs or characteristics and should not be viewed as a “call to action” or suggestion that you enter into a swap or trading strategy involving a swap or any other transaction. Scotiabank may engage in transactions in a manner inconsistent with the views discussed this report and may have positions, or be in the process of acquiring or disposing of positions, referred to in this report.
Scotiabank, its affiliates and any of their respective officers, directors and employees may from time to time take positions in currencies, act as managers, co-managers or underwriters of a public offering or act as principals or agents, deal in, own or act as market makers or advisors, brokers or commercial and/or investment bankers in relation to securities or related derivatives. As a result of these actions, Scotiabank may receive remuneration. All Scotiabank products and services are subject to the terms of applicable agreements and local regulations. Officers, directors and employees of Scotiabank and its affiliates may serve as directors of corporations.
Any securities discussed in this report may not be suitable for all investors. Scotiabank recommends that investors independently evaluate any issuer and security discussed in this report, and consult with any advisors they deem necessary prior to making any investment.
This report and all information, opinions and conclusions contained in it are protected by copyright. This information may not be reproduced without the prior express written consent of Scotiabank.
™ Trademark of The Bank of Nova Scotia. Used under license, where applicable.
Scotiabank, together with “Global Banking and Markets”, is a marketing name for the global corporate and investment banking and capital markets businesses of The Bank of Nova Scotia and certain of its affiliates in the countries where they operate, including; Scotiabank Europe plc; Scotiabank (Ireland) Designated Activity Company; Scotiabank Inverlat S.A., Institución de Banca Múltiple, Grupo Financiero Scotiabank Inverlat, Scotia Inverlat Casa de Bolsa, S.A. de C.V., Grupo Financiero Scotiabank Inverlat, Scotia Inverlat Derivados S.A. de C.V. – all members of the Scotiabank group and authorized users of the Scotiabank mark. The Bank of Nova Scotia is incorporated in Canada with limited liability and is authorised and regulated by the Office of the Superintendent of Financial Institutions Canada. The Bank of Nova Scotia is authorized by the UK Prudential Regulation Authority and is subject to regulation by the UK Financial Conduct Authority and limited regulation by the UK Prudential Regulation Authority. Details about the extent of The Bank of Nova Scotia's regulation by the UK Prudential Regulation Authority are available from us on request. Scotiabank Europe plc is authorized by the UK Prudential Regulation Authority and regulated by the UK Financial Conduct Authority and the UK Prudential Regulation Authority.
Scotiabank Inverlat, S.A., Scotia Inverlat Casa de Bolsa, S.A. de C.V, Grupo Financiero Scotiabank Inverlat, and Scotia Inverlat Derivados, S.A. de C.V., are each authorized and regulated by the Mexican financial authorities.
Not all products and services are offered in all jurisdictions. Services described are available in jurisdictions where permitted by law.