

KEY TAKEWAYS
- As widely expected, the Governing Board left the policy rate unchanged at 6.50%.
- The statement highlighted ongoing global uncertainty stemming from the conflict in the Middle East, while domestically the economy remains subject to downside risks.
- Regarding inflation, the Board maintained its expectation that inflation will converge to target in the fourth quarter of 2027, despite slight revisions to short-term forecasts.
- The Governing Board noted that Mexico's monetary policy should not react mechanically to adjustments in the Federal Reserve's rate path.
- During the week, the USDMXN weakened, with the peso depreciating to 17.76 per U.S. dollar.
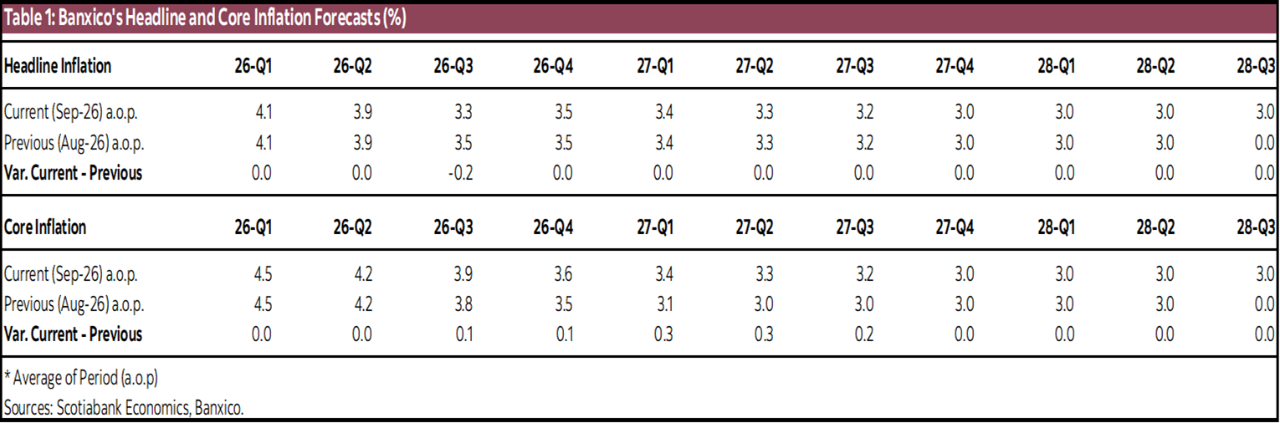
The Governing Board of the Bank of Mexico kept the benchmark interest rate unchanged for the third consecutive meeting at 6.50% in a unanimous decision. The decision was in line with market expectations, which anticipate that the policy rate will remain at current levels throughout the remainder of the year. The Board also marginally revised its headline inflation forecasts lower in Q3-26, while slightly raising its core inflation projections for the same period, maintaining its expectation that inflation will converge to the 3.0% target in the fourth quarter of 2027.
The statement noted that during the third quarter of 2026, global economic activity expanded at a faster pace than in the previous quarter. Headline inflation rebounded in June across several advanced economies, driven by higher energy prices, while core inflation remained persistent. The Board highlighted that the Federal Reserve increased its policy rate by 25 basis points at its September meeting, financial markets continued to exhibit volatility, commodity prices increased, the U.S. dollar appreciated, and long-term U.S. Treasury yields moved higher. Finally, it reiterated the persistence of an uncertain outlook related to the conflict in the Middle East and its potential repercussions.
Domestically, the Governing Board noted that since the previous monetary policy decision, yields on Mexican government securities increased across most maturities. Meanwhile, the peso displayed some volatility. The Board also pointed to a moderation in the pace of economic expansion during the third quarter, while anticipating the persistence of economic slack conditions and downside risks going forward.
Regarding inflation, the first half September inflation print, released on the same day, showed annual headline inflation at 3.42% y/y, above the 3.36% consensus expectation. However, core inflation surprised to the downside, declining from 3.83% to 3.79%. As a result, short-term inflation forecasts were revised downward, while longer-term projections remained stable and above target. Thus, the central bank expects headline inflation to converge to target during the fourth quarter of 2027, subject to upside risks including persistent core inflation, trade policy disruptions, inflationary effects from geopolitical conflicts, climate-related impacts, cost pressures, and a depreciation trend in the peso. On the downside, risks remained unchanged from the previous meeting: weaker-than-expected economic activity, a lower pass-through from production costs, and reduced inflationary pressures stemming from the peso's appreciation since last year.
In our view, the evolution of the monetary policy stance will depend primarily on incoming inflation data, USDMXN developments, and the relative policy stance vis-à-vis the Federal Reserve. In this regard, the statement appears to make a deliberate effort to differentiate Mexico's economic cycle from that of the United States by noting that "monetary policy should not react mechanically to expected adjustments in the federal funds rate." Nevertheless, the peso depreciated during the week to 17.76 per U.S. dollar. Therefore, we believe it will be important to closely monitor potential scenarios of exchange-rate volatility. Accordingly, we maintain our expectation that the policy rate will remain unchanged throughout the rest of 2026 and 2027. Finally, the release of the meeting minutes on October 8th will be key to understanding the details of the Governing Board members' views.
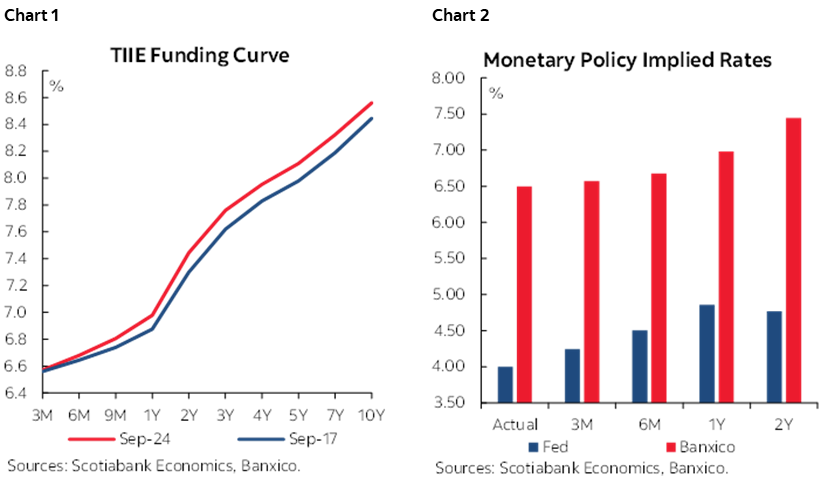
As for the market reaction, the U.S. dollar has strengthened since the Federal Reserve's rate adjustment last week. Consequently, the USDMXN moved from a low of 16.88 per dollar at the beginning of the month to 17.67 at the start of the trading session and further weakened to 17.76 per dollar following the monetary policy announcement. Meanwhile, the Overnight TIIE swap curve also moved higher. The short end of the curve (up to one year) increased between 0.88 and 10.55 basis points, while maturities between one and thirty years rose between 11.50 and 14.50 basis points. The three-month implied curve stood at 6.57%, while the one-year implied rate reached 6.98%, suggesting that markets anticipate a higher policy rate one year ahead.
DISCLAIMER
This report has been prepared by Scotiabank Economics as a resource for the clients of Scotiabank. Opinions, estimates and projections contained herein are our own as of the date hereof and are subject to change without notice. The information and opinions contained herein have been compiled or arrived at from sources believed reliable but no representation or warranty, express or implied, is made as to their accuracy or completeness. Neither Scotiabank nor any of its officers, directors, partners, employees or affiliates accepts any liability whatsoever for any direct or consequential loss arising from any use of this report or its contents.
These reports are provided to you for informational purposes only. This report is not, and is not constructed as, an offer to sell or solicitation of any offer to buy any financial instrument, nor shall this report be construed as an opinion as to whether you should enter into any swap or trading strategy involving a swap or any other transaction. The information contained in this report is not intended to be, and does not constitute, a recommendation of a swap or trading strategy involving a swap within the meaning of U.S. Commodity Futures Trading Commission Regulation 23.434 and Appendix A thereto. This material is not intended to be individually tailored to your needs or characteristics and should not be viewed as a “call to action” or suggestion that you enter into a swap or trading strategy involving a swap or any other transaction. Scotiabank may engage in transactions in a manner inconsistent with the views discussed this report and may have positions, or be in the process of acquiring or disposing of positions, referred to in this report.
Scotiabank, its affiliates and any of their respective officers, directors and employees may from time to time take positions in currencies, act as managers, co-managers or underwriters of a public offering or act as principals or agents, deal in, own or act as market makers or advisors, brokers or commercial and/or investment bankers in relation to securities or related derivatives. As a result of these actions, Scotiabank may receive remuneration. All Scotiabank products and services are subject to the terms of applicable agreements and local regulations. Officers, directors and employees of Scotiabank and its affiliates may serve as directors of corporations.
Any securities discussed in this report may not be suitable for all investors. Scotiabank recommends that investors independently evaluate any issuer and security discussed in this report, and consult with any advisors they deem necessary prior to making any investment.
This report and all information, opinions and conclusions contained in it are protected by copyright. This information may not be reproduced without the prior express written consent of Scotiabank.
™ Trademark of The Bank of Nova Scotia. Used under license, where applicable.
Scotiabank, together with “Global Banking and Markets”, is a marketing name for the global corporate and investment banking and capital markets businesses of The Bank of Nova Scotia and certain of its affiliates in the countries where they operate, including; Scotiabank Europe plc; Scotiabank (Ireland) Designated Activity Company; Scotiabank Inverlat S.A., Institución de Banca Múltiple, Grupo Financiero Scotiabank Inverlat, Scotia Inverlat Casa de Bolsa, S.A. de C.V., Grupo Financiero Scotiabank Inverlat, Scotia Inverlat Derivados S.A. de C.V. – all members of the Scotiabank group and authorized users of the Scotiabank mark. The Bank of Nova Scotia is incorporated in Canada with limited liability and is authorised and regulated by the Office of the Superintendent of Financial Institutions Canada. The Bank of Nova Scotia is authorized by the UK Prudential Regulation Authority and is subject to regulation by the UK Financial Conduct Authority and limited regulation by the UK Prudential Regulation Authority. Details about the extent of The Bank of Nova Scotia's regulation by the UK Prudential Regulation Authority are available from us on request. Scotiabank Europe plc is authorized by the UK Prudential Regulation Authority and regulated by the UK Financial Conduct Authority and the UK Prudential Regulation Authority.
Scotiabank Inverlat, S.A., Scotia Inverlat Casa de Bolsa, S.A. de C.V, Grupo Financiero Scotiabank Inverlat, and Scotia Inverlat Derivados, S.A. de C.V., are each authorized and regulated by the Mexican financial authorities.
Not all products and services are offered in all jurisdictions. Services described are available in jurisdictions where permitted by law.