

KEY TAKEAWAYS
- The Governing Board cut the benchmark rate by 25 bps in a split vote, despite the consensus expecting the rate to be held.
- In the global environment, uncertainty related to the Middle East conflict continues, while in the Mexican economy, slack conditions persist with downside risks.
- In advanced economies, several central banks have made upward adjustments in the second half of the year in response to greater inflationary pressures from higher energy prices.
- The Governing Board revised upward its inflation expectation for the current quarter, with the balance of risks skewed to the upside, although it considered that the disinflation process has continued.
- Going forward, the statement indicated that the Board is considering keeping the rate at its current level for an extended period.
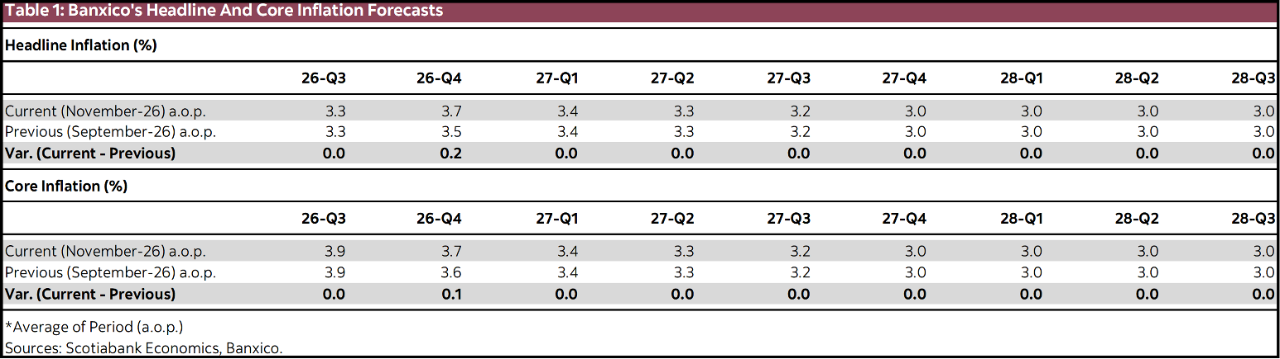
Banco de México's Governing Board decided to cut the benchmark interest rate by 25 bps to 6.25% in a split decision. Although the door had been opened to a cut and some analysts expected it to materialize, the consensus pointed to the benchmark rate being held at 6.50%, with that level being the terminal rate for this year. In addition, the Board revised upward its headline and core inflation projections for 4Q-26, placing both at 3.7%, although the expectation of convergence to 3.0% in 4Q-27 is maintained.
The statement noted that global economic activity maintained a slightly less dynamic pace of expansion during the third quarter of 2026 than in the previous quarter. Inflation increased in several advanced economies due to higher energy prices, with persistence in core inflation. It highlighted that the Federal Reserve held its benchmark rate at 3.75–4.00% at its October meeting, that financial markets continued to show volatility, with limited movements in the dollar and increases in long-term U.S. Treasury yields that took them to record highs. It also reiterated that uncertainty related to the Middle East conflict persists for the global economic environment.
On the domestic front, the Governing Board noted that, since the last monetary policy decision, interest rates on government securities in Mexico declined at medium and long maturities and rose at short maturities. For its part, the peso depreciated. The Board highlighted the expansion of the economy during the third quarter, although slack conditions are expected, as well as the persistence of downside risks going forward.
Regarding inflation, in the first half of October it stood at 3.62% due to a rebound in the non-core component, while core inflation remained virtually unchanged at 3.78%. Despite this, the Governing Board considered that the disinflation process has continued and that no demand pressures are perceived in the economy. It also considered that the pass-through of exchange rate movements to prices would be limited. Nevertheless, and somewhat contradictorily, the Board once again revised upward its forecasts for the fourth quarter of the current year for both headline and core inflation, although it still expects inflation to converge to the 3.0% target in the last quarter of 2027. In addition, the balance of inflation risks remains skewed to the upside, citing the persistence of core inflation, further peso depreciation, disruptions from trade policies, inflationary impacts from geopolitical conflicts, weather-related disruptions, and cost pressures. On the other hand, the downside risks were the same as at the previous meeting: weaker-than-anticipated economic activity, a lower pass-through of cost increases, and lower pressures from peso appreciation.
Although most analysts, ourselves included, anticipated that Banco de México would keep the rate unchanged on this occasion, the cut is not entirely surprising, since the minutes had left open the possibility of an additional move and some Board members had indicated in various forums their inclination to make one last adjustment to the benchmark rate, although the arguments are not so clear. However, the cut was accompanied by a statement with a more restrictive tone, which suggests the start of a new pause and places greater emphasis on the evolution of inflation expectations, where market expectations have declined only marginally and still do not show clear convergence toward the target. The most relevant signal was that the Board explicitly indicated that keeping the rate at the level reached “for an extended period” will contribute to the convergence of inflation, which could be interpreted as these members continuing to see monetary conditions as remaining in restrictive territory, in a context in which the decision was split, 3–2, and the headline and core inflation forecasts for the fourth quarter of 2026 were revised upward, from 3.5% to 3.7% and from 3.6% to 3.7%, respectively. Finally, the publication of the minutes on November 19th will be key to analyzing the details of the discussion and understanding the reasons behind the decision.
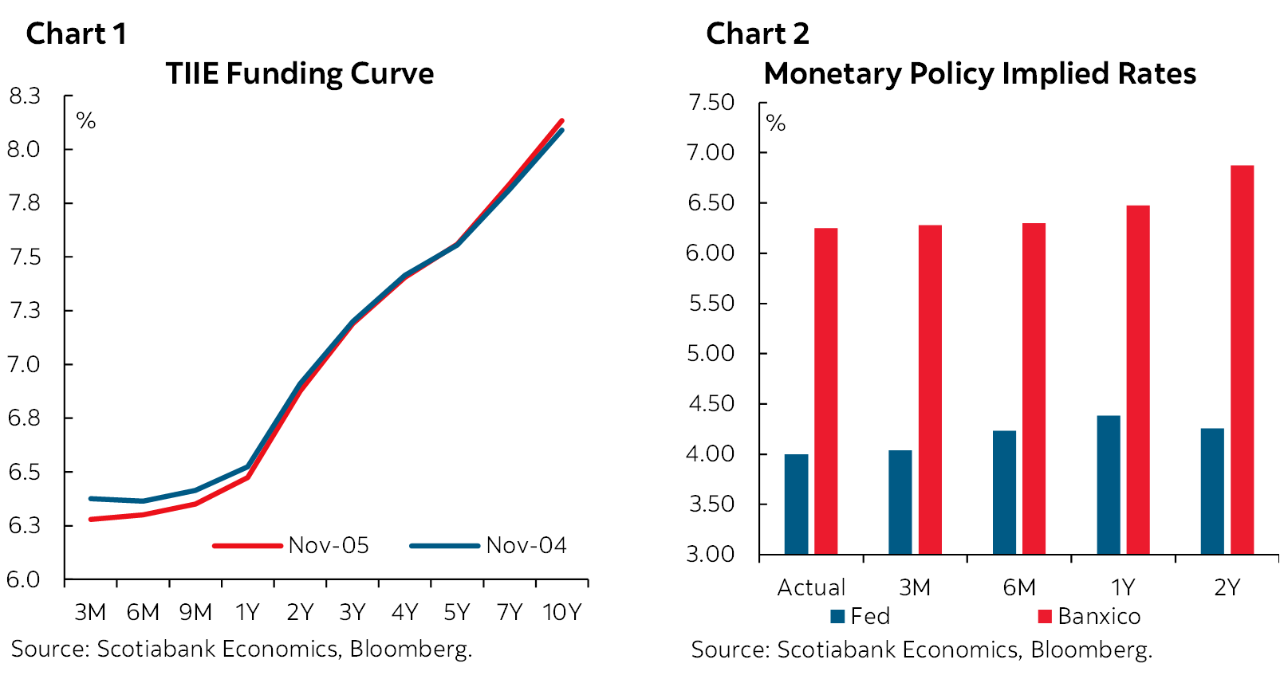
As for the market reaction, the dollar depreciated by about 10 cents at the time the decision was published, reaching $18.84, and then settling at $18.73. For its part, the Funding TIIE curve showed movements. The short end (up to 1 year), as well as the 2-, 3-, and 4-year tenors, declined between 1.00 and 9.50 bps, while the rest of the curve out to 30 years rose between 0.50 and 4.50 bps. The implied three-month rate stood at 6.28%, while the one-year rate stood at 6.48%, implying that the market anticipates a higher rate a year from now.
DISCLAIMER
This report has been prepared by Scotiabank Economics as a resource for the clients of Scotiabank. Opinions, estimates and projections contained herein are our own as of the date hereof and are subject to change without notice. The information and opinions contained herein have been compiled or arrived at from sources believed reliable but no representation or warranty, express or implied, is made as to their accuracy or completeness. Neither Scotiabank nor any of its officers, directors, partners, employees or affiliates accepts any liability whatsoever for any direct or consequential loss arising from any use of this report or its contents.
These reports are provided to you for informational purposes only. This report is not, and is not constructed as, an offer to sell or solicitation of any offer to buy any financial instrument, nor shall this report be construed as an opinion as to whether you should enter into any swap or trading strategy involving a swap or any other transaction. The information contained in this report is not intended to be, and does not constitute, a recommendation of a swap or trading strategy involving a swap within the meaning of U.S. Commodity Futures Trading Commission Regulation 23.434 and Appendix A thereto. This material is not intended to be individually tailored to your needs or characteristics and should not be viewed as a “call to action” or suggestion that you enter into a swap or trading strategy involving a swap or any other transaction. Scotiabank may engage in transactions in a manner inconsistent with the views discussed this report and may have positions, or be in the process of acquiring or disposing of positions, referred to in this report.
Scotiabank, its affiliates and any of their respective officers, directors and employees may from time to time take positions in currencies, act as managers, co-managers or underwriters of a public offering or act as principals or agents, deal in, own or act as market makers or advisors, brokers or commercial and/or investment bankers in relation to securities or related derivatives. As a result of these actions, Scotiabank may receive remuneration. All Scotiabank products and services are subject to the terms of applicable agreements and local regulations. Officers, directors and employees of Scotiabank and its affiliates may serve as directors of corporations.
Any securities discussed in this report may not be suitable for all investors. Scotiabank recommends that investors independently evaluate any issuer and security discussed in this report, and consult with any advisors they deem necessary prior to making any investment.
This report and all information, opinions and conclusions contained in it are protected by copyright. This information may not be reproduced without the prior express written consent of Scotiabank.
™ Trademark of The Bank of Nova Scotia. Used under license, where applicable.
Scotiabank, together with “Global Banking and Markets”, is a marketing name for the global corporate and investment banking and capital markets businesses of The Bank of Nova Scotia and certain of its affiliates in the countries where they operate, including; Scotiabank Europe plc; Scotiabank (Ireland) Designated Activity Company; Scotiabank Inverlat S.A., Institución de Banca Múltiple, Grupo Financiero Scotiabank Inverlat, Scotia Inverlat Casa de Bolsa, S.A. de C.V., Grupo Financiero Scotiabank Inverlat, Scotia Inverlat Derivados S.A. de C.V. – all members of the Scotiabank group and authorized users of the Scotiabank mark. The Bank of Nova Scotia is incorporated in Canada with limited liability and is authorised and regulated by the Office of the Superintendent of Financial Institutions Canada. The Bank of Nova Scotia is authorized by the UK Prudential Regulation Authority and is subject to regulation by the UK Financial Conduct Authority and limited regulation by the UK Prudential Regulation Authority. Details about the extent of The Bank of Nova Scotia's regulation by the UK Prudential Regulation Authority are available from us on request. Scotiabank Europe plc is authorized by the UK Prudential Regulation Authority and regulated by the UK Financial Conduct Authority and the UK Prudential Regulation Authority.
Scotiabank Inverlat, S.A., Scotia Inverlat Casa de Bolsa, S.A. de C.V, Grupo Financiero Scotiabank Inverlat, and Scotia Inverlat Derivados, S.A. de C.V., are each authorized and regulated by the Mexican financial authorities.
Not all products and services are offered in all jurisdictions. Services described are available in jurisdictions where permitted by law.