

CANADA HOUSING MARKET: UNCERTAINTY ABOUT ECONOMIC AND INFLATION OUTLOOK IS WEIGHING ON MARKET CONDITIONS
SUMMARY
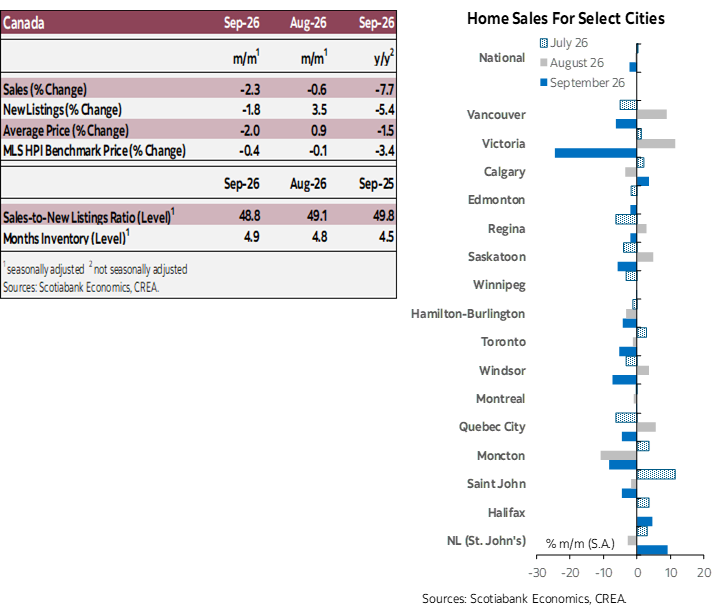
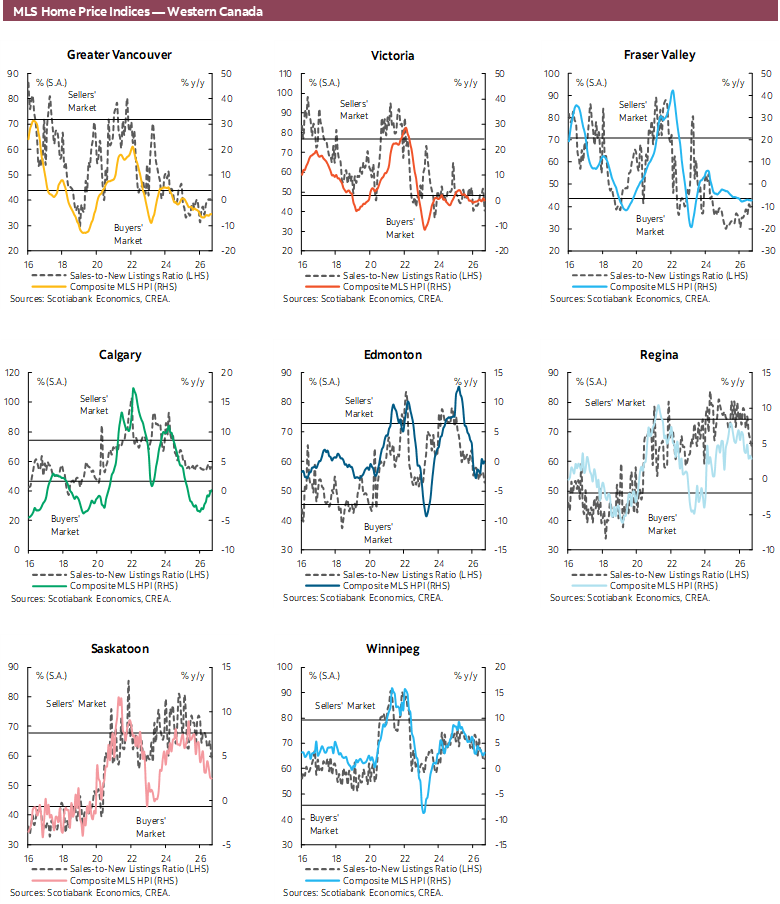
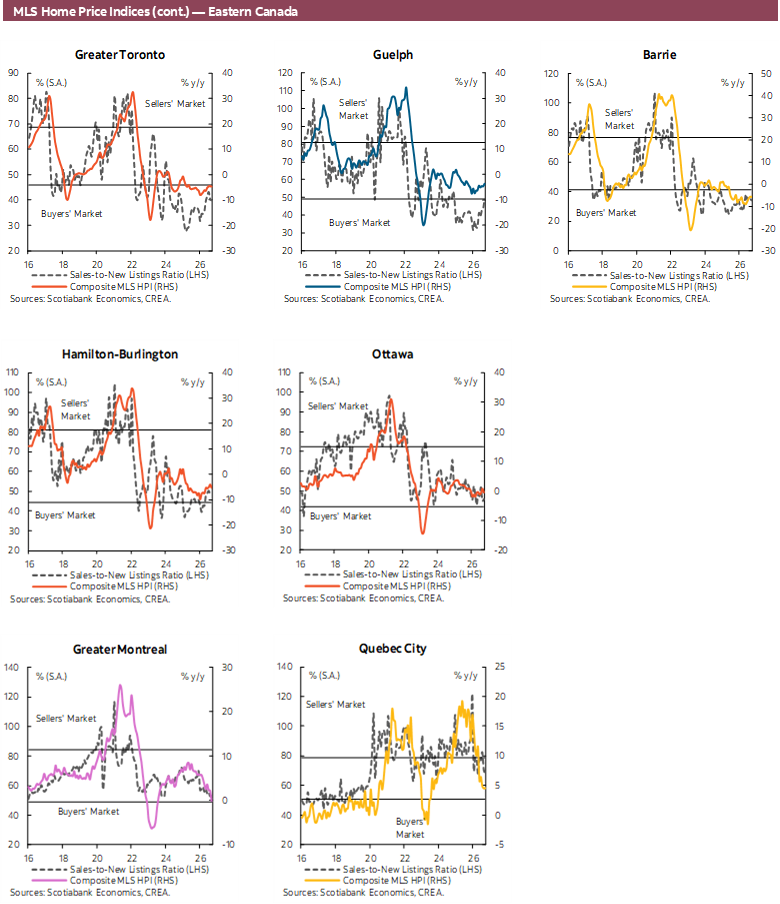
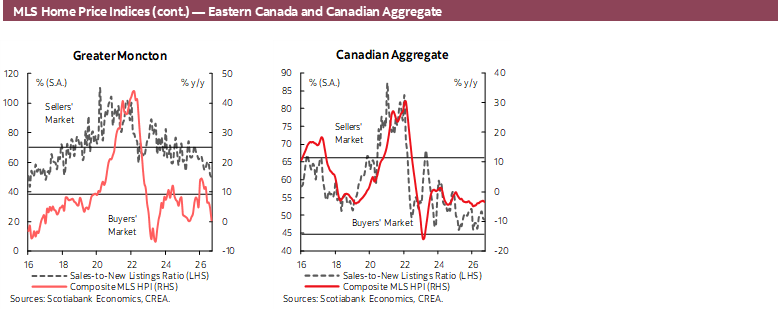
Both national unit sales and new listings declined from August to September. On net, national resale conditions eased modestly according to the sales-to-new listings ratio and months of inventory. The MLS HPI posted in September its strongest monthly decline since last February and is still on its downward trend that started in March 2022.
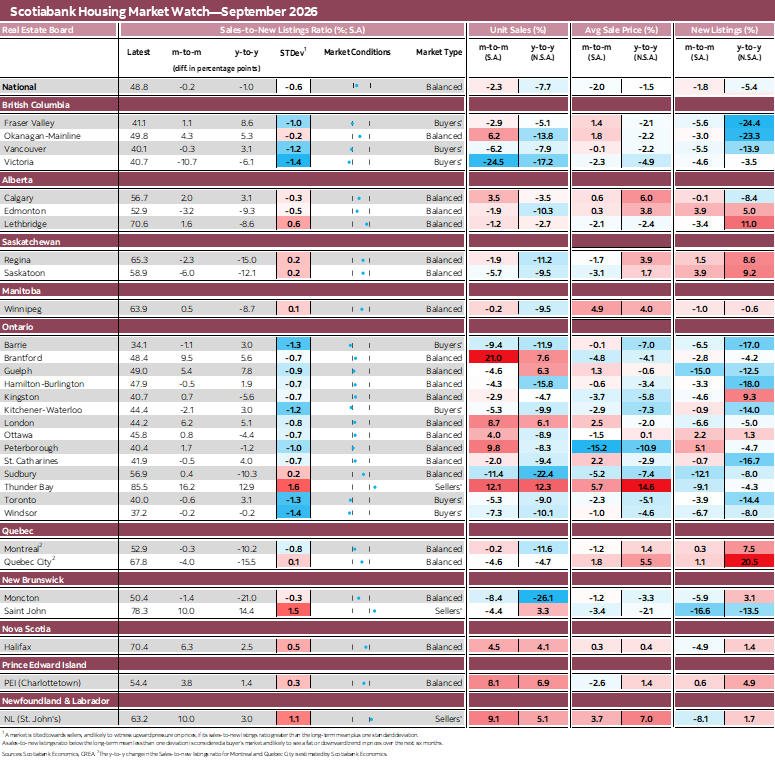
In September, the volume of national sales reported by the Canadian Real Estate Association fell by 2.3% (m/m, sa), a second monthly consecutive decline, which together have erased nearly half of the gains witnessed over the April–July period. About 2/3 of the local markets we track posted a decline in sales from August to September with the most pronounced ones in Victoria (-24.5%), Sudbury (-11.4%) and Barrie (-9.4%). Over the 12-month period ending with September, housing sales fell by 7.7% (nsa) with nearly ¾ of the tracked local markets posting a decline. The largest annual declines in sales were observed for Moncton (-26.1%), Sudbury (-22.4%) and Victoria (-17.2%).
New listings declined nationally by 1.8%% (sa) from August to September, continuing their modest downward trend that started in September 2025. Since then, national new listings declined by 5.4% (nsa), with just above 60% of the tracked local markets also showing an annual decline.
Since sales declined at a slightly faster pace than new listings in September, the national sales-to-new listings ratio modestly eased from 49.1% (sa) in August to 48.8% in September, still trending in the lower half of the balanced national conditions range as it has been doing since the end of 2024. This indicator has modestly eased since September 2025 (by 0.6 percentage point; sa figures), but with less than half of the tracked local markets also showing a decline. The other indicator of market conditions we follow, months of inventory, also eased modestly from August to September, increasing from 4.8 to 4.9 months, moving a bit closer to its long-term pre-pandemic average of 5.2 months.
The national (all markets) MLS House Price Index (HPI) continued last month the downward trend it started in March 2022, declining 0.4% (sa) from August to September, its strongest monthly decline since February of this year. All unit-types posted a decline over this period with the strongest observed for single 2-storey units (-0.5%) and weakest for townhouses (-0.2%). In September, this price indicator lost 3.4% (nsa) from the same month in 2025, with all unit-types also showing an annual decline.
IMPLICATIONS
The national housing market weakness continued in September as reflected by softer sales and the continuation of the sustained downward trend in the MLS HPI that started in early 2022. Despite mortgage rates having declined from their recent Summer/Fall 2023 peak, the weak demand cycle continued in September impacted by the rise in global trade and, more recently, geopolitical tensions. These tensions have increased inflation fears and pressures on interest rates and contribute to keep elevated the degree of uncertainty about future (real) income conditions and mortgage financing costs. And as mentioned in previous reports, the above-average pace of newly built units also contributes to soften economic conditions and put downward pressure on prices. Therefore, this wait-and-see approach by potential buyers is expected to weigh on housing demand until trade and geopolitical tensions—along with their resulting impact on expected inflation and purchasing power conditions—start cooling down.
DISCLAIMER
This report has been prepared by Scotiabank Economics as a resource for the clients of Scotiabank. Opinions, estimates and projections contained herein are our own as of the date hereof and are subject to change without notice. The information and opinions contained herein have been compiled or arrived at from sources believed reliable but no representation or warranty, express or implied, is made as to their accuracy or completeness. Neither Scotiabank nor any of its officers, directors, partners, employees or affiliates accepts any liability whatsoever for any direct or consequential loss arising from any use of this report or its contents.
These reports are provided to you for informational purposes only. This report is not, and is not constructed as, an offer to sell or solicitation of any offer to buy any financial instrument, nor shall this report be construed as an opinion as to whether you should enter into any swap or trading strategy involving a swap or any other transaction. The information contained in this report is not intended to be, and does not constitute, a recommendation of a swap or trading strategy involving a swap within the meaning of U.S. Commodity Futures Trading Commission Regulation 23.434 and Appendix A thereto. This material is not intended to be individually tailored to your needs or characteristics and should not be viewed as a “call to action” or suggestion that you enter into a swap or trading strategy involving a swap or any other transaction. Scotiabank may engage in transactions in a manner inconsistent with the views discussed this report and may have positions, or be in the process of acquiring or disposing of positions, referred to in this report.
Scotiabank, its affiliates and any of their respective officers, directors and employees may from time to time take positions in currencies, act as managers, co-managers or underwriters of a public offering or act as principals or agents, deal in, own or act as market makers or advisors, brokers or commercial and/or investment bankers in relation to securities or related derivatives. As a result of these actions, Scotiabank may receive remuneration. All Scotiabank products and services are subject to the terms of applicable agreements and local regulations. Officers, directors and employees of Scotiabank and its affiliates may serve as directors of corporations.
Any securities discussed in this report may not be suitable for all investors. Scotiabank recommends that investors independently evaluate any issuer and security discussed in this report, and consult with any advisors they deem necessary prior to making any investment.
This report and all information, opinions and conclusions contained in it are protected by copyright. This information may not be reproduced without the prior express written consent of Scotiabank.
™ Trademark of The Bank of Nova Scotia. Used under license, where applicable.
Scotiabank, together with “Global Banking and Markets”, is a marketing name for the global corporate and investment banking and capital markets businesses of The Bank of Nova Scotia and certain of its affiliates in the countries where they operate, including; Scotiabank Europe plc; Scotiabank (Ireland) Designated Activity Company; Scotiabank Inverlat S.A., Institución de Banca Múltiple, Grupo Financiero Scotiabank Inverlat, Scotia Inverlat Casa de Bolsa, S.A. de C.V., Grupo Financiero Scotiabank Inverlat, Scotia Inverlat Derivados S.A. de C.V. – all members of the Scotiabank group and authorized users of the Scotiabank mark. The Bank of Nova Scotia is incorporated in Canada with limited liability and is authorised and regulated by the Office of the Superintendent of Financial Institutions Canada. The Bank of Nova Scotia is authorized by the UK Prudential Regulation Authority and is subject to regulation by the UK Financial Conduct Authority and limited regulation by the UK Prudential Regulation Authority. Details about the extent of The Bank of Nova Scotia's regulation by the UK Prudential Regulation Authority are available from us on request. Scotiabank Europe plc is authorized by the UK Prudential Regulation Authority and regulated by the UK Financial Conduct Authority and the UK Prudential Regulation Authority.
Scotiabank Inverlat, S.A., Scotia Inverlat Casa de Bolsa, S.A. de C.V, Grupo Financiero Scotiabank Inverlat, and Scotia Inverlat Derivados, S.A. de C.V., are each authorized and regulated by the Mexican financial authorities.
Not all products and services are offered in all jurisdictions. Services described are available in jurisdictions where permitted by law.