

- CPI slightly undershot expectations…
- …but high frequency core inflation gauges remain warm…
- …and the BoC is focused upon forward-looking inflation risk
- Canadian CPI m/m NSA / y/y %, October:
- Actual: 0.2 / 3.1
- Scotia: 0.4 / 3.3
- Consensus: 0.3 / 3.2
- Prior: 0.1 / 3.1
- Trimmed mean CPI: 2.2
- Weighted median CPI: 2.7
- Traditional core CPI: 1.5
Probably good enough to hike in December, perhaps pending further information. That about sums up the latest inflation readings out of Canada. Markets barely reacted as the C$ slipped by about a tenth of a penny and Canada’s two-year yield edged about 2bps lower. Markets remain on the fence toward the December 9th move with pricing moving about 2bps lower to roughly half of a quarter-point hike priced.
Why is it good enough? For one, the BoC is forward-looking and expects a protracted overshoot of its 2% target throughout much of its forecast horizon. That signals it believes it is behind in fighting inflationary pressures and inflation risk. That signals belief that it is not focused upon backward data to begin with and certainly not just one month.
Second, the smoothed core measures continue to point toward rising pressures on underlying inflation. Charts 1 and 2 show the month-over-month trimmed mean and weighted median gauges on a seasonally adjusted and annualized basis after applying a three-month moving average to smooth the volatility. Weighted median CPI stands at 2.9% m/m SAAR, and trimmed mean CPI is at 2.6% and traditional core CPI is at 2% on this basis. Average all three and they’re at 2.5% m/m SAAR on a 3moMA basis.
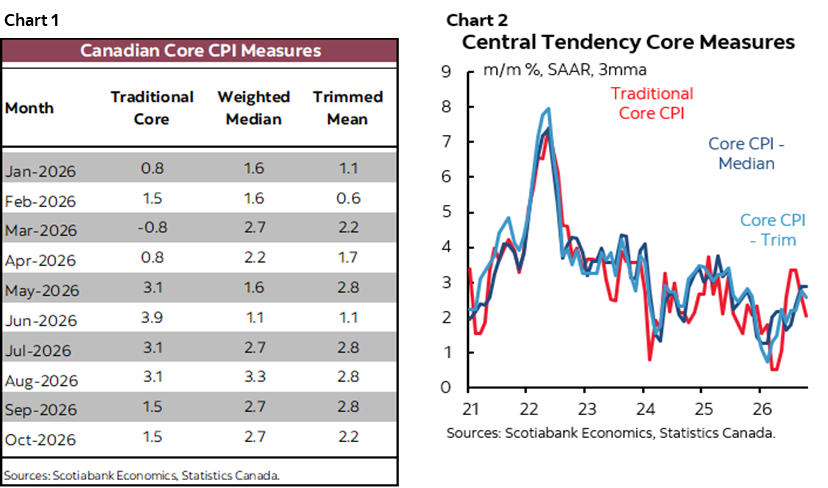
The combination of these two points continues to merit moving further away from the bottom end of the neutral rate range in a continued rebalancing of the policy risks. If you’re on or above the 2% inflation target using headline CPI and higher frequency core gauges, then you shouldn’t still be at 2.5% with a real policy rate that is close to zero or negative depending upon what measure of inflation or inflation expectations is used.
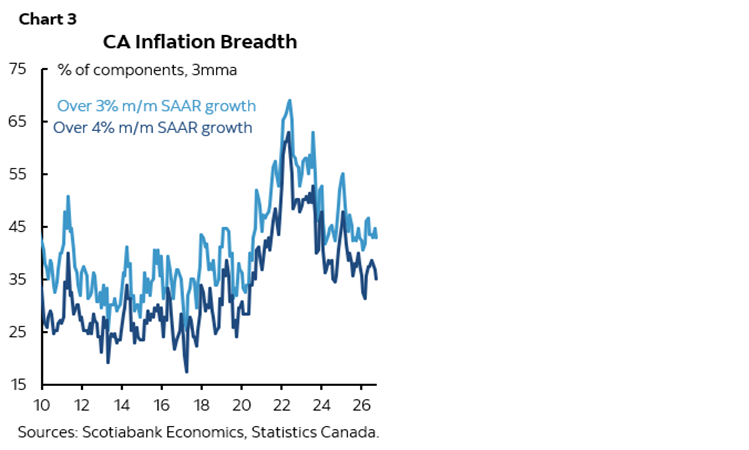
The breadth of price pressures was little changed overall (chart 3).
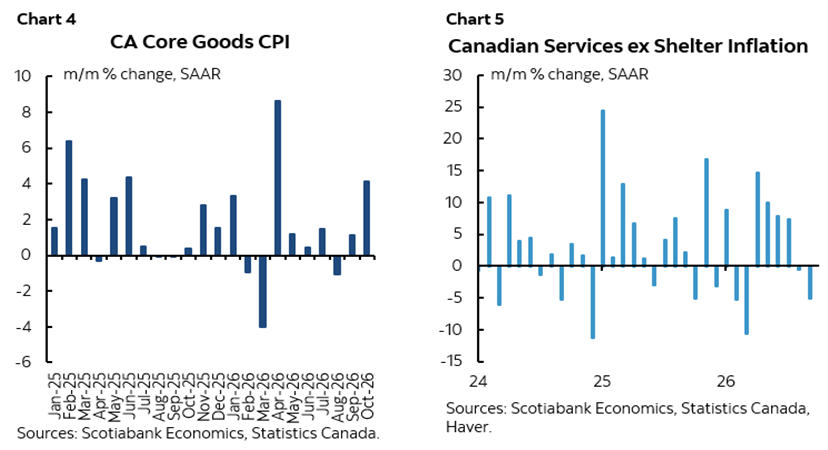
While core goods inflation accelerated to the highest rate since April (chart 4), this was offset by the weakest core services inflation (ex-shelter) since April, shown in chart 5.
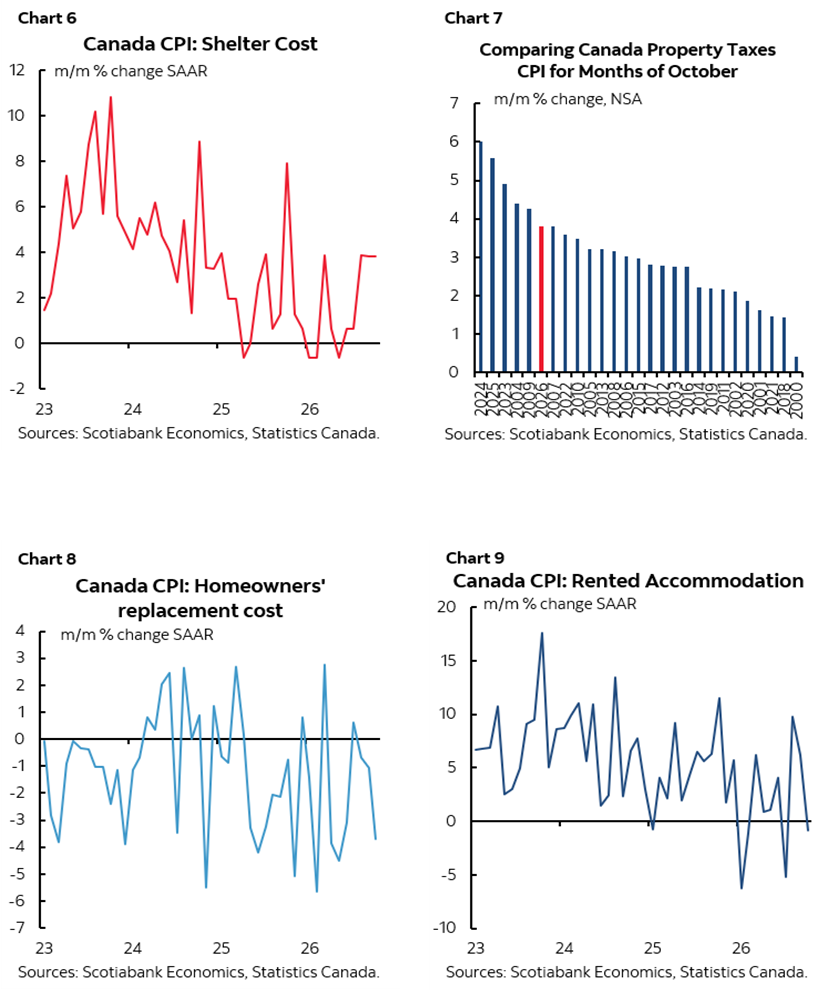
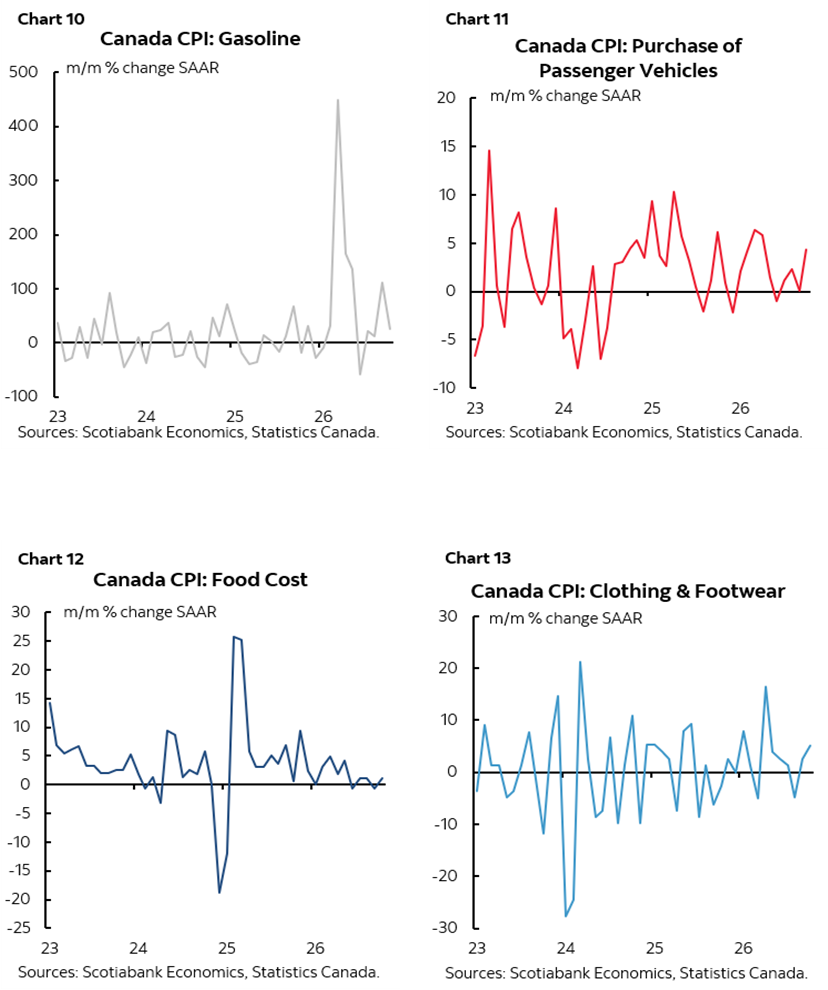
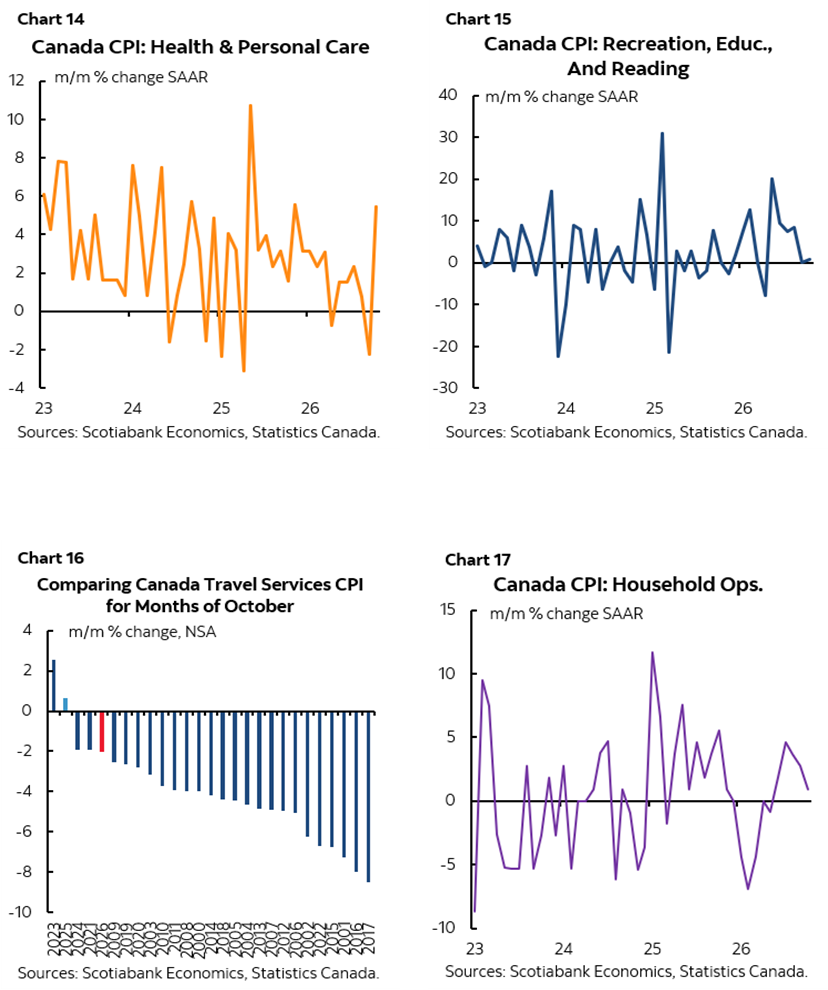
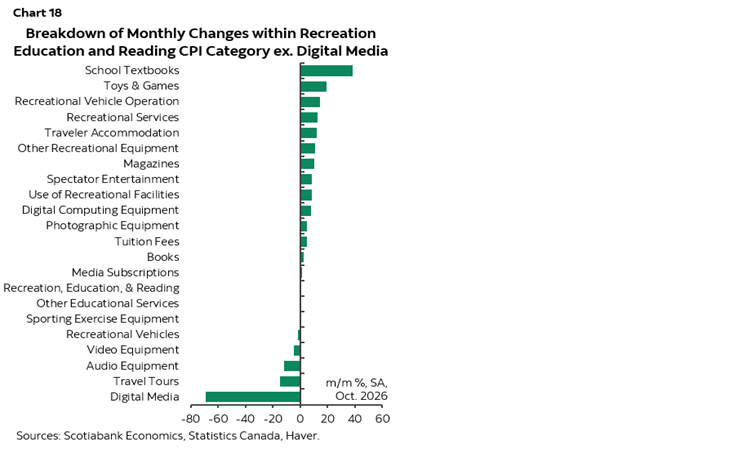
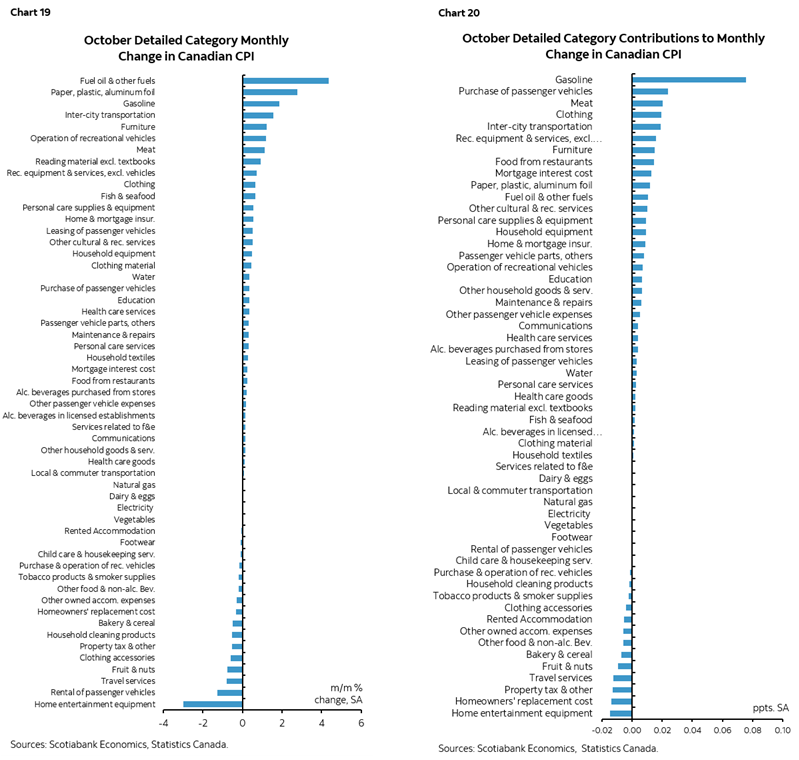
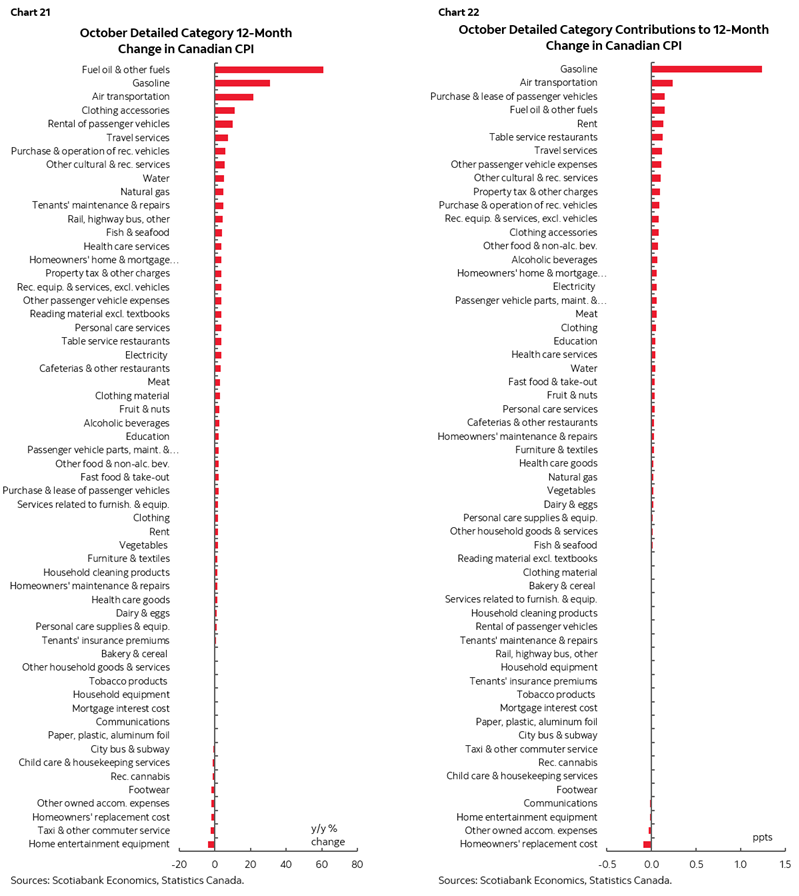
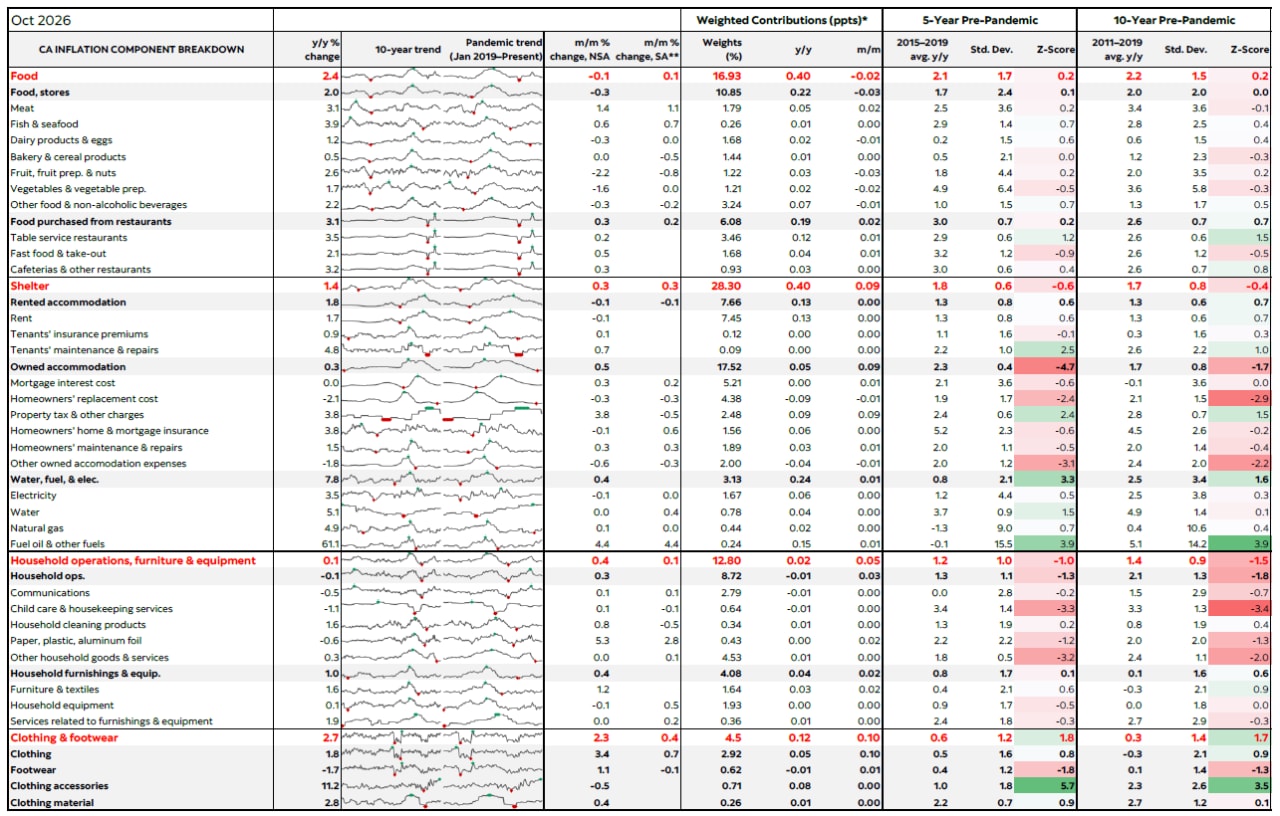
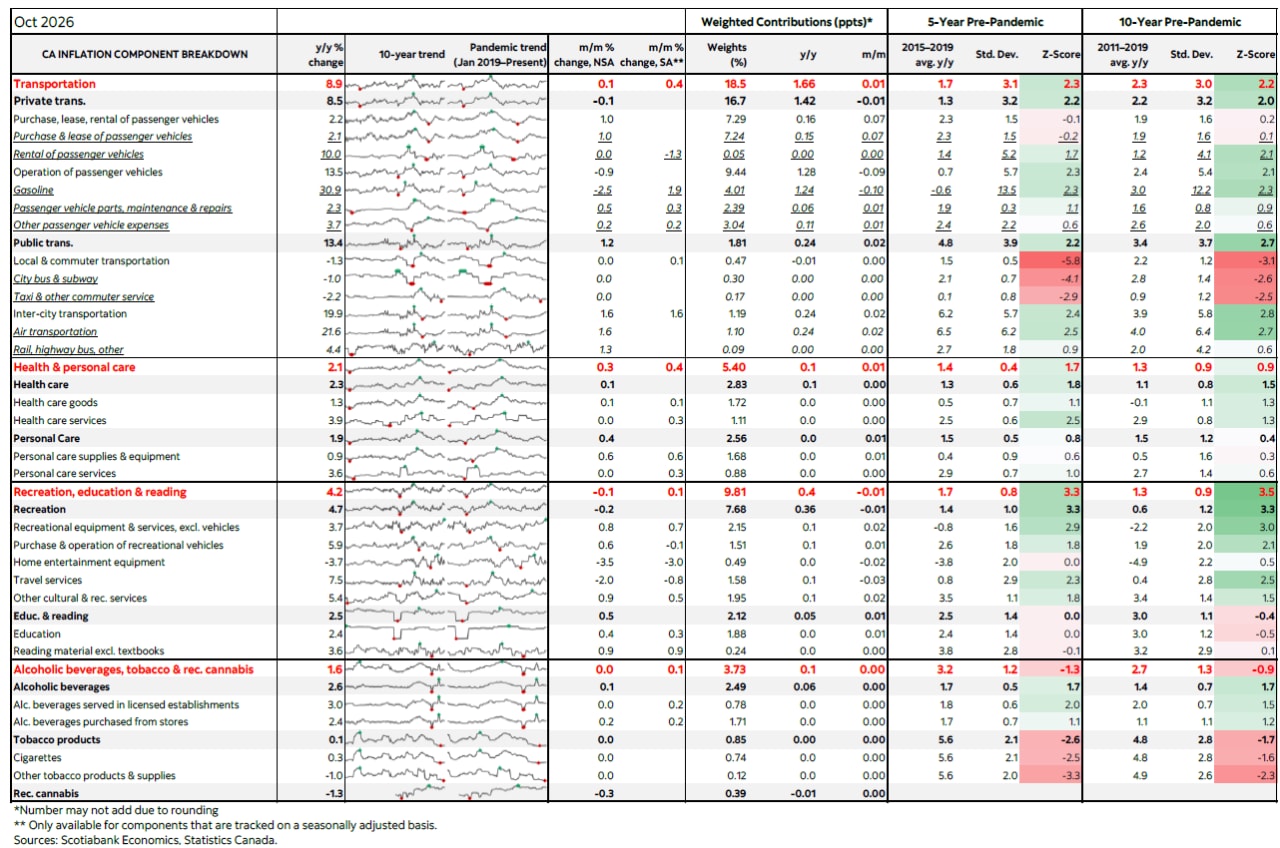
Additional charts (chart 6–22) follow along with the full table including more measures and micro-charts.
DISCLAIMER
This report has been prepared by Scotiabank Economics as a resource for the clients of Scotiabank. Opinions, estimates and projections contained herein are our own as of the date hereof and are subject to change without notice. The information and opinions contained herein have been compiled or arrived at from sources believed reliable but no representation or warranty, express or implied, is made as to their accuracy or completeness. Neither Scotiabank nor any of its officers, directors, partners, employees or affiliates accepts any liability whatsoever for any direct or consequential loss arising from any use of this report or its contents.
These reports are provided to you for informational purposes only. This report is not, and is not constructed as, an offer to sell or solicitation of any offer to buy any financial instrument, nor shall this report be construed as an opinion as to whether you should enter into any swap or trading strategy involving a swap or any other transaction. The information contained in this report is not intended to be, and does not constitute, a recommendation of a swap or trading strategy involving a swap within the meaning of U.S. Commodity Futures Trading Commission Regulation 23.434 and Appendix A thereto. This material is not intended to be individually tailored to your needs or characteristics and should not be viewed as a “call to action” or suggestion that you enter into a swap or trading strategy involving a swap or any other transaction. Scotiabank may engage in transactions in a manner inconsistent with the views discussed this report and may have positions, or be in the process of acquiring or disposing of positions, referred to in this report.
Scotiabank, its affiliates and any of their respective officers, directors and employees may from time to time take positions in currencies, act as managers, co-managers or underwriters of a public offering or act as principals or agents, deal in, own or act as market makers or advisors, brokers or commercial and/or investment bankers in relation to securities or related derivatives. As a result of these actions, Scotiabank may receive remuneration. All Scotiabank products and services are subject to the terms of applicable agreements and local regulations. Officers, directors and employees of Scotiabank and its affiliates may serve as directors of corporations.
Any securities discussed in this report may not be suitable for all investors. Scotiabank recommends that investors independently evaluate any issuer and security discussed in this report, and consult with any advisors they deem necessary prior to making any investment.
This report and all information, opinions and conclusions contained in it are protected by copyright. This information may not be reproduced without the prior express written consent of Scotiabank.
™ Trademark of The Bank of Nova Scotia. Used under license, where applicable.
Scotiabank, together with “Global Banking and Markets”, is a marketing name for the global corporate and investment banking and capital markets businesses of The Bank of Nova Scotia and certain of its affiliates in the countries where they operate, including; Scotiabank Europe plc; Scotiabank (Ireland) Designated Activity Company; Scotiabank Inverlat S.A., Institución de Banca Múltiple, Grupo Financiero Scotiabank Inverlat, Scotia Inverlat Casa de Bolsa, S.A. de C.V., Grupo Financiero Scotiabank Inverlat, Scotia Inverlat Derivados S.A. de C.V. – all members of the Scotiabank group and authorized users of the Scotiabank mark. The Bank of Nova Scotia is incorporated in Canada with limited liability and is authorised and regulated by the Office of the Superintendent of Financial Institutions Canada. The Bank of Nova Scotia is authorized by the UK Prudential Regulation Authority and is subject to regulation by the UK Financial Conduct Authority and limited regulation by the UK Prudential Regulation Authority. Details about the extent of The Bank of Nova Scotia's regulation by the UK Prudential Regulation Authority are available from us on request. Scotiabank Europe plc is authorized by the UK Prudential Regulation Authority and regulated by the UK Financial Conduct Authority and the UK Prudential Regulation Authority.
Scotiabank Inverlat, S.A., Scotia Inverlat Casa de Bolsa, S.A. de C.V, Grupo Financiero Scotiabank Inverlat, and Scotia Inverlat Derivados, S.A. de C.V., are each authorized and regulated by the Mexican financial authorities.
Not all products and services are offered in all jurisdictions. Services described are available in jurisdictions where permitted by law.