

- GDP recorded its slowest growth in three months in September.
- Weakness in primary sectors was partially offset by continued strength in domestic demand.
- For Q4-26, we estimate growth of nearly 3%; out 3.3% GDP growth forecast for 2026 now carries a downside risk.
The Peruvian economy expanded by 2.4% y/y in September, its slowest pace in the past three months, according to figures from the National Institute of Statistics and Informatics (INEI, chart 1). The result fell short of our 2.8% estimate and the 3.5% expected by the consensus of analysts surveyed by Bloomberg. With September’s result, cumulative GDP growth reached 3.2% in the first nine months of the year (table 1).
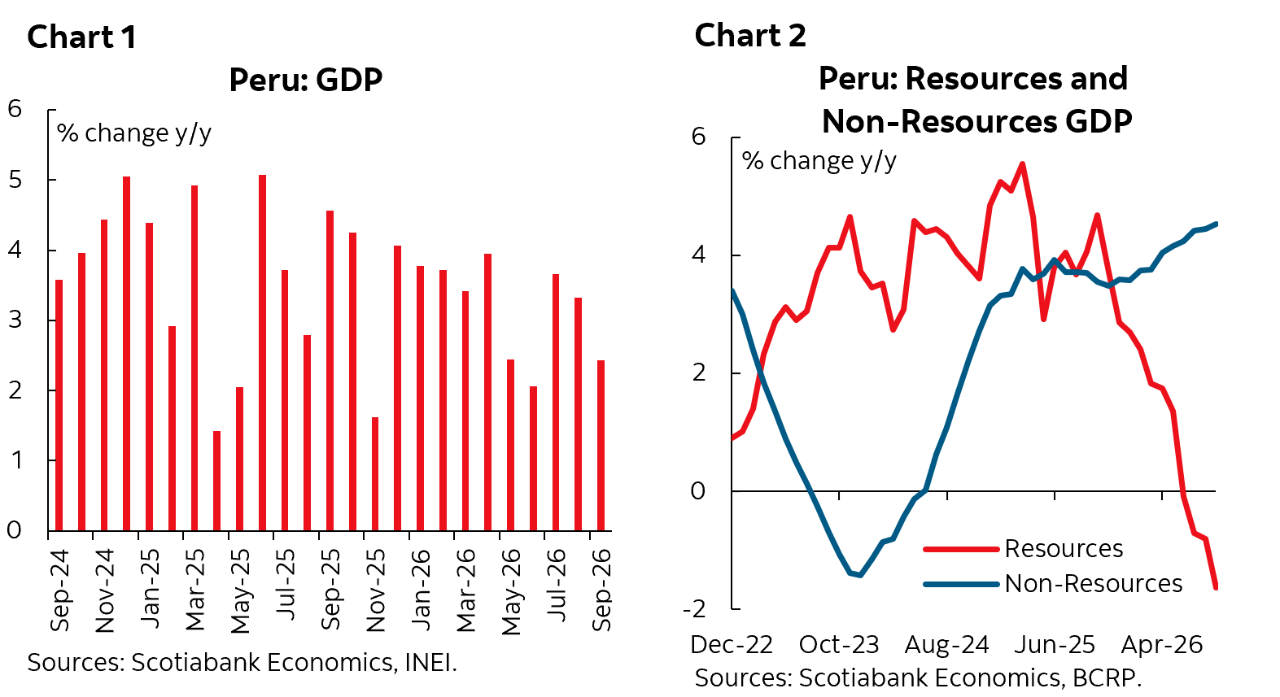
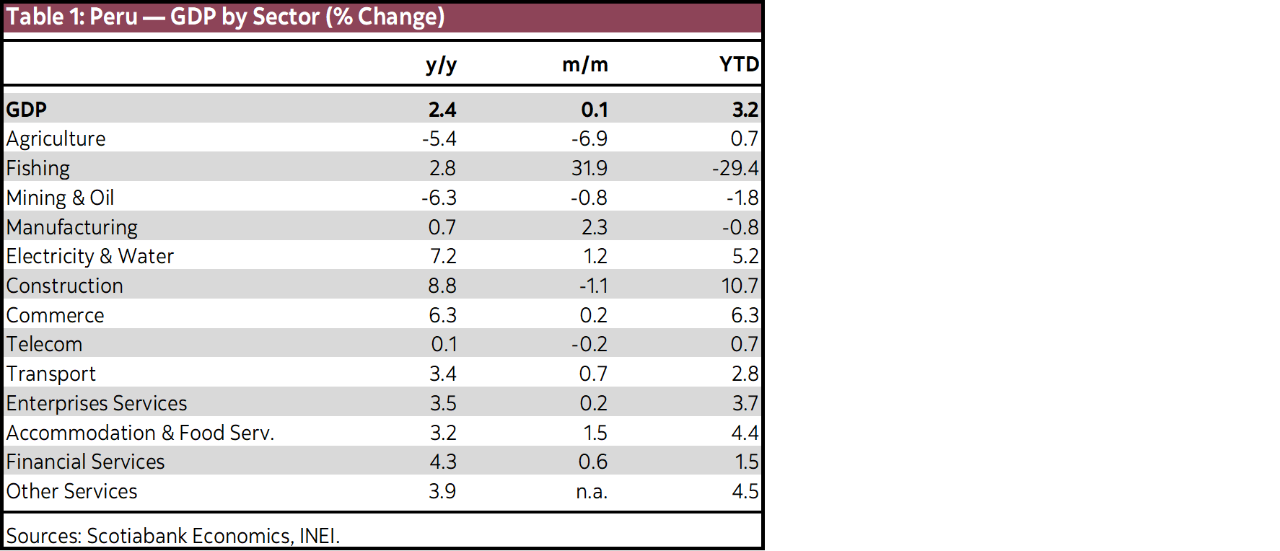
Primary sectors continued to constrain GDP expansion. The Mining and Hydrocarbons sector (-6.3% y/y) led the decline among extractive industries for the second consecutive month, shaving 0.8 percentage points off GDP growth. This weakness was unrelated to El Niño and instead reflected lower tonnage processed and ore grades, particularly for copper and gold. The hydrocarbons subsector remained stable, as a decline in oil production was offset by an increase in gas extraction.
Meanwhile, the agricultural and livestock sector (-5.4% y/y) was impacted by the El Niño event, which hit the agricultural subsector (-9.8% y/y) particularly hard. Significantly above-average temperatures along the coast affected the yields of crops such as olives, onions, corn, and sugarcane, while also bringing forward harvests for other crops, including avocados and blueberries. Meanwhile, the fishing sector (+2.8% y/y) recovered after four consecutive months of decline, driven by an increase in the landing of species intended for direct human consumption.
Non-primary sectors continued to lead the GDP expansion, most notably construction (+8.8% y/y), which was bolstered by private investment in infrastructure, real estate, mining, and energy, among other areas. The commerce sector (+6.3% y/y) also maintained its momentum, supported by rising employment and household income, although higher inflation has begun to weigh on purchasing power. The services sector also performed well, specifically transportation (+3.4% y/y), driven largely by passenger transport; accommodation and restaurants (+3.2%), reflecting an increase in domestic tourism; and the financial sector (+4.3% y/y), fueled by higher demand for credit.
For the fourth quarter, we project GDP growth of approximately 3%, broadly in line with the 3.1% recorded in Q3-26. We expect primary sectors to remain affected by El Niño, particularly fishing, following the decision not to open the second anchovy fishing season. Non-primary sectors should continue to expand, supported by resilient domestic demand. Following the weaker-than-expected September result and Q3 performance, our 3.3% GDP growth forecast for 2026 now carries downside risk.
—Pablo Nano
DISCLAIMER
This report has been prepared by Scotiabank Economics as a resource for the clients of Scotiabank. Opinions, estimates and projections contained herein are our own as of the date hereof and are subject to change without notice. The information and opinions contained herein have been compiled or arrived at from sources believed reliable but no representation or warranty, express or implied, is made as to their accuracy or completeness. Neither Scotiabank nor any of its officers, directors, partners, employees or affiliates accepts any liability whatsoever for any direct or consequential loss arising from any use of this report or its contents.
These reports are provided to you for informational purposes only. This report is not, and is not constructed as, an offer to sell or solicitation of any offer to buy any financial instrument, nor shall this report be construed as an opinion as to whether you should enter into any swap or trading strategy involving a swap or any other transaction. The information contained in this report is not intended to be, and does not constitute, a recommendation of a swap or trading strategy involving a swap within the meaning of U.S. Commodity Futures Trading Commission Regulation 23.434 and Appendix A thereto. This material is not intended to be individually tailored to your needs or characteristics and should not be viewed as a “call to action” or suggestion that you enter into a swap or trading strategy involving a swap or any other transaction. Scotiabank may engage in transactions in a manner inconsistent with the views discussed this report and may have positions, or be in the process of acquiring or disposing of positions, referred to in this report.
Scotiabank, its affiliates and any of their respective officers, directors and employees may from time to time take positions in currencies, act as managers, co-managers or underwriters of a public offering or act as principals or agents, deal in, own or act as market makers or advisors, brokers or commercial and/or investment bankers in relation to securities or related derivatives. As a result of these actions, Scotiabank may receive remuneration. All Scotiabank products and services are subject to the terms of applicable agreements and local regulations. Officers, directors and employees of Scotiabank and its affiliates may serve as directors of corporations.
Any securities discussed in this report may not be suitable for all investors. Scotiabank recommends that investors independently evaluate any issuer and security discussed in this report, and consult with any advisors they deem necessary prior to making any investment.
This report and all information, opinions and conclusions contained in it are protected by copyright. This information may not be reproduced without the prior express written consent of Scotiabank.
™ Trademark of The Bank of Nova Scotia. Used under license, where applicable.
Scotiabank, together with “Global Banking and Markets”, is a marketing name for the global corporate and investment banking and capital markets businesses of The Bank of Nova Scotia and certain of its affiliates in the countries where they operate, including; Scotiabank Europe plc; Scotiabank (Ireland) Designated Activity Company; Scotiabank Inverlat S.A., Institución de Banca Múltiple, Grupo Financiero Scotiabank Inverlat, Scotia Inverlat Casa de Bolsa, S.A. de C.V., Grupo Financiero Scotiabank Inverlat, Scotia Inverlat Derivados S.A. de C.V. – all members of the Scotiabank group and authorized users of the Scotiabank mark. The Bank of Nova Scotia is incorporated in Canada with limited liability and is authorised and regulated by the Office of the Superintendent of Financial Institutions Canada. The Bank of Nova Scotia is authorized by the UK Prudential Regulation Authority and is subject to regulation by the UK Financial Conduct Authority and limited regulation by the UK Prudential Regulation Authority. Details about the extent of The Bank of Nova Scotia's regulation by the UK Prudential Regulation Authority are available from us on request. Scotiabank Europe plc is authorized by the UK Prudential Regulation Authority and regulated by the UK Financial Conduct Authority and the UK Prudential Regulation Authority.
Scotiabank Inverlat, S.A., Scotia Inverlat Casa de Bolsa, S.A. de C.V, Grupo Financiero Scotiabank Inverlat, and Scotia Inverlat Derivados, S.A. de C.V., are each authorized and regulated by the Mexican financial authorities.
Not all products and services are offered in all jurisdictions. Services described are available in jurisdictions where permitted by law.