

- Exports rise in sixth consecutive monthly trade surplus (chart 1). The value of Canadian exports rose by 2.5% in August, led by energy products but also supported by increases in most other categories—and despite a large drop in volatile gold exports. Total imports fell 2.0%, led by an 8.8% drop in motor vehicles and parts (following a large temporary increase in July) and lower gold imports. Imports of industrial machinery and equipment (a key indicator for capital investment) continued its trend higher with a 3.5% monthly increase. Export volumes (which adjust for prices) also rose 2.5% but imports were only 1.1% lower (chart 2). Overall, a stronger report than July, but aided by front-running of new U.S. tariffs and import bans in September. Despite the stronger month, trade is likely to contribute only modestly to overall economic growth in Q3.
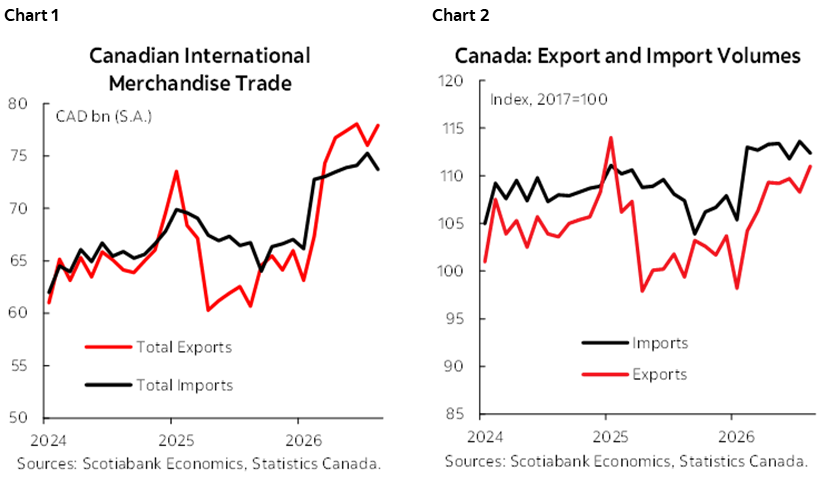
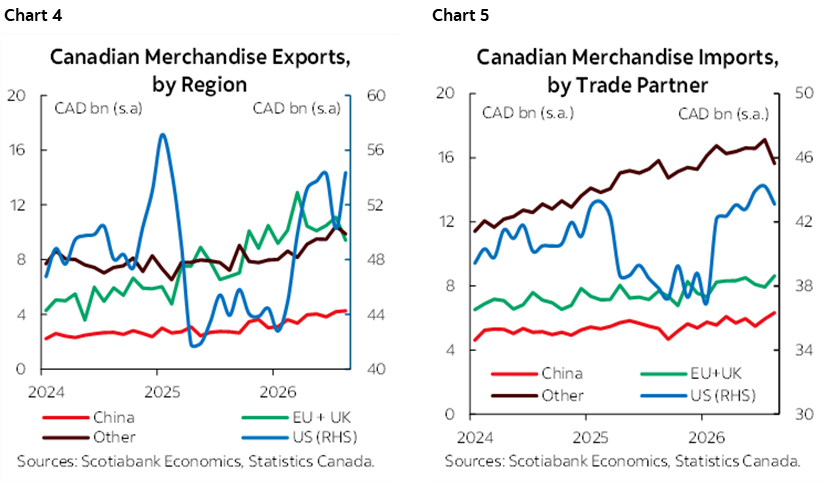
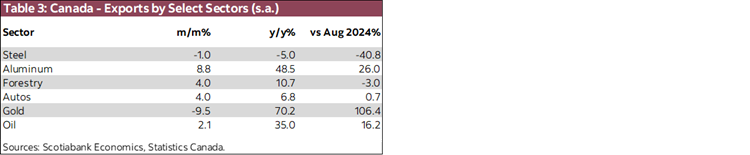
- Volatility in gold and energy exports continues to mask clear declines in some sectors. Exports are lower in most goods categories targeted by the U.S. sectoral tariffs (chart 3) including: steel (-40% vs Dec 2024), forestry (-14%), and autos (-2%)—though aluminum has recovered.
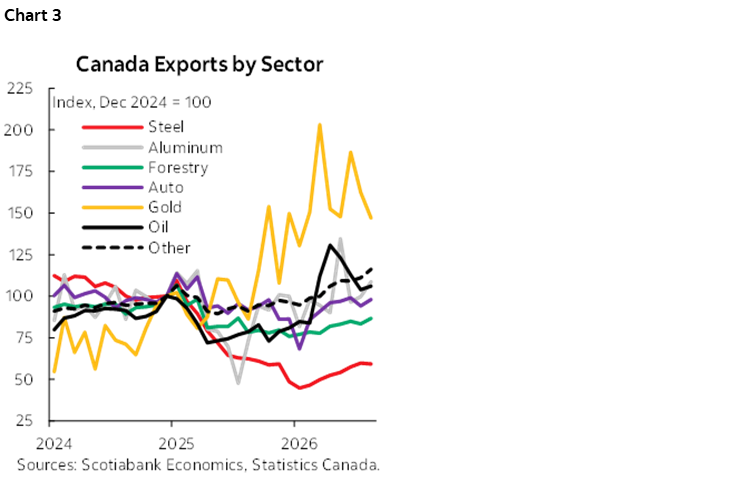
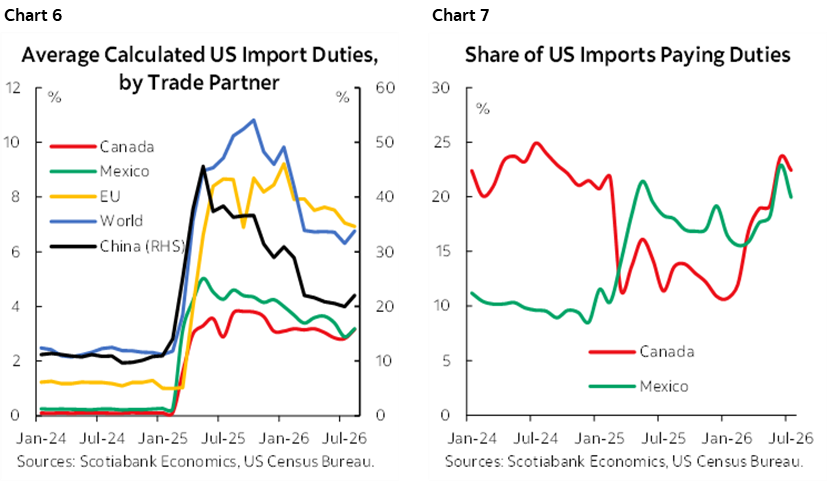
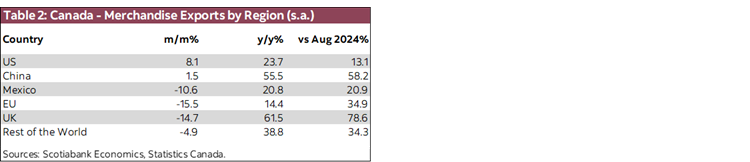
- The share of Canadian exports bound for the U.S. is volatile but trending lower, averaging 76% in 2024 and 72% in 2025, and coming in at 70% in July 2026. This has been driven by faster growth in exports to non-U.S. markets—especially Europe (chart 4). In August, exports to the U.S. rose 8.1% m/m after a drop in July, and were up 11% y/y (aided by the increase in oil prices since last year). Exports to other countries fell 8.5% m/m, but were up 51% from 2024—though much of this increase has been driven by gold. On the import side (chart 5), the share of Canadian imports from the U.S. has gradually fallen to 59% in August from an average of 62% in 2024.
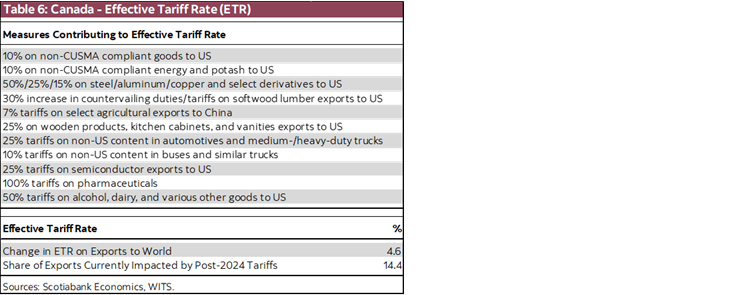
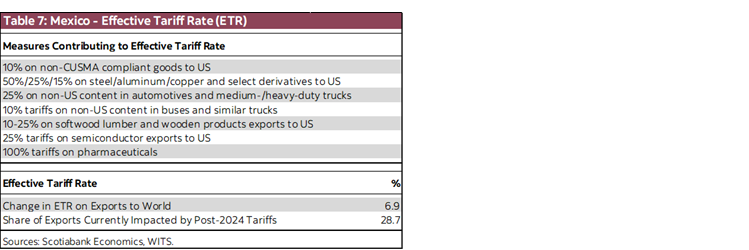
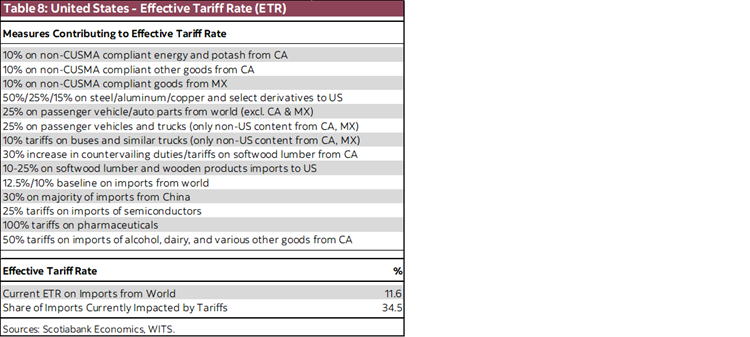
- Canada continues to benefit from a (relatively) low effective tariff rate (ETR) on total exports, though this advantage has narrowed. We estimate that Canada’s ETR has increased from around 3% to 4.6% over the last couple of months. The reported average actual duties paid on U.S. goods imports from Canada (which reflects substitution effects) had been trending lower but rose from 2.8% to 3.2% in August (chart 6) and could increase further in the coming months. The proportion of Canadian goods imported into the U.S. facing tariffs rose slightly to 23% (chart 7).
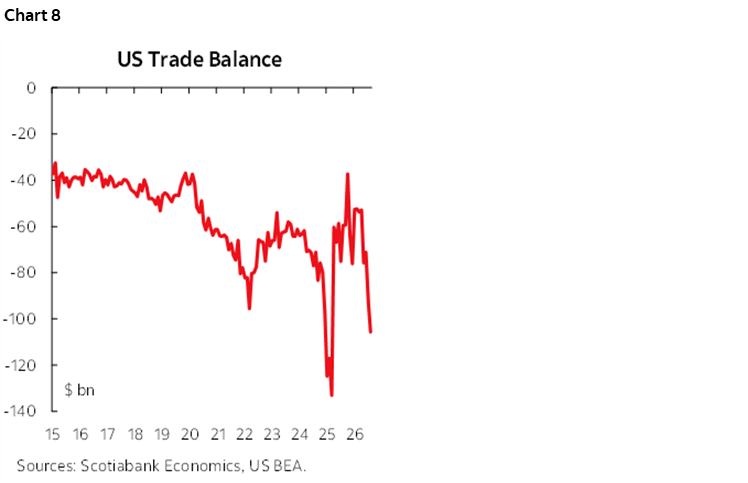
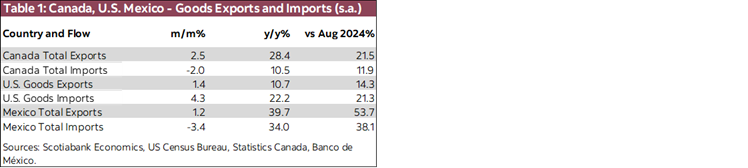
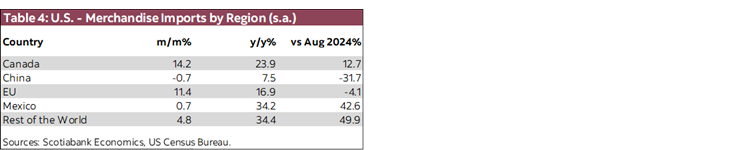
- The U.S. trade deficit increased sharply (chart 8). In August, U.S. exports rose 1.4% but imports jumped 4.3%, resulting in an increase of the U.S. trade deficit to US$105 bn—substantially larger than its average 2024 level. The increase in imports was led by strong increases in imports of industrial supplies and capital goods.
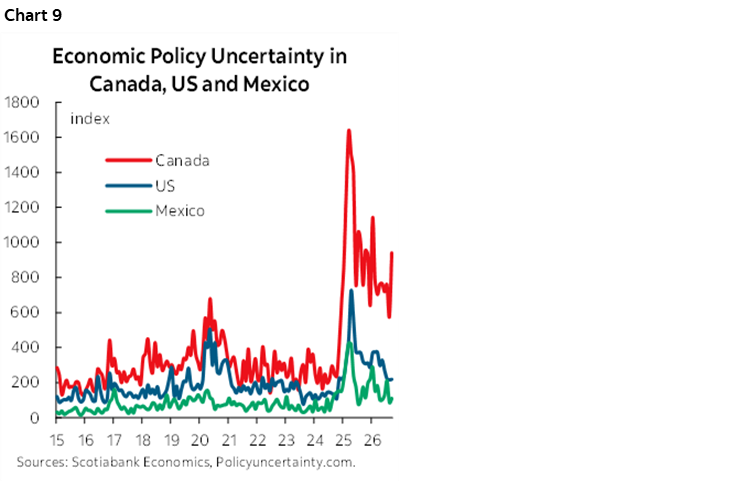
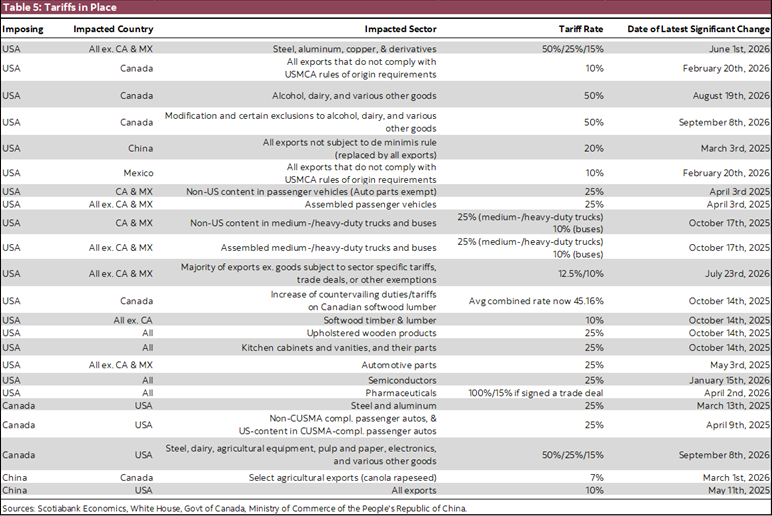
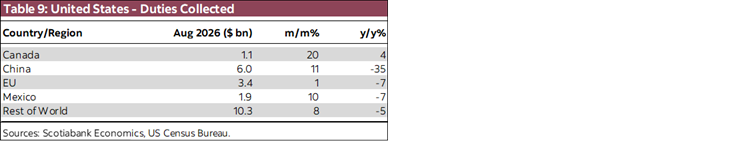
- Tariffs and uncertainty (chart 9) continue to be elevated and dynamic. Canada continues to benefit from tariff-free access to the U.S. on the vast majority of our trade, but the trade war has heated up following the latest breakdown in negotiations. Our baseline remains that Canada will emerge from the CUSMA negotiations with a competitive ETR and tariff-free access to the U.S. economy for the vast majority of our exports—but also that the path to this outcome will be volatile. There has been some tit-for-tat tariff escalation over the past couple of months, though this fortunately seems to have settled down. However, additional U.S. tariffs on autos have been threatened for January. That said, given that a deal was so close in August, there remains the potential for a deal in the coming months to avoid those tariffs as well as reduce the significant tariffs impacting some sectors.
DISCLAIMER
This report has been prepared by Scotiabank Economics as a resource for the clients of Scotiabank. Opinions, estimates and projections contained herein are our own as of the date hereof and are subject to change without notice. The information and opinions contained herein have been compiled or arrived at from sources believed reliable but no representation or warranty, express or implied, is made as to their accuracy or completeness. Neither Scotiabank nor any of its officers, directors, partners, employees or affiliates accepts any liability whatsoever for any direct or consequential loss arising from any use of this report or its contents.
These reports are provided to you for informational purposes only. This report is not, and is not constructed as, an offer to sell or solicitation of any offer to buy any financial instrument, nor shall this report be construed as an opinion as to whether you should enter into any swap or trading strategy involving a swap or any other transaction. The information contained in this report is not intended to be, and does not constitute, a recommendation of a swap or trading strategy involving a swap within the meaning of U.S. Commodity Futures Trading Commission Regulation 23.434 and Appendix A thereto. This material is not intended to be individually tailored to your needs or characteristics and should not be viewed as a “call to action” or suggestion that you enter into a swap or trading strategy involving a swap or any other transaction. Scotiabank may engage in transactions in a manner inconsistent with the views discussed this report and may have positions, or be in the process of acquiring or disposing of positions, referred to in this report.
Scotiabank, its affiliates and any of their respective officers, directors and employees may from time to time take positions in currencies, act as managers, co-managers or underwriters of a public offering or act as principals or agents, deal in, own or act as market makers or advisors, brokers or commercial and/or investment bankers in relation to securities or related derivatives. As a result of these actions, Scotiabank may receive remuneration. All Scotiabank products and services are subject to the terms of applicable agreements and local regulations. Officers, directors and employees of Scotiabank and its affiliates may serve as directors of corporations.
Any securities discussed in this report may not be suitable for all investors. Scotiabank recommends that investors independently evaluate any issuer and security discussed in this report, and consult with any advisors they deem necessary prior to making any investment.
This report and all information, opinions and conclusions contained in it are protected by copyright. This information may not be reproduced without the prior express written consent of Scotiabank.
™ Trademark of The Bank of Nova Scotia. Used under license, where applicable.
Scotiabank, together with “Global Banking and Markets”, is a marketing name for the global corporate and investment banking and capital markets businesses of The Bank of Nova Scotia and certain of its affiliates in the countries where they operate, including; Scotiabank Europe plc; Scotiabank (Ireland) Designated Activity Company; Scotiabank Inverlat S.A., Institución de Banca Múltiple, Grupo Financiero Scotiabank Inverlat, Scotia Inverlat Casa de Bolsa, S.A. de C.V., Grupo Financiero Scotiabank Inverlat, Scotia Inverlat Derivados S.A. de C.V. – all members of the Scotiabank group and authorized users of the Scotiabank mark. The Bank of Nova Scotia is incorporated in Canada with limited liability and is authorised and regulated by the Office of the Superintendent of Financial Institutions Canada. The Bank of Nova Scotia is authorized by the UK Prudential Regulation Authority and is subject to regulation by the UK Financial Conduct Authority and limited regulation by the UK Prudential Regulation Authority. Details about the extent of The Bank of Nova Scotia's regulation by the UK Prudential Regulation Authority are available from us on request. Scotiabank Europe plc is authorized by the UK Prudential Regulation Authority and regulated by the UK Financial Conduct Authority and the UK Prudential Regulation Authority.
Scotiabank Inverlat, S.A., Scotia Inverlat Casa de Bolsa, S.A. de C.V, Grupo Financiero Scotiabank Inverlat, and Scotia Inverlat Derivados, S.A. de C.V., are each authorized and regulated by the Mexican financial authorities.
Not all products and services are offered in all jurisdictions. Services described are available in jurisdictions where permitted by law.