

- GDP was revised up to 3.8% in Q2…
- …and is tracking 2% in Q3…
- …as August posted solid growth after a flat July…
- …because of prior upward revisions
- The traditional output gap has been cut by two-thirds in two quarters…
- …opening the door to the BoC lifting off…
- …from the lower end of neutral and a negative real rate with soft C$
- Canadian GDP, m/m % SA, July:
- Actual: 0.0
- Scotia: 0.1
- Consensus: 0.0
- Prior: +0.4 (revised up from 0.3%)
- August ‘flash’: +0.2
Canada’s economy is proving to be much more resilient in Q3 than negative nellies feared after a strong second quarter that itself was revised to be stronger this morning. The result is that slack is being rapidly eroded with the takeaway being that the Bank of Canada probably needs to get on with tightening policy. Canada’s 2-year yield climbed 2–3bps and CAD was flat post-data with the BoC priced as a coin flip in a month’s time and 32bps priced for December’s meeting.
July GDP matched consensus at 0.0% m/m SA against those of us who were a tick higher. The only reason for it not being higher is because June GDP was revised up a tick to solid growth of 0.4% which posed a higher than expected jumping off point.
August GDP is guided by Statcan to be tracking a gain of 0.2% m/m on a preliminary basis. I’m tracking a touch higher.
The result is that very strong growth in Q2 is being followed by decent growth in Q3 (chart 1). Q2 GDP growth was revised up from 3.6% q/q SAAR to 3.8% as Statcan revised up both April and June GDP by a tenth. Q2 GDP growth is tracking 2% q/q SAAR based on what we know about Q2 and most of Q3 while assuming September GDP will be flat solely in order to avoid skewing the math before we get any September data.
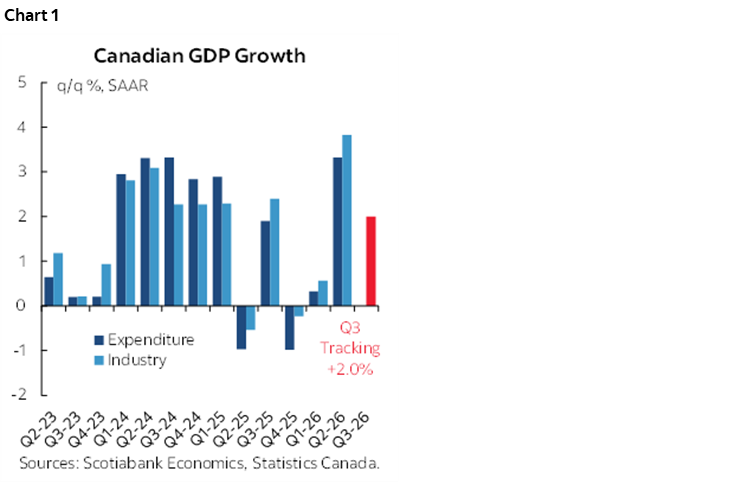
These quarterly estimates are based on monthly production-side accounts whereas the BoC and most shops put more stock in quarterly expenditure-based GDP accounts that do a better job at capturing volatile inventory and net trade effects.
But 2% after 3.8%? I'll take that!! Recall that after Canada posted strong
Q2 growth there were fears in some quarters—some legitimate, some biased—that growth would disappoint in Q3 and possibly retreat. That hasn’t happened.
The traditional output gap (potential minus actual divided by potential GDP) is tracking around -0.5% in Q3 if the upward revision to Q2 monthly GDP flows through to a similar upward revision to quarterly accounts and based on Q3 tracking. It was about -1.4% in Q1 (chart 2).
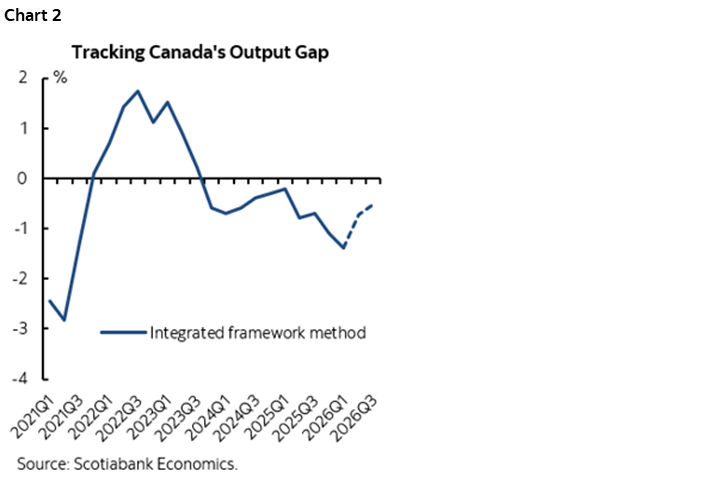
In other words, slack has been cut by two-thirds in just two quarters. There is only a fairly small amount of slack left in the economy and it’s likely to close into 2027 and will probably be overwhelmed from an inflation standpoint by other factors. Tariffs? Oh please. DJT’s gift to Canada has been high commodities and a weak C$.
Since monetary policy effects are lagged by 6–18 months for the most part, this continues to suggest that the BoC had better get on with it. Not in reckless fashion, but if you're close to eliminating slack within the monpol horizon and there are other drivers of inflation, then you probably don't need to still hang out at the lower end of the neutral rate range with a roughly zero to negative real policy rate and an undervalued C$.
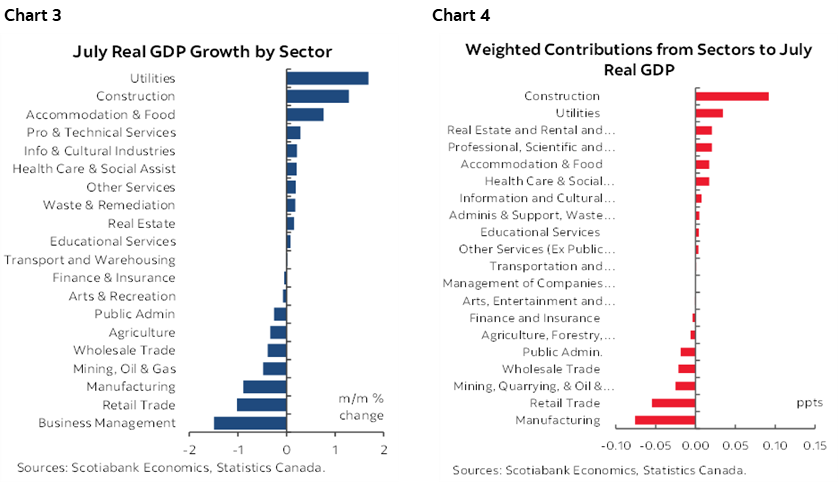
Charts 3 and 4 show the breakdown of July figures in terms of unweighted and weighted contributions respectively. It was mixed. Upsides came from construction and utilities with smaller gains in about seven other sectors. There were also notable downsides like manufacturing, mining and oil and gas extraction and retail. Recall, however, that both manufacturing and retail had posted super-sized gains in June, so some takeback in July isn’t all that surprising.
As for August, we don't get numbers for the flash August estimate, only verbiage: “Increases in mining and quarrying and retail trade were partially offset by decreases in oil and gas extraction."
DISCLAIMER
This report has been prepared by Scotiabank Economics as a resource for the clients of Scotiabank. Opinions, estimates and projections contained herein are our own as of the date hereof and are subject to change without notice. The information and opinions contained herein have been compiled or arrived at from sources believed reliable but no representation or warranty, express or implied, is made as to their accuracy or completeness. Neither Scotiabank nor any of its officers, directors, partners, employees or affiliates accepts any liability whatsoever for any direct or consequential loss arising from any use of this report or its contents.
These reports are provided to you for informational purposes only. This report is not, and is not constructed as, an offer to sell or solicitation of any offer to buy any financial instrument, nor shall this report be construed as an opinion as to whether you should enter into any swap or trading strategy involving a swap or any other transaction. The information contained in this report is not intended to be, and does not constitute, a recommendation of a swap or trading strategy involving a swap within the meaning of U.S. Commodity Futures Trading Commission Regulation 23.434 and Appendix A thereto. This material is not intended to be individually tailored to your needs or characteristics and should not be viewed as a “call to action” or suggestion that you enter into a swap or trading strategy involving a swap or any other transaction. Scotiabank may engage in transactions in a manner inconsistent with the views discussed this report and may have positions, or be in the process of acquiring or disposing of positions, referred to in this report.
Scotiabank, its affiliates and any of their respective officers, directors and employees may from time to time take positions in currencies, act as managers, co-managers or underwriters of a public offering or act as principals or agents, deal in, own or act as market makers or advisors, brokers or commercial and/or investment bankers in relation to securities or related derivatives. As a result of these actions, Scotiabank may receive remuneration. All Scotiabank products and services are subject to the terms of applicable agreements and local regulations. Officers, directors and employees of Scotiabank and its affiliates may serve as directors of corporations.
Any securities discussed in this report may not be suitable for all investors. Scotiabank recommends that investors independently evaluate any issuer and security discussed in this report, and consult with any advisors they deem necessary prior to making any investment.
This report and all information, opinions and conclusions contained in it are protected by copyright. This information may not be reproduced without the prior express written consent of Scotiabank.
™ Trademark of The Bank of Nova Scotia. Used under license, where applicable.
Scotiabank, together with “Global Banking and Markets”, is a marketing name for the global corporate and investment banking and capital markets businesses of The Bank of Nova Scotia and certain of its affiliates in the countries where they operate, including; Scotiabank Europe plc; Scotiabank (Ireland) Designated Activity Company; Scotiabank Inverlat S.A., Institución de Banca Múltiple, Grupo Financiero Scotiabank Inverlat, Scotia Inverlat Casa de Bolsa, S.A. de C.V., Grupo Financiero Scotiabank Inverlat, Scotia Inverlat Derivados S.A. de C.V. – all members of the Scotiabank group and authorized users of the Scotiabank mark. The Bank of Nova Scotia is incorporated in Canada with limited liability and is authorised and regulated by the Office of the Superintendent of Financial Institutions Canada. The Bank of Nova Scotia is authorized by the UK Prudential Regulation Authority and is subject to regulation by the UK Financial Conduct Authority and limited regulation by the UK Prudential Regulation Authority. Details about the extent of The Bank of Nova Scotia's regulation by the UK Prudential Regulation Authority are available from us on request. Scotiabank Europe plc is authorized by the UK Prudential Regulation Authority and regulated by the UK Financial Conduct Authority and the UK Prudential Regulation Authority.
Scotiabank Inverlat, S.A., Scotia Inverlat Casa de Bolsa, S.A. de C.V, Grupo Financiero Scotiabank Inverlat, and Scotia Inverlat Derivados, S.A. de C.V., are each authorized and regulated by the Mexican financial authorities.
Not all products and services are offered in all jurisdictions. Services described are available in jurisdictions where permitted by law.