
- Scotiabank Economics expects the BoC to hike by 25bps next Wednesday
- BoC’s Macklem has already pivoted to forward-looking risks…
- …that fade backward data…
- …but all smoothed measures of inflation remain warm enough amid upside risks
- BoC surveys, Alberta vote pending
- Canadian CPI, m/m / y/y %, NSA, September:
- Actual: 0.1 / 3.1
- Scotia: 0.2 / 3.2
- Consensus: 0.2 / 3.2
- Prior: -0.1 / 3.0
- Core inflation, m/m SAAR, September:
- Trimmed mean CPI: 2.2 (prior 2.8 unrevised)
- Weighted median CPI: 2.2 (prior 3.3 revised up from 2.7)
- CPI ex food and energy: 1.5 (prior 3.1 revised down from 3.9)
Backward looking Canadian CPI for one month was probably doomed to be immaterial before it landed given BoC Governor Macklem’s forward-looking warnings. Still, I believe the trend continues to provide the BoC with a warning that it needs to get on with tightening next week. We forecast the Bank of Canada will hike 25bps next week.
Markets seem to get this message. Pricing for next week’s meeting was unchanged at about 18bps of a hike post-CPI after reacting to Governor Macklem’s weekend comments. Canada 2s shook it off and remain the worst-performing front-end among the majors this morning. CAD barely flinched, depreciating a quarter cent post-data but was also probably influenced by volatile WTI.
It’s not a slam dunk call but there is probably enough supporting evidence for a hike. BoC Governor Macklem sounds like he’s fading backward looking data in favour of a higher forward-looking inflation forecast and higher inflation risk. The BoC looks at trends, not spot data anyway. If a hike is significantly priced, then they’re likely to deliver one since easing financial conditions by whiffing would be tough to justify. They struck out “appropriate” reference to the policy rate last time presumably as a warning, and the warnings on forward-looking inflation risks have been consistently pointing to raising the forecast and being increasingly concerned about upside risk. They’re at the lower bound of neutral and negative in real rate terms, so there is a need to balance the forward-looking inflation risks especially given long lagging effects of policy rate changes. As noted, the BoC staffers have a serial addiction to missing inflection points on inflation risk and routinely underestimating it as shown in the chart in this morning’s note. Governing Council should lean toward an insurance hike at this meeting and with careful guidance on the path forward. That path forward, however, could well include post-midterms escalation of the Iran war and higher energy and other commodity prices and another expansionary Federal budget. Monetary policy needs to sterilize some fiscal and commodity pressures as slack closes. Waiting even longer could put the BoC further behind the evolving upside risks to inflation especially given long and lagging effects of monetary policy adjustments.
Total CPI increased a tick to 3.1% y/y after it climbed by 0.4% m/m SA and 0.1% m/m NSA. That was a tick lower than consensus on both the m/m NSA and y/y rates but positions overall inflation at the top end of the 1–3% target range.
Underlying core measures of inflation ebbed a little in September but there were some upward revisions to consider, and the smoothed trend remains warm enough. Chart 1 shows the figures in m/m SAAR terms so far this year.
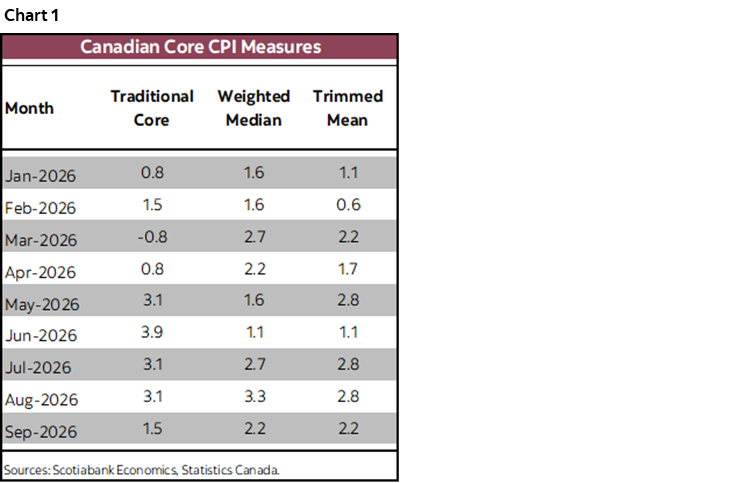
Chart 2 shows the smoothed m/m SAAR weighted median and trimmed mean core readings using a three-month moving average. They are trending up, notwithstanding monthly volatility shown charts 3 and 4. There is obvious trend pass through.
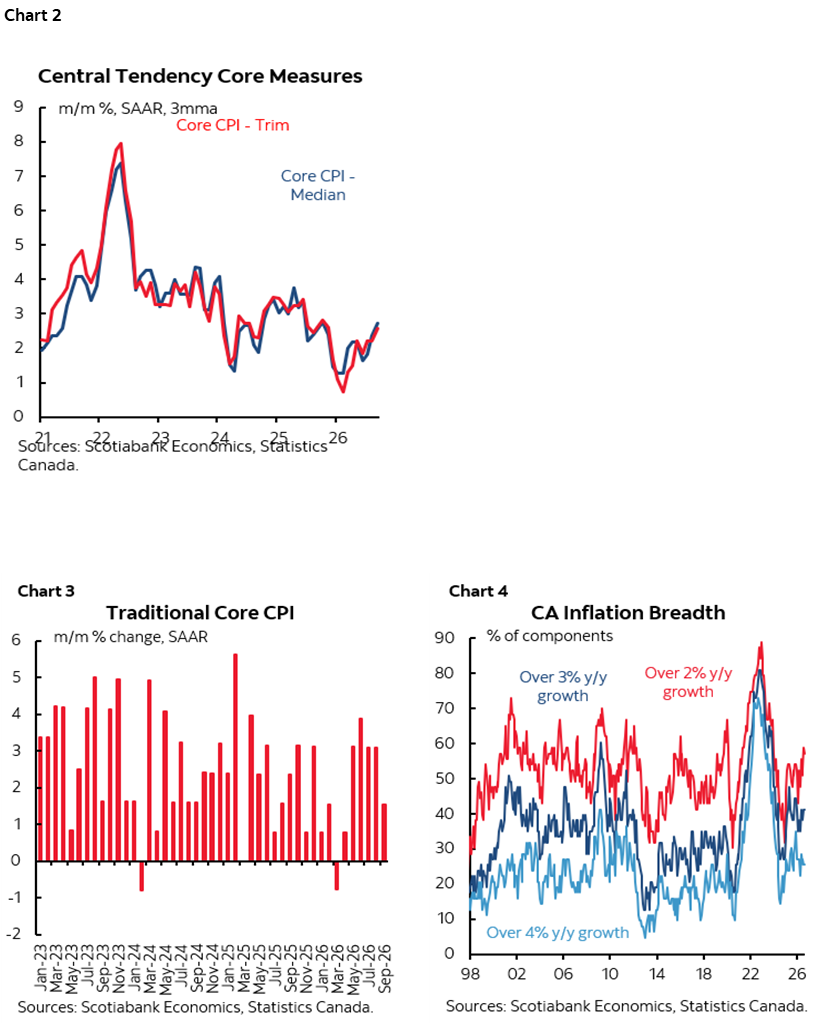
Traditional core CPI (ex-food and energy) climbed by 1.5% m/m SAAR which is the weakest reading since April after a string of four consecutive m/m SAAR readings above 3%. The 3-mo moving average is now 2.6% m/m SAAR. The year-over-year rate remained at 2.1%. Here too, there is clear evidence of pass through.
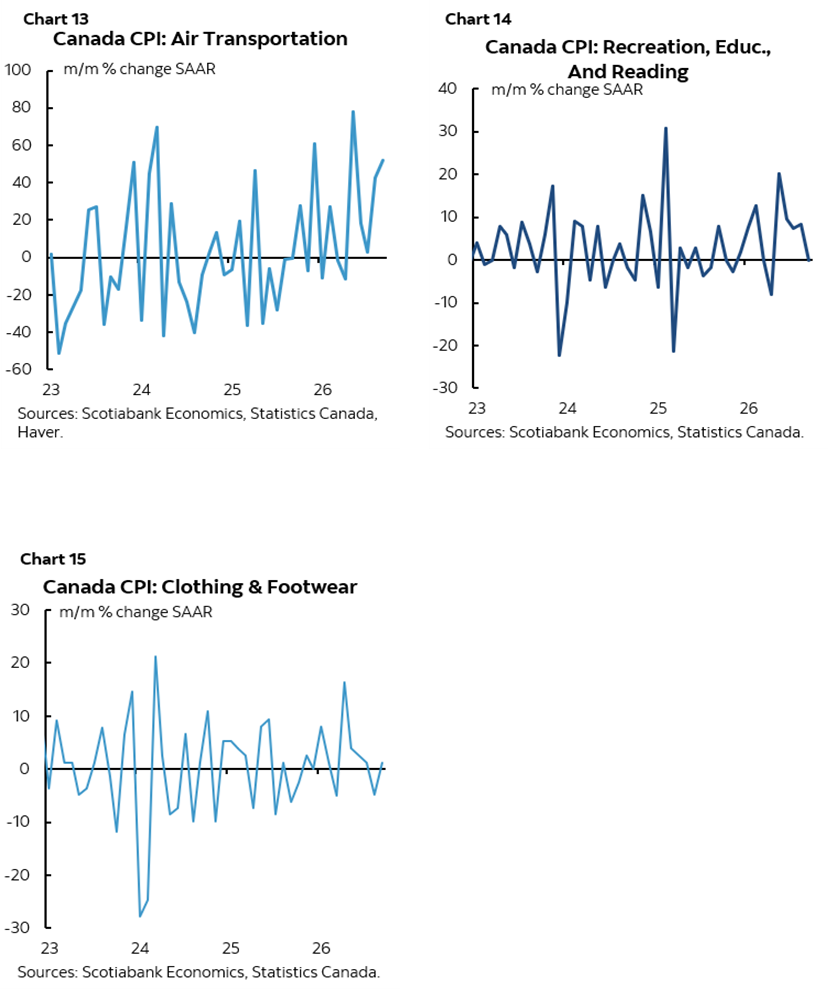
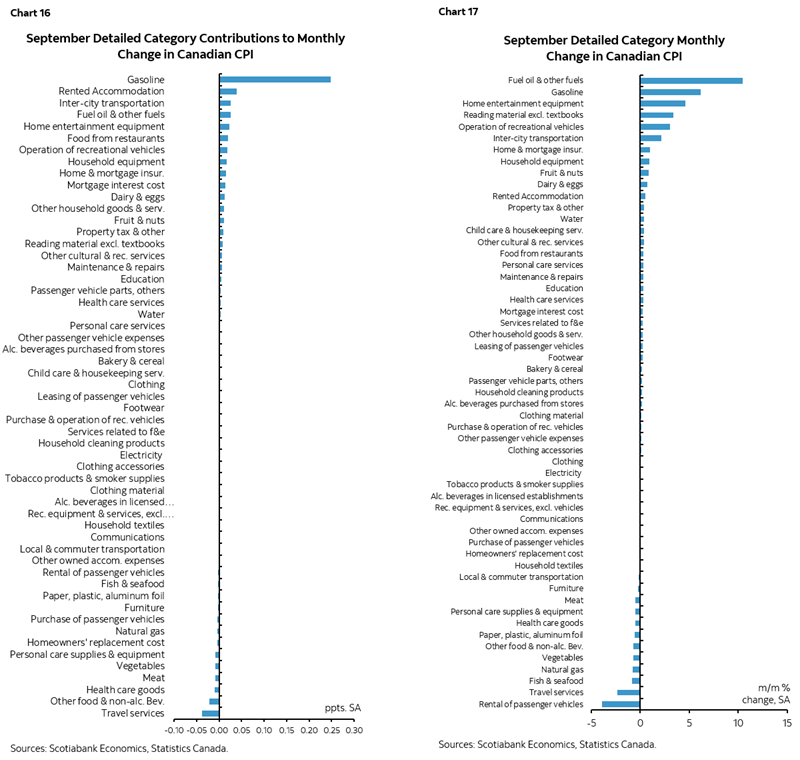
What dragged down traditional core CPI m/m SAAR in September? Folks travelled less than usual after a summertime surge and as the adorable little critters went back to school and folks wrapped up summer vacays. The impact was much bigger than seasonally normal. Prices for overall travel services fell 25% m/m SAAR in September with a 1.58% weight in the basket that knocks 0.4% m/m SAAR off total CPI and 0.5% m/m SAAR off core CPI. Car rental prices were down 38% m/m SAAR. These are such large declines as to inspire caution toward data quality, and yet you don't hold the policy rate because folks travelled less in September. Take out travel stuff and traditional core CPI would have been much warmer and broader.
Weighted median CPI was up by 2.7% m/m SAAR and revised up by over half a point in August for a three-month moving average of 2.7% m/m SAAR. The y/y WM measure is meaningless at 1.9% since it is calculated as a m/m compounded sum that turns too slowly at inflection points which is why we emphasize m/m.
Trimmed mean CPI was up 2.6% m/m SAAR and unrevised, for a three-month moving average of 2.6% m/m SAAR. The y/y rate of 1.8% is also meaningless for the same reason as above.
Breadth is marked by almost 60% of the basket rising by 2% y/y or more (chart 5).
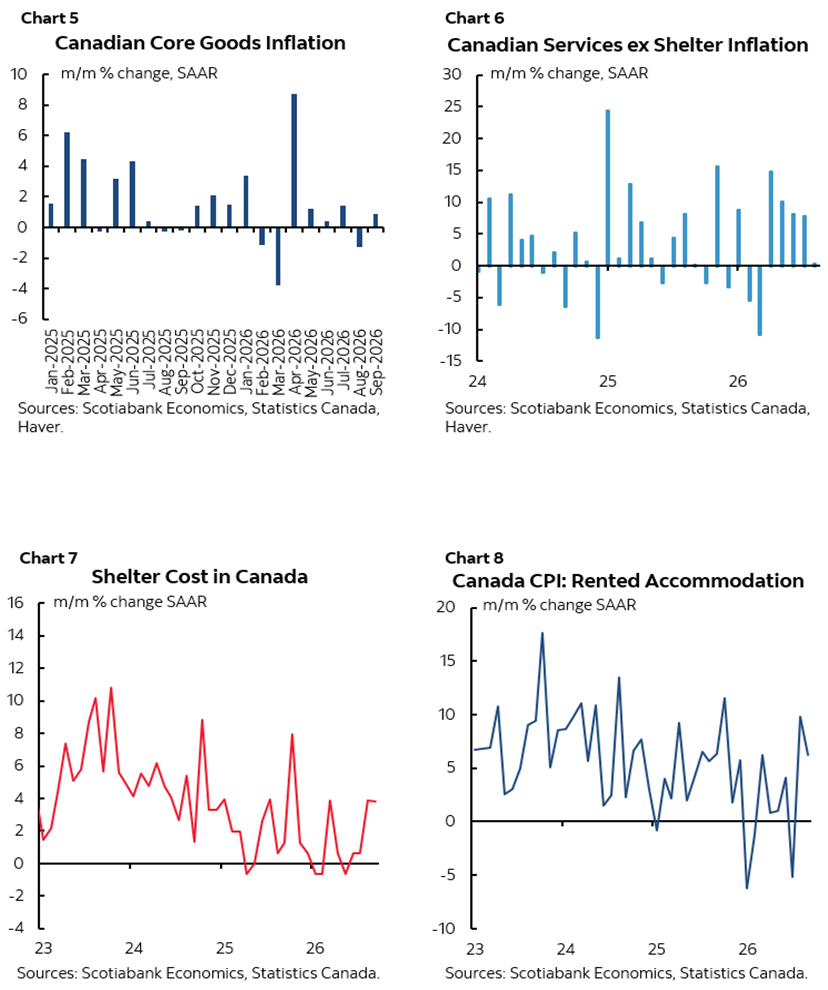
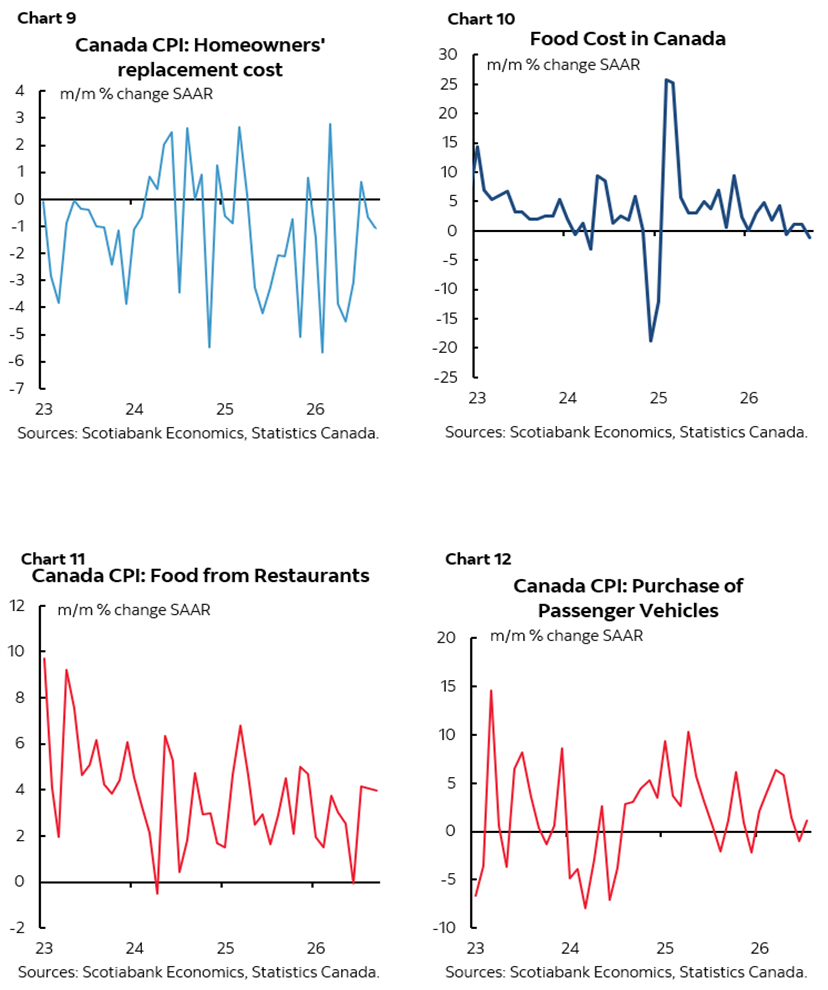
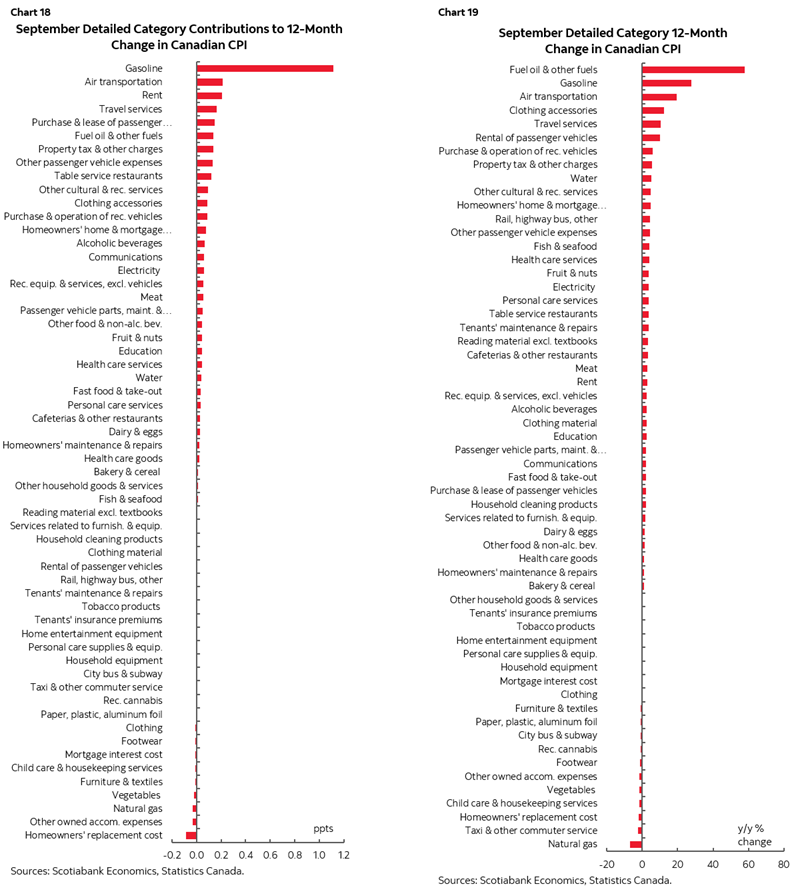
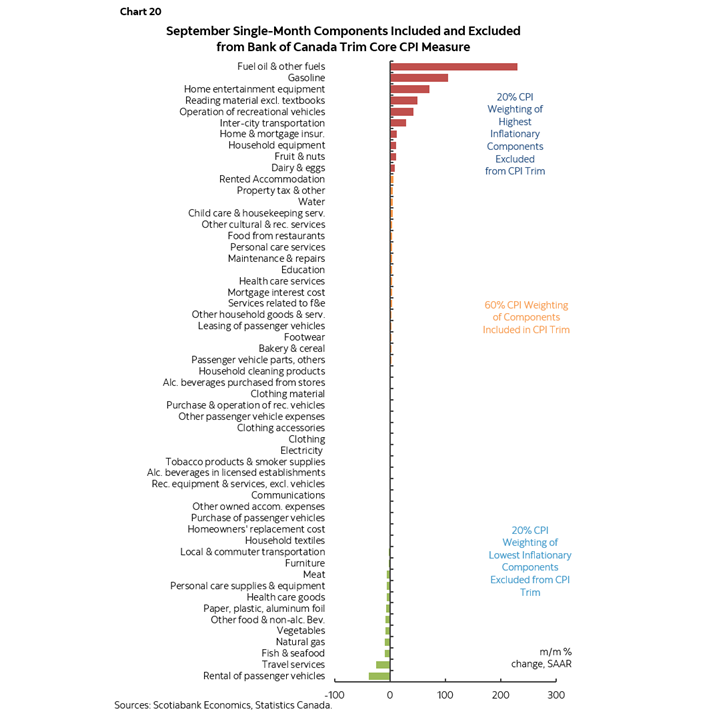
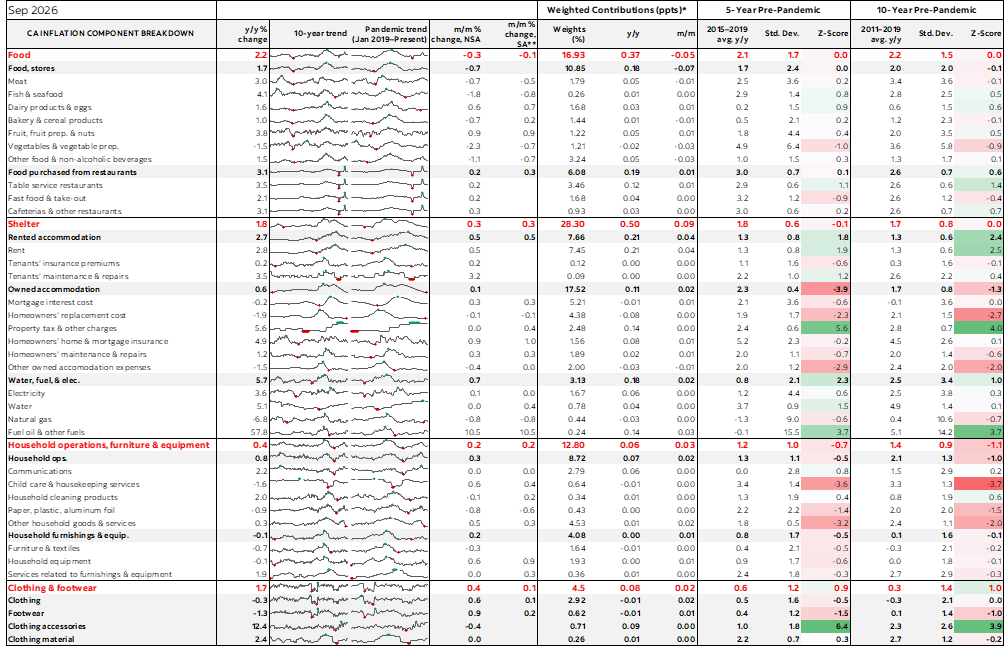
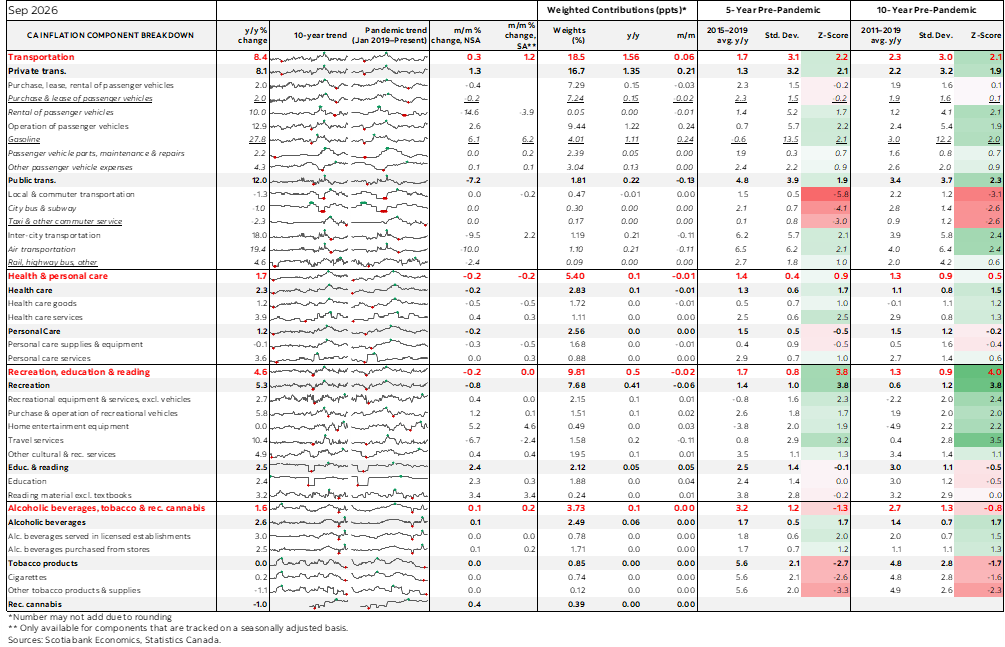
Core goods inflation increased in September (chart 5), while services inflation eased (chart 6) but the trend remains warm especially ex-travel services. Charts 7-15 break down various parts of the basket. Charts 16-19 break down the basket in m/m and y/y terms using weighted contributions and unweighted price changes. Chart 20 shows what was included in trimmed mean this time.
DISCLAIMER
This report has been prepared by Scotiabank Economics as a resource for the clients of Scotiabank. Opinions, estimates and projections contained herein are our own as of the date hereof and are subject to change without notice. The information and opinions contained herein have been compiled or arrived at from sources believed reliable but no representation or warranty, express or implied, is made as to their accuracy or completeness. Neither Scotiabank nor any of its officers, directors, partners, employees or affiliates accepts any liability whatsoever for any direct or consequential loss arising from any use of this report or its contents.
These reports are provided to you for informational purposes only. This report is not, and is not constructed as, an offer to sell or solicitation of any offer to buy any financial instrument, nor shall this report be construed as an opinion as to whether you should enter into any swap or trading strategy involving a swap or any other transaction. The information contained in this report is not intended to be, and does not constitute, a recommendation of a swap or trading strategy involving a swap within the meaning of U.S. Commodity Futures Trading Commission Regulation 23.434 and Appendix A thereto. This material is not intended to be individually tailored to your needs or characteristics and should not be viewed as a “call to action” or suggestion that you enter into a swap or trading strategy involving a swap or any other transaction. Scotiabank may engage in transactions in a manner inconsistent with the views discussed this report and may have positions, or be in the process of acquiring or disposing of positions, referred to in this report.
Scotiabank, its affiliates and any of their respective officers, directors and employees may from time to time take positions in currencies, act as managers, co-managers or underwriters of a public offering or act as principals or agents, deal in, own or act as market makers or advisors, brokers or commercial and/or investment bankers in relation to securities or related derivatives. As a result of these actions, Scotiabank may receive remuneration. All Scotiabank products and services are subject to the terms of applicable agreements and local regulations. Officers, directors and employees of Scotiabank and its affiliates may serve as directors of corporations.
Any securities discussed in this report may not be suitable for all investors. Scotiabank recommends that investors independently evaluate any issuer and security discussed in this report, and consult with any advisors they deem necessary prior to making any investment.
This report and all information, opinions and conclusions contained in it are protected by copyright. This information may not be reproduced without the prior express written consent of Scotiabank.
™ Trademark of The Bank of Nova Scotia. Used under license, where applicable.
Scotiabank, together with “Global Banking and Markets”, is a marketing name for the global corporate and investment banking and capital markets businesses of The Bank of Nova Scotia and certain of its affiliates in the countries where they operate, including; Scotiabank Europe plc; Scotiabank (Ireland) Designated Activity Company; Scotiabank Inverlat S.A., Institución de Banca Múltiple, Grupo Financiero Scotiabank Inverlat, Scotia Inverlat Casa de Bolsa, S.A. de C.V., Grupo Financiero Scotiabank Inverlat, Scotia Inverlat Derivados S.A. de C.V. – all members of the Scotiabank group and authorized users of the Scotiabank mark. The Bank of Nova Scotia is incorporated in Canada with limited liability and is authorised and regulated by the Office of the Superintendent of Financial Institutions Canada. The Bank of Nova Scotia is authorized by the UK Prudential Regulation Authority and is subject to regulation by the UK Financial Conduct Authority and limited regulation by the UK Prudential Regulation Authority. Details about the extent of The Bank of Nova Scotia's regulation by the UK Prudential Regulation Authority are available from us on request. Scotiabank Europe plc is authorized by the UK Prudential Regulation Authority and regulated by the UK Financial Conduct Authority and the UK Prudential Regulation Authority.
Scotiabank Inverlat, S.A., Scotia Inverlat Casa de Bolsa, S.A. de C.V, Grupo Financiero Scotiabank Inverlat, and Scotia Inverlat Derivados, S.A. de C.V., are each authorized and regulated by the Mexican financial authorities.
Not all products and services are offered in all jurisdictions. Services described are available in jurisdictions where permitted by law.