
ON DECK FOR TUESDAY, SEPTEMBER 29th
KEY POINTS:
- Modest market moves await Canadian, US developments
- Wistful deal talk is just that for both Iran and Canada
- Canadian GDP to inform how resilient Q3 is after a strong Q2
- BoC’s Gravelle to give balance sheet speech
- US consumer confidence and JOLTS on tap
- US house prices continue to fall in real terms
- Plenty of Fed-speak
- RBA hikes, then goes wet noodle
- Spanish CPI kicks off EZ tracking on warm footings
- Global Week Ahead — All the World’s a Stage (reminder here)
The start of todays’ race may not be the same as the end after several US and Canadian releases and a Bank of Canada speech are released. The dollar is broadly firmer, oil prices are a few dimes lower, stocks are little changed in N.A. futures with European cash markets up a bit. Yawn. Oil prices have insatiable thirst for the Monty Python Let’s Make a Deal show in Washington that nobody truly believes or shouldn’t. Iran is begging for a deal no more than Canada is despite the delusional White House rhetoric.
CANADIAN GDP—ANOTHER RESILIENT QUARTER?
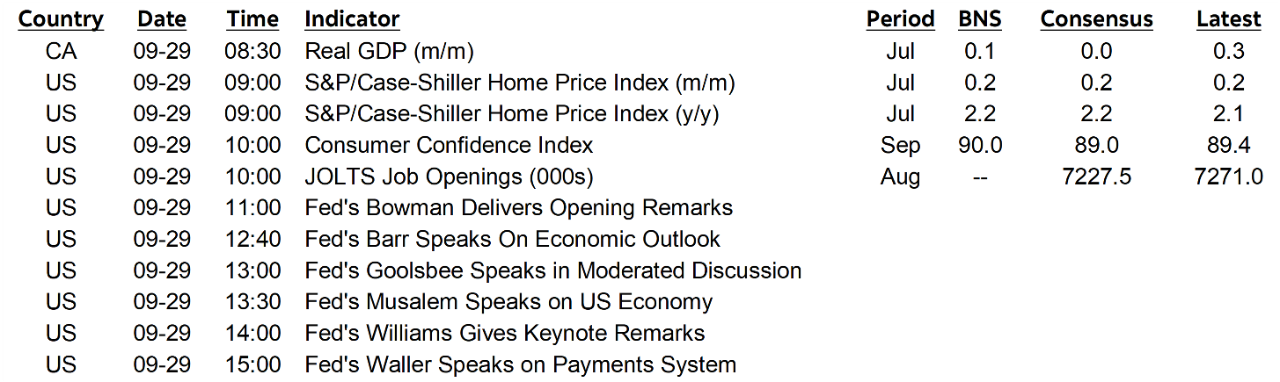
July and preliminary August readings will inform tracking of Q3 GDP growth (8:30amET). Statcan had guided "essentially unchanged" in its advance reading for July which can usually mean -0.1% to +0.1% m/m and I went with 0.1%. Consensus is divided between flat and 0.1% with a couple at -0.1%. Whatever. Eventually the reading will get revised as fast as the Blue Jays spin on a horrendous season.
August may come in stronger based on limited data to date such as a strong gain in hours worked which matters since GDP is hours times labour productivity. We could be left tracking GDP growth around 2% q/q SAAR or better when the dust settles.
BOC SPEECH ON FUNDING MARKETS
Is the BoC trying to push settlement balances too low?
Bank of Canada Deputy Governor Gravelle may weigh in on the topic early this afternoon when he speaks on "Repo markets and monetary policy implementation" (1:20pmET). No Q&A or presser, only a written speech. If we’re lucky, there will be visuals, maybe a nice vista of Lake Ontario say.
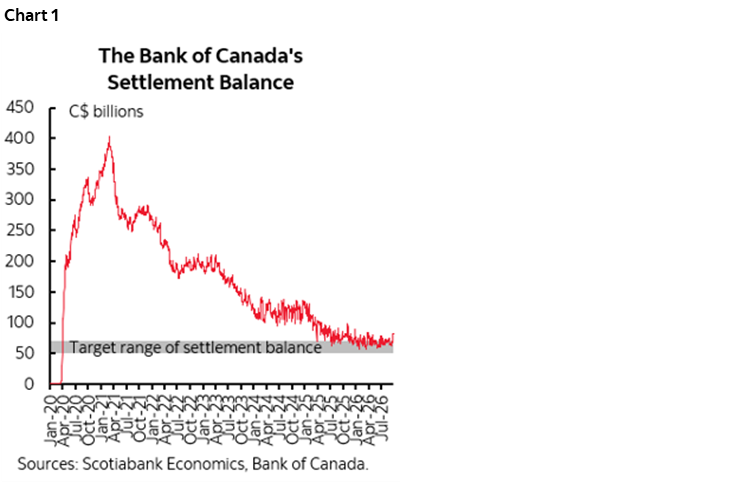
The BoC has tended to underestimate the level of optimal settlement balances needed in the financial system. They raised the target range from $20-60B to $50–70B last year. The target could still be too low with balances presently sitting at about $80B (chart 1). The BoC’s argument in targeting lower reserves than the Federal Reserve’s ample framework has been that Canadian banks are special. While I have a soft spot for them and generally agree, they’re not so special that you can play Russian roulette with how low reserves are allowed to go on a proportionate basis. The BoC has been pumping heavy volumes of repo purchases of securities to inject liquidity, roughly doubling this year to about $60B now. Globally, repo activity is on fire.
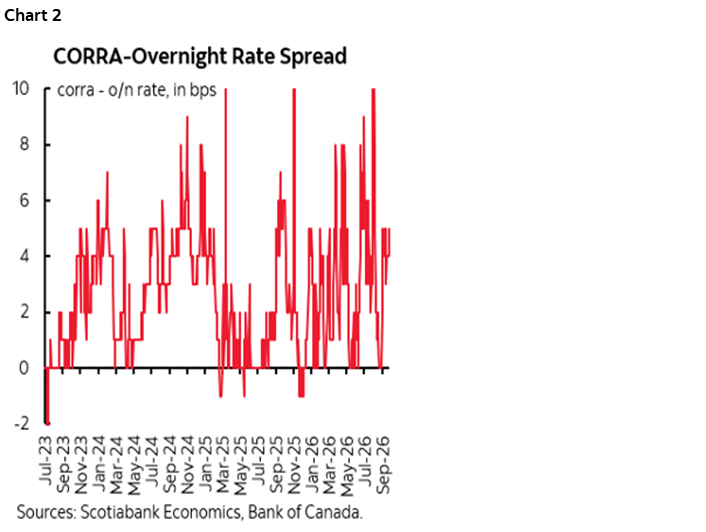
And yet the CORRA spread over the overnight rate is persistently positive when it should be on the target (chart 2). This signals funding strains in the financial system. Holdings are narrowly based, there may be unusual funding demands to feed rate change expectations, and there may be a need to target higher reserves.
The interconnectedness of the components on the BoC’s balance sheet and the two identities being sought in the quest for a more normal balance sheet keep everything in play. Interest bearing assets are eventually being targeted to equal interest bearing liabilities while GoC bond holdings are eventually targeted to equal currency in circulation. Neither is close to such goals.
So, on that note, also watch for any updated guidance on when the BoC may return to gross GoC bond buying. They previously guided that they could do so in 2027 in the normal conduct of monetary policy implementation but that they would provide advance notice.
Whatever is announced today could update day-to-day operations like the repo book, or be implemented as soon as at the next BoC decision on October 28th given the past pattern, or be a longer-run guide to bond purchases. We haven’t had a meaty speech on balance sheet management from the BoC in a gerbil’s age so any or all of the above could be on the docket. See my weekly for more.
US RELEASES—CONFIDENCE, JOLTS
A hat trick of US releases could be impactful to short term markets this morning. The most consequential ones arrive at 10amET. Consumer confidence for September and JOLTS job openings and related metrics for August often elicit a market nod. That's despite the fact that neither measure performs terribly well as input to a consumer spending or nonfarm payrolls forecast. Repeat sale home prices are also due (9amET) and continue to fall in real terms.
We'll also get a bunch of Fed speak today (Bowman, Barr, Goolsbee, Musalem, Williams and Waller). My, how they’ve all jumped on the hike bandwagon compared to a short time ago when there was a greater variety of views. Group think? Or Chair Warsh’s powers of persuasion? Something else?
RBA HIKED THEN WENT WET NOODLE
Australia's central bank raised its cash rate target by 25bps to 4.6% as universally expected. It's the fourth hike and while they left the door open to do more, the language sounded hopeful that maybe that’s enough. The Aussie front-end rallied 7bps in a 2s10s steepener while the A$ lost a little ground to the greenback.
SPAIN KICKED OFF EZ CPI TRACKING
Spanish inflation started the monthly parade of September readings across the Eurozone on the wrong foot. The readings were warmer than expected but not so warm as to materially impact what is mostly priced for an ECB hold on October 29th.
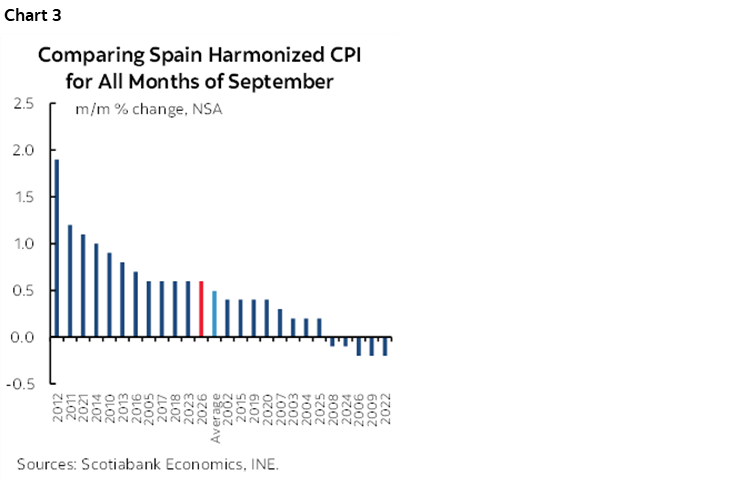
CPI was up 0.3% m/m (0.1% consensus) and 4.9% y/y (4.6% consensus). Core CPI was up 3.1% y/y (3% consensus) and chart 3 shows that it was a slightly warmer than average month for core cpi on a m/m basis.
The Eurozone tally will be released on Friday after more individual countries released starting tomorrow.
I'm out for the rest of this week with publishing resuming on Monday.
DISCLAIMER
This report has been prepared by Scotiabank Economics as a resource for the clients of Scotiabank. Opinions, estimates and projections contained herein are our own as of the date hereof and are subject to change without notice. The information and opinions contained herein have been compiled or arrived at from sources believed reliable but no representation or warranty, express or implied, is made as to their accuracy or completeness. Neither Scotiabank nor any of its officers, directors, partners, employees or affiliates accepts any liability whatsoever for any direct or consequential loss arising from any use of this report or its contents.
These reports are provided to you for informational purposes only. This report is not, and is not constructed as, an offer to sell or solicitation of any offer to buy any financial instrument, nor shall this report be construed as an opinion as to whether you should enter into any swap or trading strategy involving a swap or any other transaction. The information contained in this report is not intended to be, and does not constitute, a recommendation of a swap or trading strategy involving a swap within the meaning of U.S. Commodity Futures Trading Commission Regulation 23.434 and Appendix A thereto. This material is not intended to be individually tailored to your needs or characteristics and should not be viewed as a “call to action” or suggestion that you enter into a swap or trading strategy involving a swap or any other transaction. Scotiabank may engage in transactions in a manner inconsistent with the views discussed this report and may have positions, or be in the process of acquiring or disposing of positions, referred to in this report.
Scotiabank, its affiliates and any of their respective officers, directors and employees may from time to time take positions in currencies, act as managers, co-managers or underwriters of a public offering or act as principals or agents, deal in, own or act as market makers or advisors, brokers or commercial and/or investment bankers in relation to securities or related derivatives. As a result of these actions, Scotiabank may receive remuneration. All Scotiabank products and services are subject to the terms of applicable agreements and local regulations. Officers, directors and employees of Scotiabank and its affiliates may serve as directors of corporations.
Any securities discussed in this report may not be suitable for all investors. Scotiabank recommends that investors independently evaluate any issuer and security discussed in this report, and consult with any advisors they deem necessary prior to making any investment.
This report and all information, opinions and conclusions contained in it are protected by copyright. This information may not be reproduced without the prior express written consent of Scotiabank.
™ Trademark of The Bank of Nova Scotia. Used under license, where applicable.
Scotiabank, together with “Global Banking and Markets”, is a marketing name for the global corporate and investment banking and capital markets businesses of The Bank of Nova Scotia and certain of its affiliates in the countries where they operate, including; Scotiabank Europe plc; Scotiabank (Ireland) Designated Activity Company; Scotiabank Inverlat S.A., Institución de Banca Múltiple, Grupo Financiero Scotiabank Inverlat, Scotia Inverlat Casa de Bolsa, S.A. de C.V., Grupo Financiero Scotiabank Inverlat, Scotia Inverlat Derivados S.A. de C.V. – all members of the Scotiabank group and authorized users of the Scotiabank mark. The Bank of Nova Scotia is incorporated in Canada with limited liability and is authorised and regulated by the Office of the Superintendent of Financial Institutions Canada. The Bank of Nova Scotia is authorized by the UK Prudential Regulation Authority and is subject to regulation by the UK Financial Conduct Authority and limited regulation by the UK Prudential Regulation Authority. Details about the extent of The Bank of Nova Scotia's regulation by the UK Prudential Regulation Authority are available from us on request. Scotiabank Europe plc is authorized by the UK Prudential Regulation Authority and regulated by the UK Financial Conduct Authority and the UK Prudential Regulation Authority.
Scotiabank Inverlat, S.A., Scotia Inverlat Casa de Bolsa, S.A. de C.V, Grupo Financiero Scotiabank Inverlat, and Scotia Inverlat Derivados, S.A. de C.V., are each authorized and regulated by the Mexican financial authorities.
Not all products and services are offered in all jurisdictions. Services described are available in jurisdictions where permitted by law.