

ON DECK FOR FRIDAY, OCTOBER 9th
KEY POINTS:
- Global markets ending the week on more positive footings
- Canadian jobs — spin the wheel!
- US UMich update — down on the outlook, but still spending
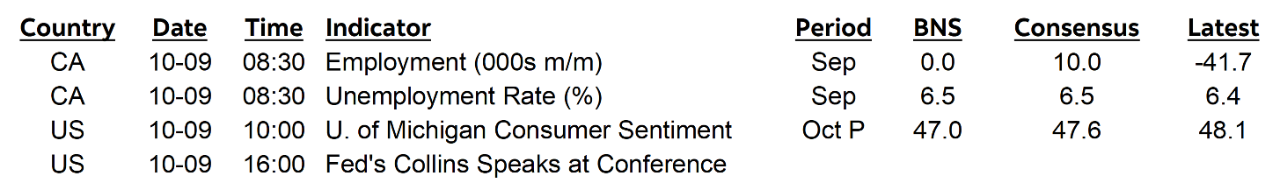
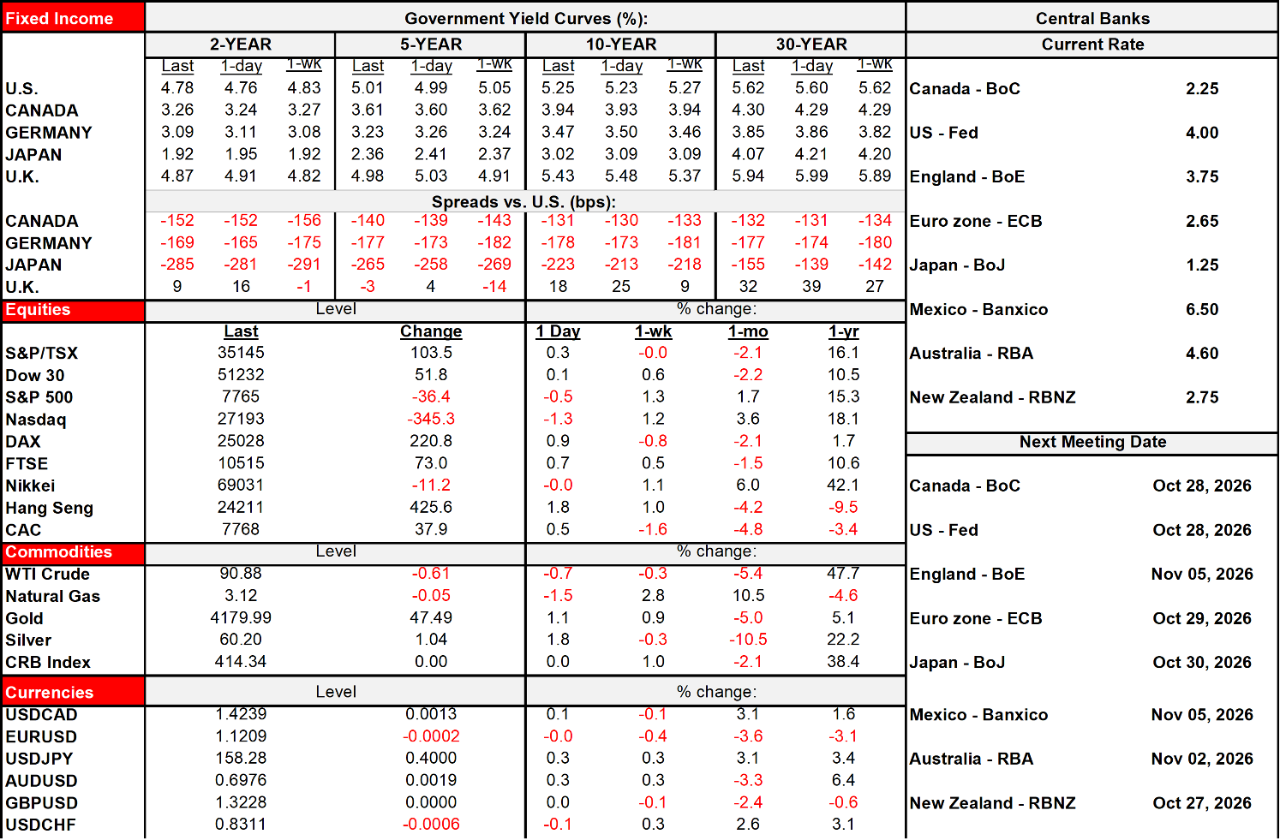
Markets are closing out the week in a somewhat more constructive mood. Equities are broadly higher by ¼% to ¾% across pre-open N.A. futures and up to 1% in European cash markets. Bonds are mixed as US Treasuries sell off a bit with yields up 2bps across the curve and underperforming mild rallies across Europe. Oil prices are up to a buck lower. The dollar is little changed against most crosses, but CAD may be vulnerable ahead of Canadian jobs this morning.
CANADIAN JOBS — MOST EXPECT LITTLE CHANGE
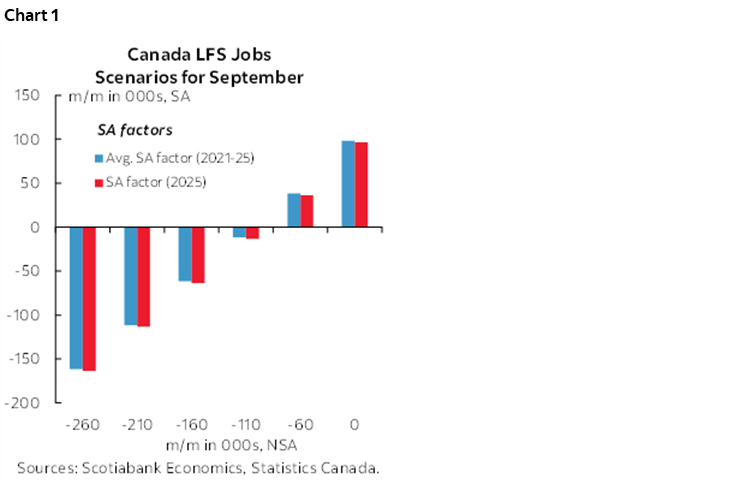
Canada updates the state of the job market in September this morning (8:30amET). Last-minute stragglers boosted the median consensus estimate a little to 10k with a large -30k to +30k set of guesses. Most of the estimates lie within a 0-15k range (Scotia 0k). Most forecasters expect a higher unemployment rate of 6.5% (Scotia 6.5%). Because of client travel I offered a preview ahead of time in Wednesday’s note that I won’t repeat here. Chart 1 shows the range of possible outcomes at differing seasonal adjustment factors and monthly unadjusted employment changes and I’m roughly in the middle.
US CONSUMERS BLEAK ON THE OUTLOOK, BUT STILL SPENDING
The US calendar will only bring out the University of Michigan’s consumer sentiment reading for October (10amET).
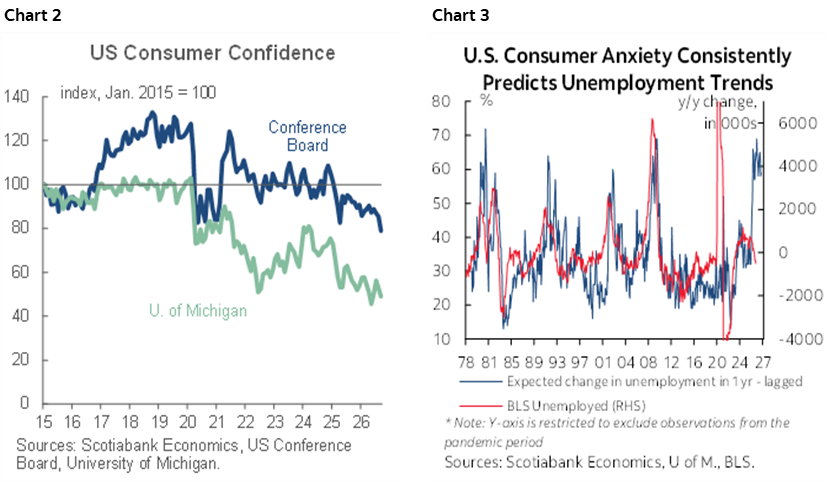
Consumer expectations for future conditions surrounding their finances and the general economy in the near-term and long-term are riding around lows since the Global Financial Crisis (chart 2). At the center of their concerns is what they feel about the job market. The UMich measure of the expected change in the number of unemployed over the coming year remains high and is highly correlated with what actually happens in history (chart 3).
And yet despite all of this, US consumers are still spending. Consumption was up by 3.8% q/q SAAR in Q2 in inflation-adjusted terms and is tracking another milder gain in Q3. They’re doing so by eroding the saving rate albeit that at 4.1% it’s higher than previously thought given recent revisions yet steadily moving lower from over 7% in early 2024.
DISCLAIMER
This report has been prepared by Scotiabank Economics as a resource for the clients of Scotiabank. Opinions, estimates and projections contained herein are our own as of the date hereof and are subject to change without notice. The information and opinions contained herein have been compiled or arrived at from sources believed reliable but no representation or warranty, express or implied, is made as to their accuracy or completeness. Neither Scotiabank nor any of its officers, directors, partners, employees or affiliates accepts any liability whatsoever for any direct or consequential loss arising from any use of this report or its contents.
These reports are provided to you for informational purposes only. This report is not, and is not constructed as, an offer to sell or solicitation of any offer to buy any financial instrument, nor shall this report be construed as an opinion as to whether you should enter into any swap or trading strategy involving a swap or any other transaction. The information contained in this report is not intended to be, and does not constitute, a recommendation of a swap or trading strategy involving a swap within the meaning of U.S. Commodity Futures Trading Commission Regulation 23.434 and Appendix A thereto. This material is not intended to be individually tailored to your needs or characteristics and should not be viewed as a “call to action” or suggestion that you enter into a swap or trading strategy involving a swap or any other transaction. Scotiabank may engage in transactions in a manner inconsistent with the views discussed this report and may have positions, or be in the process of acquiring or disposing of positions, referred to in this report.
Scotiabank, its affiliates and any of their respective officers, directors and employees may from time to time take positions in currencies, act as managers, co-managers or underwriters of a public offering or act as principals or agents, deal in, own or act as market makers or advisors, brokers or commercial and/or investment bankers in relation to securities or related derivatives. As a result of these actions, Scotiabank may receive remuneration. All Scotiabank products and services are subject to the terms of applicable agreements and local regulations. Officers, directors and employees of Scotiabank and its affiliates may serve as directors of corporations.
Any securities discussed in this report may not be suitable for all investors. Scotiabank recommends that investors independently evaluate any issuer and security discussed in this report, and consult with any advisors they deem necessary prior to making any investment.
This report and all information, opinions and conclusions contained in it are protected by copyright. This information may not be reproduced without the prior express written consent of Scotiabank.
™ Trademark of The Bank of Nova Scotia. Used under license, where applicable.
Scotiabank, together with “Global Banking and Markets”, is a marketing name for the global corporate and investment banking and capital markets businesses of The Bank of Nova Scotia and certain of its affiliates in the countries where they operate, including; Scotiabank Europe plc; Scotiabank (Ireland) Designated Activity Company; Scotiabank Inverlat S.A., Institución de Banca Múltiple, Grupo Financiero Scotiabank Inverlat, Scotia Inverlat Casa de Bolsa, S.A. de C.V., Grupo Financiero Scotiabank Inverlat, Scotia Inverlat Derivados S.A. de C.V. – all members of the Scotiabank group and authorized users of the Scotiabank mark. The Bank of Nova Scotia is incorporated in Canada with limited liability and is authorised and regulated by the Office of the Superintendent of Financial Institutions Canada. The Bank of Nova Scotia is authorized by the UK Prudential Regulation Authority and is subject to regulation by the UK Financial Conduct Authority and limited regulation by the UK Prudential Regulation Authority. Details about the extent of The Bank of Nova Scotia's regulation by the UK Prudential Regulation Authority are available from us on request. Scotiabank Europe plc is authorized by the UK Prudential Regulation Authority and regulated by the UK Financial Conduct Authority and the UK Prudential Regulation Authority.
Scotiabank Inverlat, S.A., Scotia Inverlat Casa de Bolsa, S.A. de C.V, Grupo Financiero Scotiabank Inverlat, and Scotia Inverlat Derivados, S.A. de C.V., are each authorized and regulated by the Mexican financial authorities.
Not all products and services are offered in all jurisdictions. Services described are available in jurisdictions where permitted by law.