

ON DECK FOR TUESDAY, NOVEMBER 3rd
KEY POINTS:
- Fragile markets await midterms, Iran, while unimpressed with tech
- Midterms —when results will roll…
- …and beware early misinterpretations that will drive volatility
- Stunning manipulation of the oil market, but traders should know better by now
- BoC’s Macklem likely to fade GDP, oil in today’s testimony
- RBA hiked, indicated it may be done
- US data distractions to include JOLTS, factory orders, vehicle sales
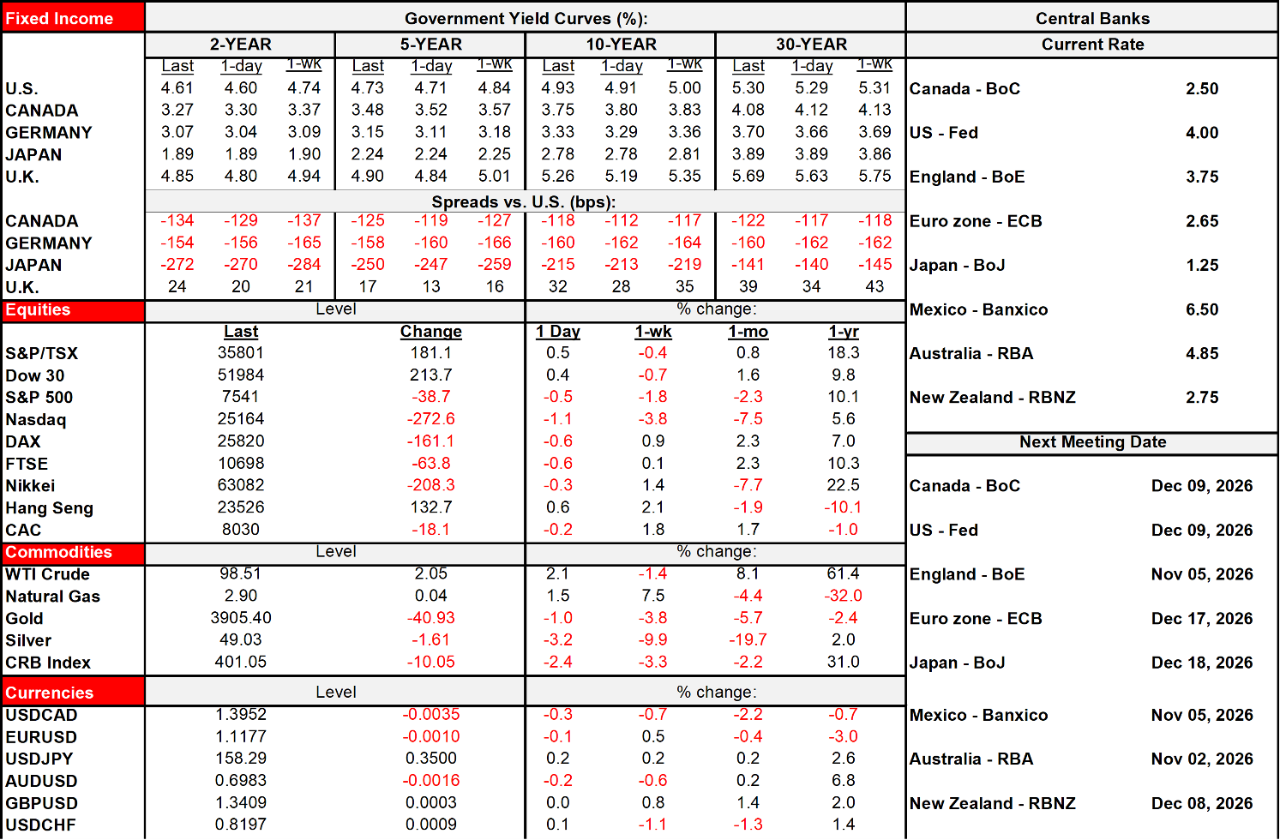
Mixed signals on the Iran war continue to spark volatility in oil, bonds and stocks on midterm election day in the US. After yesterday’s plunge in oil prices, today’s prices are slightly higher by 2% or so. That’s enough to pivot bonds back toward higher yields in the US but particularly Canada and Europe.
Stocks are gently lower almost everywhere partly because of oil, partly because markets were unimpressed by Apple’s beats as sales growth slows and results in China disappointed, and partly because of nervousness toward what happens in the midterms and the ensuing aftermath.
Back to oil. Unquestioning robots believed Trump hook, line and sinker yesterday when he did an about-face on attacking Iran. His social media post played up talks and pointed to lower oil on the day as prices plunged on the back of his own headlines. Most would see through this as an effort to lower energy prices on election day while retaining caution toward the ensuing days given Trump’s constant warnings that he could escalate war again after the vote. The overnight US attacks on Qeshm Island play to this narrative, as do more ships struck by mines in the Strait of Hormuz. Leaning against this is jawboning from Qatar that negotiations are ongoing. They’ve been ongoing time and again to no avail as the divisions are too great. Possible domestic gridlock raises foreign policy risks in my opinion.
MIDTERMS—STAGGERED RESULTS TO DRIVE MARKET VOLATILITY
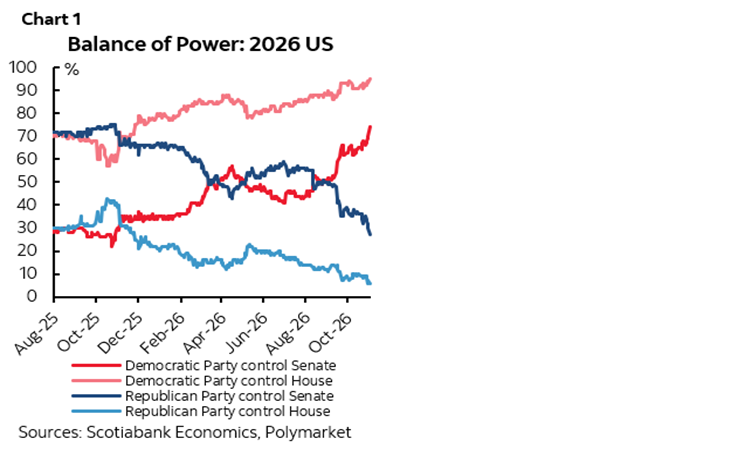
And then settle in tonight for US midterm results to start rolling as polls close in staggered fashion and media outlets are permitted to begin reporting results. The first polls close at 6pmET in parts of Kentucky and Indiana. More shut at 7pmET (Georgia, Virginia, the part of Florida in the eastern time zone, South Carolina and Vermont). Then Ohio, NC and West Virginia at 7:30pmET. 8pmET is the biggest single closing period followed by 9pmET. Polls continue to close at 10pmET and then 11pmET including California. Alaska and Hawaii shut after the midnight bell tolls. It’s an inefficient electoral system and any close races could be subject to recounts and possible court challenges. It’s also very unclear that Trump will accept the results.
Early results could be misleading, such as the so-called ‘red mirage.’ Markets are likely to be volatile as headlines then transition toward counting in true blue country. Unless it’s a real blow-out it could take days or weeks to get the full results including any contested outcomes. Most pundits and pollsters expect a blue House and possibly blue sweep.
They’ve been wrong before. Never count out Democrat dysfunction as we’ve seen in recent days and in the absence of any true leader.
BOC’S MACKLEM WILL PROBABLY FADE POST-HIKE DEVELOPMENTS
BoC Governor Macklem and SDG Rogers are unlikely to say much of anything new in round one of two rounds of testimony before parliamentary committees this week. Macklem’s statement will be released at 11amET and then two hours of scintillating banter will unfold. The only news since the BoC’s rate hike decision last Wednesday has included softer than expected monthly GDP that I think he’ll fade in relation to forward-looking views, and a drop in oil prices that he’ll probably also fade given mixed signals on next steps in the Iran war.
RBA HIKED, MAY BE DONE
The RBA did indeed raise its cash rate target by 25bps to 4.85% in a 6–3 vote as widely expected overnight. Yet the A$ softened and the Australian rates curve rallied post-communications. Why? The statement removed reference to doing what’s necessary “including increased the cash rate target further if needed.” Governor Bullock said “I’d not be interpreting this as saying we’re not going up. I wouldn’t be interpreting it as saying we definitely are going up. We’re basically preserving our options.” Communications further emphasized data dependency and the lagging effects of rate increases. Markets are pricing the RBA as basically done after 125bps of hikes with a peak one-in-four chance of a further hike in 2027Q1 after a hold in December.
MODEST US DATA RISK
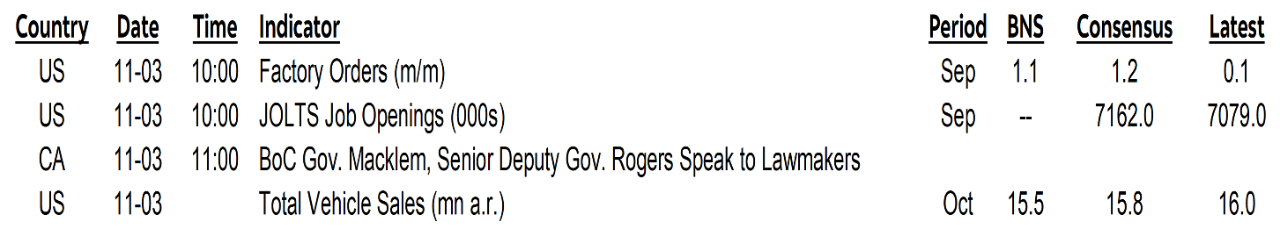
US data will pass the time while markets await midterm coverage. JOLTS job openings during September (10amET) and an expected jump in factory orders for the same month (10amET) will then be followed by an expected dip in vehicle sales by the end of the day.
DISCLAIMER
This report has been prepared by Scotiabank Economics as a resource for the clients of Scotiabank. Opinions, estimates and projections contained herein are our own as of the date hereof and are subject to change without notice. The information and opinions contained herein have been compiled or arrived at from sources believed reliable but no representation or warranty, express or implied, is made as to their accuracy or completeness. Neither Scotiabank nor any of its officers, directors, partners, employees or affiliates accepts any liability whatsoever for any direct or consequential loss arising from any use of this report or its contents.
These reports are provided to you for informational purposes only. This report is not, and is not constructed as, an offer to sell or solicitation of any offer to buy any financial instrument, nor shall this report be construed as an opinion as to whether you should enter into any swap or trading strategy involving a swap or any other transaction. The information contained in this report is not intended to be, and does not constitute, a recommendation of a swap or trading strategy involving a swap within the meaning of U.S. Commodity Futures Trading Commission Regulation 23.434 and Appendix A thereto. This material is not intended to be individually tailored to your needs or characteristics and should not be viewed as a “call to action” or suggestion that you enter into a swap or trading strategy involving a swap or any other transaction. Scotiabank may engage in transactions in a manner inconsistent with the views discussed this report and may have positions, or be in the process of acquiring or disposing of positions, referred to in this report.
Scotiabank, its affiliates and any of their respective officers, directors and employees may from time to time take positions in currencies, act as managers, co-managers or underwriters of a public offering or act as principals or agents, deal in, own or act as market makers or advisors, brokers or commercial and/or investment bankers in relation to securities or related derivatives. As a result of these actions, Scotiabank may receive remuneration. All Scotiabank products and services are subject to the terms of applicable agreements and local regulations. Officers, directors and employees of Scotiabank and its affiliates may serve as directors of corporations.
Any securities discussed in this report may not be suitable for all investors. Scotiabank recommends that investors independently evaluate any issuer and security discussed in this report, and consult with any advisors they deem necessary prior to making any investment.
This report and all information, opinions and conclusions contained in it are protected by copyright. This information may not be reproduced without the prior express written consent of Scotiabank.
™ Trademark of The Bank of Nova Scotia. Used under license, where applicable.
Scotiabank, together with “Global Banking and Markets”, is a marketing name for the global corporate and investment banking and capital markets businesses of The Bank of Nova Scotia and certain of its affiliates in the countries where they operate, including; Scotiabank Europe plc; Scotiabank (Ireland) Designated Activity Company; Scotiabank Inverlat S.A., Institución de Banca Múltiple, Grupo Financiero Scotiabank Inverlat, Scotia Inverlat Casa de Bolsa, S.A. de C.V., Grupo Financiero Scotiabank Inverlat, Scotia Inverlat Derivados S.A. de C.V. – all members of the Scotiabank group and authorized users of the Scotiabank mark. The Bank of Nova Scotia is incorporated in Canada with limited liability and is authorised and regulated by the Office of the Superintendent of Financial Institutions Canada. The Bank of Nova Scotia is authorized by the UK Prudential Regulation Authority and is subject to regulation by the UK Financial Conduct Authority and limited regulation by the UK Prudential Regulation Authority. Details about the extent of The Bank of Nova Scotia's regulation by the UK Prudential Regulation Authority are available from us on request. Scotiabank Europe plc is authorized by the UK Prudential Regulation Authority and regulated by the UK Financial Conduct Authority and the UK Prudential Regulation Authority.
Scotiabank Inverlat, S.A., Scotia Inverlat Casa de Bolsa, S.A. de C.V, Grupo Financiero Scotiabank Inverlat, and Scotia Inverlat Derivados, S.A. de C.V., are each authorized and regulated by the Mexican financial authorities.
Not all products and services are offered in all jurisdictions. Services described are available in jurisdictions where permitted by law.