

ON DECK FOR MONDAY, NOVEMBER 2nd
KEY POINTS:
- Oil down on pre-election headline manipulation
- Canada-US trade talks back on track…
- …but we’ve heard that before
- German retail sales plunge
- Chile’s economy super-accelerated
- US to refresh ISM-mfrg, construction spending
- Canada to update little-watched manufacturing PMI
- RBA to hike again tonight
- Global Week Ahead — Checks and Balances (reminder here)
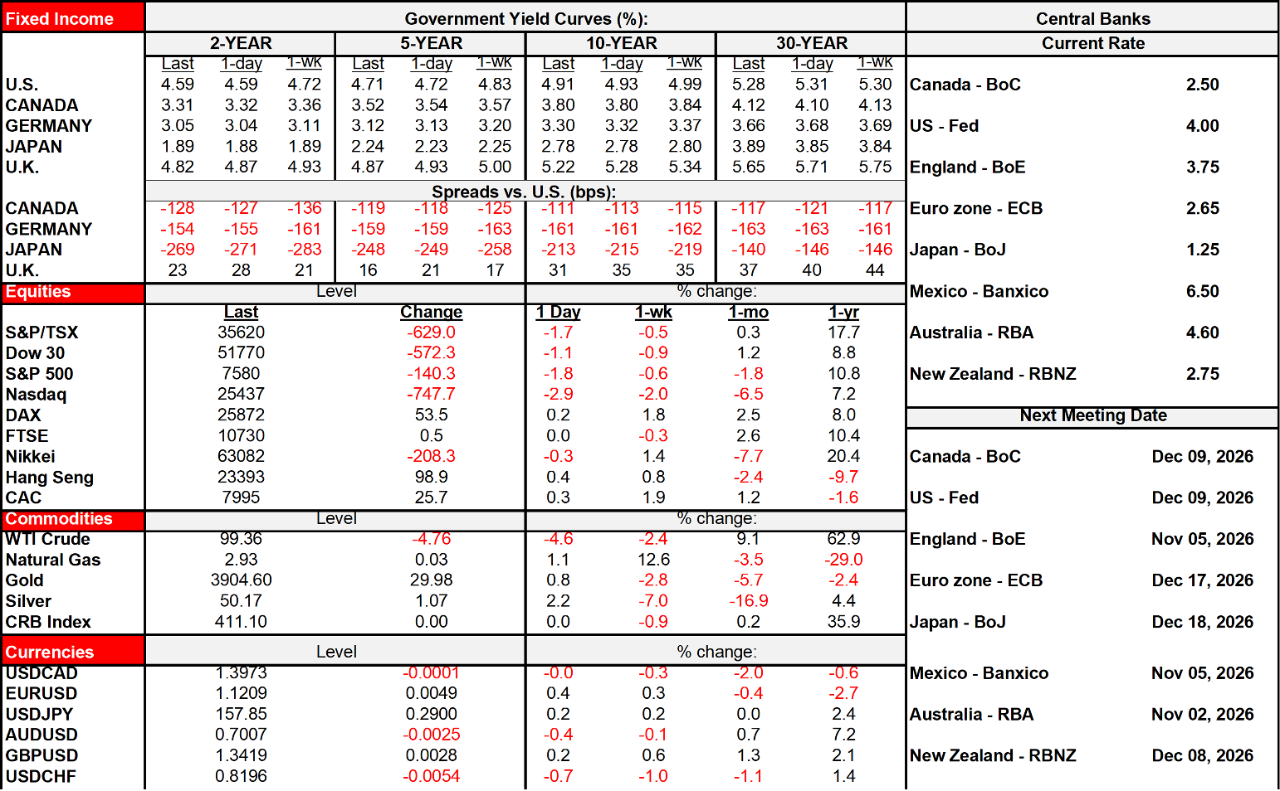
The dominant factor across markets this morning is ongoing manipulation of the energy market. Oil is down by nearly $5 on speculation that Trump is seeking a diplomatic solution with Iran. Who’s driving that speculation? The Trump administration, the day before Americans who haven’t mailed it in already show up to vote. Most other signs point to post-midterms escalation in what in another entry on the list of intractable conflicts.
Bonds are sceptical. US Treasury yields are little changed. European yields are down by up to 5bps mostly outside of bunds. Equities are gently higher across NA futures and European cash.
Data risk was light overnight and we’ll get a few nuggets out of the US and Canada later on this morning. German retail sales volumes plunged -2% m/m in September, reversing the prior 1.2% gain and then some. Chile’s economy super-accelerated in September, given this morning’s GDP proxy that grew by 1.9% m/m SA.
Otherwise, here’s what we face today which is merely passing the time before tomorrow’s US midterms:
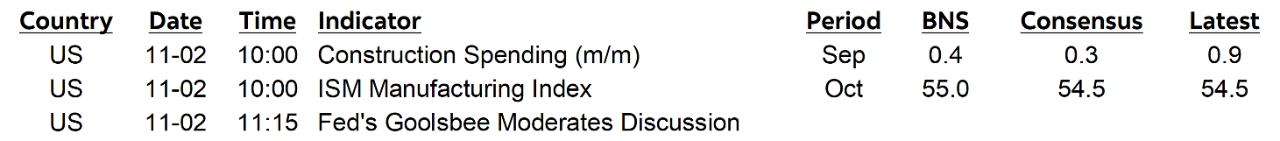
- US ISM-manufacturing for October is due out at 10amET. Moderate growth is expected to continue alongside very high price pressures.
- US construction spending during September faces a high hurdle to post another gain after a strong 1% rise in August (10amET).
- Canada’s manufacturing sector is registering mild growth with October’s little-watched S&P manufacturing PMI due out (9:30amET).
They’re talking again. Canadian PM Carney and Trump spoke over the weekend, and both sides acknowledged progress in trade talks. Be cautious. Trump sounded more optimistic in saying they’re close to a great deal. Carney said they were working toward a possible deal over coming weeks. Trump is obviously motivated by his vote tomorrow. Trump likely wants his signature on a new trade deal which means if it’s a fairly comprehensive CUSMA 2.0 deal, then get it through Congress before the Democrats control at least one of the chambers come January. Canada holds leverage over US politics in that sense. We’ve heard all this before, and the difference would have to be Trump exerting control over Lutnick this time after he played spoiler in the final hours of talks in August.
In an ideal world for the Carney administration, a passable deal could be struck in time for six by-elections that the PM called over the weekend and to be held on December 7th.
Australia’s central bank is widely expected to hike again later on this evening (10:30pmET). CPI recently surprised a touch on the upside and remains too warm even before the full consequences of recently rising oil prices and further upside arrive. Governor Bullock warned in recent parliamentary testimony about materializing upside risks to inflation, while accompanying officials warned that the latest inflation readings were too high and hotter than expected in their August outlook. Hawkish guidance was therefore generally supportive of hike pricing for tonight.
And last, thank you to the National Post for this shout out on our rate call as Scotiabank Economics was the only one to get it right on the Bank of Canada long in advance straight back to last November. Most other media outlets were too busy denying that rates could ever go up and gave little to no airtime for the hawkish case which was a disservice to their readers. There is a long history of Scotiabank Economics outperforming consensus on Canadian rates that goes back to the Global Financial Crisis and its aftermath and throughout the pandemic.
DISCLAIMER
This report has been prepared by Scotiabank Economics as a resource for the clients of Scotiabank. Opinions, estimates and projections contained herein are our own as of the date hereof and are subject to change without notice. The information and opinions contained herein have been compiled or arrived at from sources believed reliable but no representation or warranty, express or implied, is made as to their accuracy or completeness. Neither Scotiabank nor any of its officers, directors, partners, employees or affiliates accepts any liability whatsoever for any direct or consequential loss arising from any use of this report or its contents.
These reports are provided to you for informational purposes only. This report is not, and is not constructed as, an offer to sell or solicitation of any offer to buy any financial instrument, nor shall this report be construed as an opinion as to whether you should enter into any swap or trading strategy involving a swap or any other transaction. The information contained in this report is not intended to be, and does not constitute, a recommendation of a swap or trading strategy involving a swap within the meaning of U.S. Commodity Futures Trading Commission Regulation 23.434 and Appendix A thereto. This material is not intended to be individually tailored to your needs or characteristics and should not be viewed as a “call to action” or suggestion that you enter into a swap or trading strategy involving a swap or any other transaction. Scotiabank may engage in transactions in a manner inconsistent with the views discussed this report and may have positions, or be in the process of acquiring or disposing of positions, referred to in this report.
Scotiabank, its affiliates and any of their respective officers, directors and employees may from time to time take positions in currencies, act as managers, co-managers or underwriters of a public offering or act as principals or agents, deal in, own or act as market makers or advisors, brokers or commercial and/or investment bankers in relation to securities or related derivatives. As a result of these actions, Scotiabank may receive remuneration. All Scotiabank products and services are subject to the terms of applicable agreements and local regulations. Officers, directors and employees of Scotiabank and its affiliates may serve as directors of corporations.
Any securities discussed in this report may not be suitable for all investors. Scotiabank recommends that investors independently evaluate any issuer and security discussed in this report, and consult with any advisors they deem necessary prior to making any investment.
This report and all information, opinions and conclusions contained in it are protected by copyright. This information may not be reproduced without the prior express written consent of Scotiabank.
™ Trademark of The Bank of Nova Scotia. Used under license, where applicable.
Scotiabank, together with “Global Banking and Markets”, is a marketing name for the global corporate and investment banking and capital markets businesses of The Bank of Nova Scotia and certain of its affiliates in the countries where they operate, including; Scotiabank Europe plc; Scotiabank (Ireland) Designated Activity Company; Scotiabank Inverlat S.A., Institución de Banca Múltiple, Grupo Financiero Scotiabank Inverlat, Scotia Inverlat Casa de Bolsa, S.A. de C.V., Grupo Financiero Scotiabank Inverlat, Scotia Inverlat Derivados S.A. de C.V. – all members of the Scotiabank group and authorized users of the Scotiabank mark. The Bank of Nova Scotia is incorporated in Canada with limited liability and is authorised and regulated by the Office of the Superintendent of Financial Institutions Canada. The Bank of Nova Scotia is authorized by the UK Prudential Regulation Authority and is subject to regulation by the UK Financial Conduct Authority and limited regulation by the UK Prudential Regulation Authority. Details about the extent of The Bank of Nova Scotia's regulation by the UK Prudential Regulation Authority are available from us on request. Scotiabank Europe plc is authorized by the UK Prudential Regulation Authority and regulated by the UK Financial Conduct Authority and the UK Prudential Regulation Authority.
Scotiabank Inverlat, S.A., Scotia Inverlat Casa de Bolsa, S.A. de C.V, Grupo Financiero Scotiabank Inverlat, and Scotia Inverlat Derivados, S.A. de C.V., are each authorized and regulated by the Mexican financial authorities.
Not all products and services are offered in all jurisdictions. Services described are available in jurisdictions where permitted by law.