

ON DECK FOR THURSDAY, NOVEMBER 12th
KEY POINTS:
- Tech, Fed-speak in driver’s seat as global markets return
- Waller appears to have little support for upsizing…
- …with more Fed-speak on tap today
- Trump threatens Mexico with more tariffs
- UK data was solid, but sterling, gilts ignored it
- US existing home sales, budget balance, claims on tap
The tech trade and Fed-speak are the main considerations as markets come back from Remembrance Day.
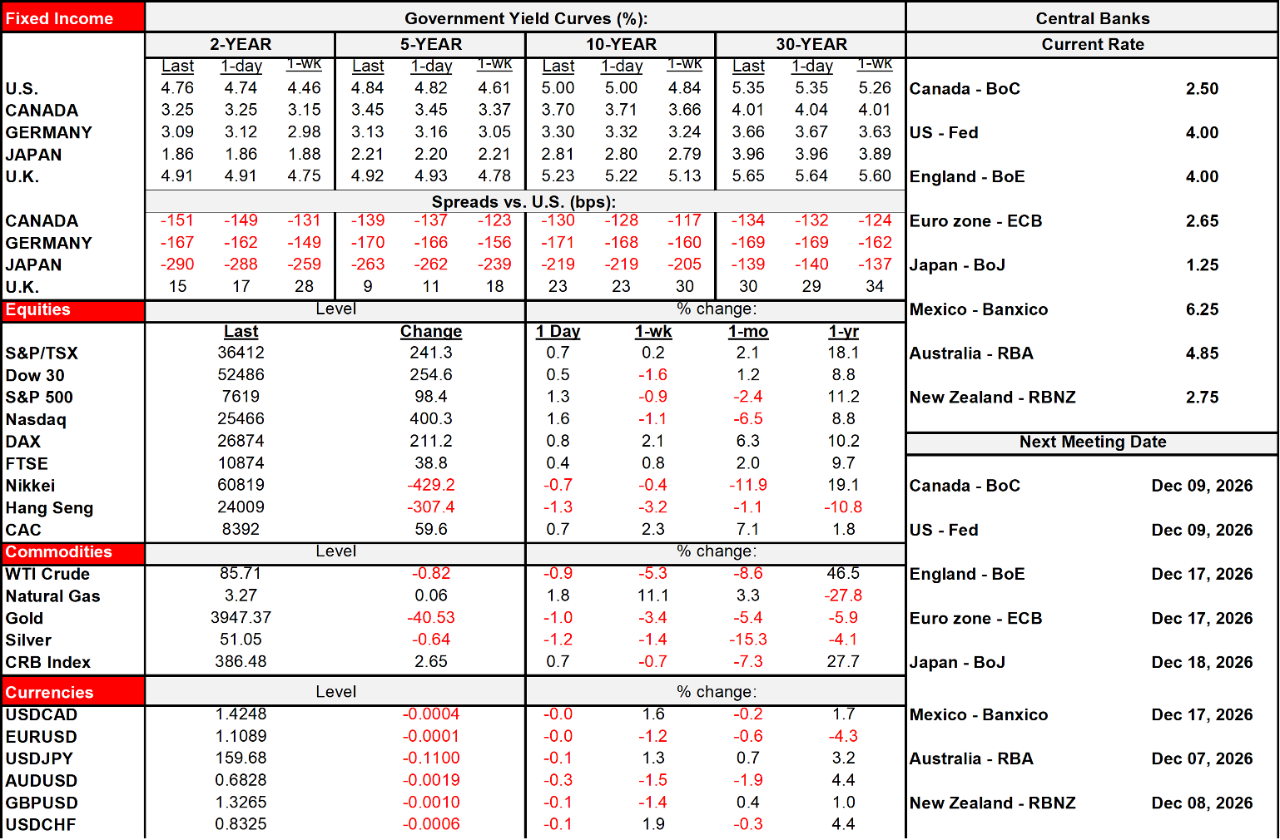
US stock futures are broadly lower and led by the Nasdaq’s nearly 1% dip as markets await the fate of Nvidia’s Jensen Huang and possible implications for Trump’s coming visit to China next week given evidence of spying. European cash markets are broadly higher after a weak Asian session. Short-term US Treasury yields are higher by about 3bps as ongoing Fed-speak continues to be digested. Markets continue to price a few basis points over a quarter-point hike on December 9th although the only Fed-speaker who so far seems to support upsizing is Governor Waller (see below). The effect is continuing to spill into Canada with pricing for the December move on the fence at 13bps.
Oil prices are little changed this morning. The dollar is mixed but the Mexican peso slid after Trump issued this social media threat to double unspecified tariffs against Mexico if it does not curtail caravans.
MORE FED-SPEAK — LITTLE SUPPORT FOR UPSIZING
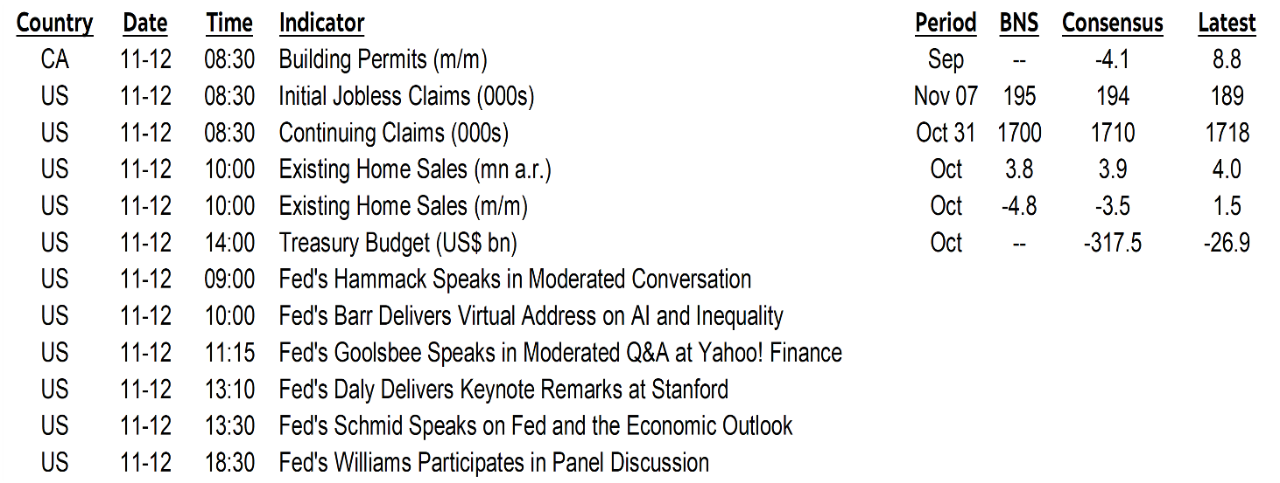
More Fed-speak arrives today to further inform size and pace of future rate changes including the December 9th decision. We’ll hear from Cleveland’s Hammack (9amET), Governor Barr (10amET), Chicago’s Goolsbee (11:15amET), San Fran’s Daly (1:10pmET), KC’s Schmid (1:30pmET) and NY Fed President Williams (6:30pmET).
They are likely to pick up from where the tone left off on Tuesday. Recall that five Fed officials all sounded hawkish to varying degrees but only one seemed to overtly favour upsizing as most used language that would support +25bps at the next meeting.
- Governor Waller is likely to advocate a 50bps hike in December.
- Dallas President Logan supports at least 50bps of further tightening and possibly “more rapidly this winter” but did not weigh in on upsizing.
- Governor Bowman argued further tightening is needed but that the drivers of inflation should abate in 2027.
- Philly’s Paulson said she prefers gradual hikes over sharply accelerating tightening.
- KC’s Schmid said current policy was “fairly accommodative.”
- Chicago’s Goolsbee said he wanted to keep all options on the table and did not commit to anything at the December meeting while sounding generally hawkish on inflation concerns.
Light US data risk includes weekly jobless claims (8:30amET), existing home sales during October (10amET) and the monthly federal budget balance for October (2pmET).
SOLID, BUT LAGGING UK READINGS
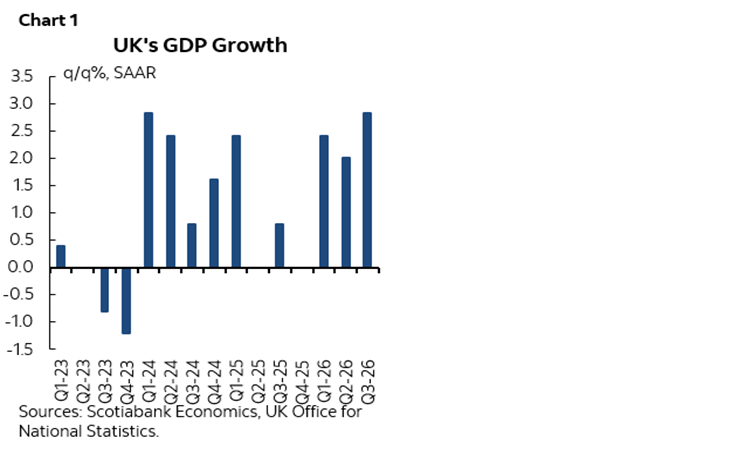
The UK economy put in a decent performance in Q3 and the way the quarter ended but sterling and gilts largely ignored it as stale. GDP was up 0.7% q/q SA nonannualized, matching consensus. Growth drivers included consumer spending (0.6%), exports (1.6%) and investment (1.7%), while surging imports (1.8%) dented growth as a leakage effect from traditional GDP accounting.
The quarter ended on a high note. GDP was up 0.2% m/m (0% consensus) with some help from downward revisions to August (0% instead of 0.1%). Industrial output was up 0.3% m/m, services output expanded 0.2%, construction was up 0.8%, but the trade deficit widened.
DISCLAIMER
This report has been prepared by Scotiabank Economics as a resource for the clients of Scotiabank. Opinions, estimates and projections contained herein are our own as of the date hereof and are subject to change without notice. The information and opinions contained herein have been compiled or arrived at from sources believed reliable but no representation or warranty, express or implied, is made as to their accuracy or completeness. Neither Scotiabank nor any of its officers, directors, partners, employees or affiliates accepts any liability whatsoever for any direct or consequential loss arising from any use of this report or its contents.
These reports are provided to you for informational purposes only. This report is not, and is not constructed as, an offer to sell or solicitation of any offer to buy any financial instrument, nor shall this report be construed as an opinion as to whether you should enter into any swap or trading strategy involving a swap or any other transaction. The information contained in this report is not intended to be, and does not constitute, a recommendation of a swap or trading strategy involving a swap within the meaning of U.S. Commodity Futures Trading Commission Regulation 23.434 and Appendix A thereto. This material is not intended to be individually tailored to your needs or characteristics and should not be viewed as a “call to action” or suggestion that you enter into a swap or trading strategy involving a swap or any other transaction. Scotiabank may engage in transactions in a manner inconsistent with the views discussed this report and may have positions, or be in the process of acquiring or disposing of positions, referred to in this report.
Scotiabank, its affiliates and any of their respective officers, directors and employees may from time to time take positions in currencies, act as managers, co-managers or underwriters of a public offering or act as principals or agents, deal in, own or act as market makers or advisors, brokers or commercial and/or investment bankers in relation to securities or related derivatives. As a result of these actions, Scotiabank may receive remuneration. All Scotiabank products and services are subject to the terms of applicable agreements and local regulations. Officers, directors and employees of Scotiabank and its affiliates may serve as directors of corporations.
Any securities discussed in this report may not be suitable for all investors. Scotiabank recommends that investors independently evaluate any issuer and security discussed in this report, and consult with any advisors they deem necessary prior to making any investment.
This report and all information, opinions and conclusions contained in it are protected by copyright. This information may not be reproduced without the prior express written consent of Scotiabank.
™ Trademark of The Bank of Nova Scotia. Used under license, where applicable.
Scotiabank, together with “Global Banking and Markets”, is a marketing name for the global corporate and investment banking and capital markets businesses of The Bank of Nova Scotia and certain of its affiliates in the countries where they operate, including; Scotiabank Europe plc; Scotiabank (Ireland) Designated Activity Company; Scotiabank Inverlat S.A., Institución de Banca Múltiple, Grupo Financiero Scotiabank Inverlat, Scotia Inverlat Casa de Bolsa, S.A. de C.V., Grupo Financiero Scotiabank Inverlat, Scotia Inverlat Derivados S.A. de C.V. – all members of the Scotiabank group and authorized users of the Scotiabank mark. The Bank of Nova Scotia is incorporated in Canada with limited liability and is authorised and regulated by the Office of the Superintendent of Financial Institutions Canada. The Bank of Nova Scotia is authorized by the UK Prudential Regulation Authority and is subject to regulation by the UK Financial Conduct Authority and limited regulation by the UK Prudential Regulation Authority. Details about the extent of The Bank of Nova Scotia's regulation by the UK Prudential Regulation Authority are available from us on request. Scotiabank Europe plc is authorized by the UK Prudential Regulation Authority and regulated by the UK Financial Conduct Authority and the UK Prudential Regulation Authority.
Scotiabank Inverlat, S.A., Scotia Inverlat Casa de Bolsa, S.A. de C.V, Grupo Financiero Scotiabank Inverlat, and Scotia Inverlat Derivados, S.A. de C.V., are each authorized and regulated by the Mexican financial authorities.
Not all products and services are offered in all jurisdictions. Services described are available in jurisdictions where permitted by law.